

Enrollment Revenue and Monthly Calc
Revenue distributes one occupied-place pool across five age programs. Calc turns annual occupancy and tuition inputs into monthly sales.


The Daycare Center Financial Model is an Excel template for planning tuition, staffing, operating expenses, startup investment, and financial projections. It connects enrollment capacity and age-group tuition rates to monthly calculations and reports.
The illustrated case is an independent, leased, 80-place daycare center in Raleigh, North Carolina, with five age-based programs and a January 2026 launch. Its 2026–2030 projections are estimates, not historical results or guaranteed performance.
The workbook connects tuition inputs with expense, investment, financing, and reporting schedules.
Revenue distributes one occupied-place pool across five age programs. Calc turns annual occupancy and tuition inputs into monthly sales.
COGS & OPEX separates direct, variable, and fixed costs. Payroll plans staff FTE, salaries, and monthly expenses.
CAPEX schedules fit-out, equipment, and depreciation. CapTable records equity; Dashboard controls and Debt schedules accommodate entered financing.
Income Statement, Cash Flow, and Balance Sheet report operating activity and financial position. Summary and Dashboard consolidate key outputs.
Scenarios, Returns, Valuation, Sources & Uses, Benchmarks, charts, and checks support review alongside local diligence.
Revenue depends on planned places, the occupied share of those places, the age-program mix, and monthly tuition per enrolled child.
The case assumes 80 planned licensed places and occupancy rising from 55% in 2026 to 90% in 2030. Occupied child-months are allocated once across five programs, avoiding duplicate enrollment.
The 2026 mix assigns 12.5% to infant care, 15% to toddlers, 20% to two-year-olds, 25% to three-year-olds, and 27.5% to Pre-K. Estimated 2026 monthly tuition ranges from $1,200 for Pre-K to $1,600 for infants.
The Revenue Forecast links planned licensed places, occupied share, age-group enrollment mix, and realized tuition rates to each program’s revenue. Annual inputs flow into the monthly Calc worksheet and consolidate into total daycare sales.
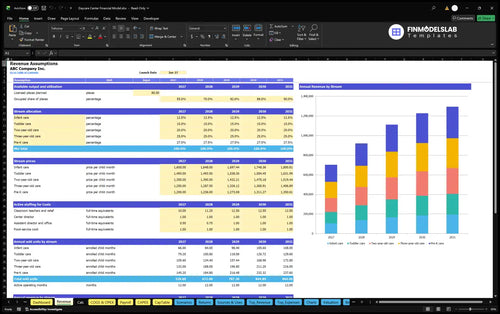
80 planned places × 55% occupied share = 44 enrolled child-months per month; 44 × $1,330 weighted monthly tuition × 12 months = $702,240 annual revenue.
Changing occupancy adjusts the total pool before age-group allocation. Changing tuition affects its program’s allocated child-months, separating pricing from enrollment decisions.
The forecast separates direct care costs, revenue-linked operating expenses, monthly fixed overhead, and personnel expenses to make EBITDA drivers visible.
Direct costs include food at 5% of revenue, classroom consumables at 2%, and substitutes at 1.5%. Variable operating expenses include payment processing at 1.8% and uncollected tuition at 0.4%.
Fixed costs cover premises, utilities, insurance, cleaning, maintenance, software, accounting, marketing, and administration. Monthly rent starts at an estimated $9,000 in 2026, totaling $108,000 over twelve months.
The COGS and Operating Expenses Forecast separates food, classroom supplies, substitutes, payment charges, unpaid tuition, and fixed overhead. Its cost schedules feed the monthly profit-and-loss calculations without mixing these operating categories with startup asset purchases.
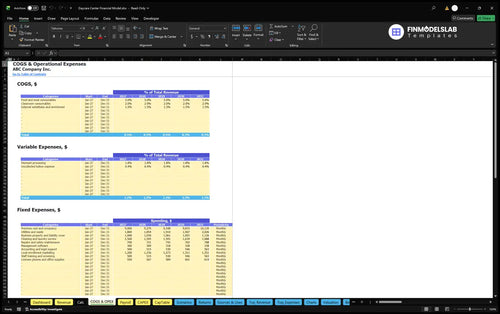
In 2026, COGS totals $59,690, variable expenses $15,449, fixed expenses $204,600, and payroll $507,000. The categories are separate to avoid counting salaries twice.
The Payroll Forecast plans teachers and relief staff, a center director, assistant director and office support, and a food-service cook by FTE and salary. The selected teaching plan grows from 10 to 12.5 FTE across the forecast.
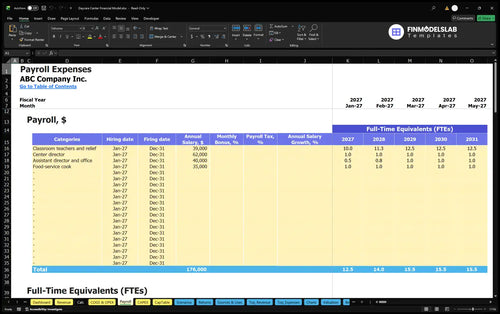
Starting a daycare requires a separate view of premises investment, December 2025 preopening costs, cash funding, and short-term operating balances.
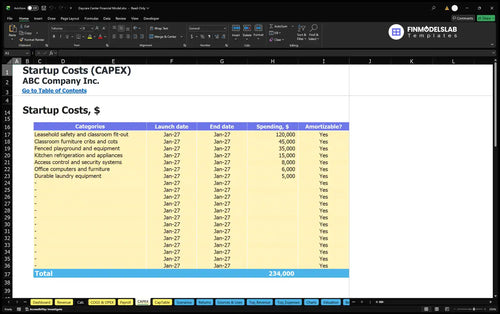
Selected startup assets include $120,000 for leasehold safety and classroom fit-out, $45,000 for furniture and cots, $35,000 for fenced play space, and $15,000 for kitchen appliances. Access systems, office equipment, and durable laundry equipment are additional startup assets.
Preopening deposits, permits, pay, marketing, and legal cash items remain separate from annual expenses. Estimated owner funding is $476,291, based on investment, working capital, and a three-month operating reserve.
The Capital Expenditure Plan organizes daycare fit-out, classroom furniture, playground equipment, and other asset purchases by spending date. The CAPEX schedule also supports depreciation calculations for applicable assets rather than treating all capital purchases as operating costs.
Working-capital inputs specify 1 receivables day, 12 payables days, and 12 inventory days. These affect financial-statement timing without changing EBITDA’s meaning.
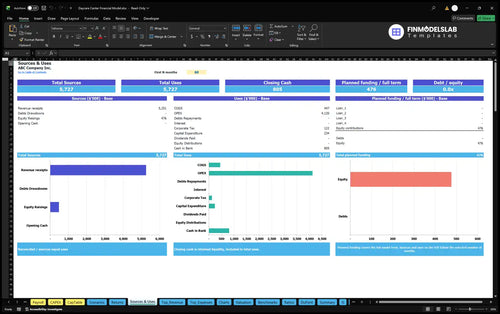
The Sources and Uses of Funds report explains how modeled revenue receipts, owner contributions, debt funding when entered, operating payments, and investment spending relate to available cash. Use it to review funding allocation rather than infer cash sufficiency from EBITDA alone.
The documented base operating case moves from an opening-year EBITDA deficit to positive EBITDA as occupied places and tuition increase.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $702,240 | $786,740 | -$84,500 |
| 2027 | $920,573 | $874,989 | $45,584 |
| 2028 | $1,110,734 | $960,409 | $150,326 |
| 2029 | $1,227,769 | $979,443 | $248,326 |
| 2030 | $1,293,346 | $993,167 | $300,179 |
Illustrative estimates from the supplied Raleigh operating case. Values are rounded to whole dollars; EBITDA is revenue less the stated operating expenses.
Opening-year negative EBITDA reflects low occupancy alongside fixed rent and staffing costs. In 2030, estimated 90% occupancy yields $1,293,346 revenue, $993,167 operating expenses, and $300,179 EBITDA.
EBITDA measures earnings before interest, taxes, depreciation, and amortization. It is not net profit and does not establish cash generated, adequacy of opening funding, or the eventual recovery of the original investment.
The Cash Flow Forecast tracks operating cash movements alongside capital purchases, equity contributions, borrowing when modeled, and debt service. Its monthly reconciliation is the appropriate place to inspect liquidity timing that the EBITDA projection alone cannot establish.
The workbook provides distinct analyses for operating coverage, investment recovery, return on invested capital, and sensitivity to changed assumptions.
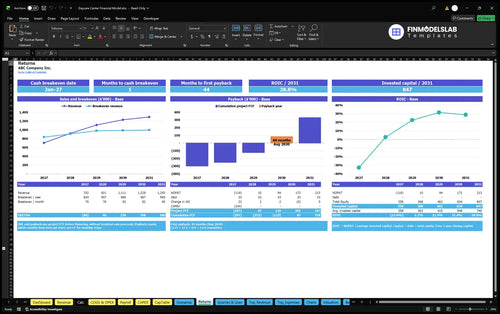
Returns compares revenue with sales break-even, tracks cumulative project cash recovery, and calculates annual ROIC. Operating break-even does not automatically establish cash break-even or investment payback.
The Returns analysis brings together sales break-even, cash break-even timing, investment payback, and annual ROIC calculations. The supplied operating case does not establish a verified payback month or return percentage, so none is asserted here.
Dashboard Low, Base, and High scenarios adjust revenue and cost categories to compare operating margins under different occupancy, staffing, and overhead assumptions.
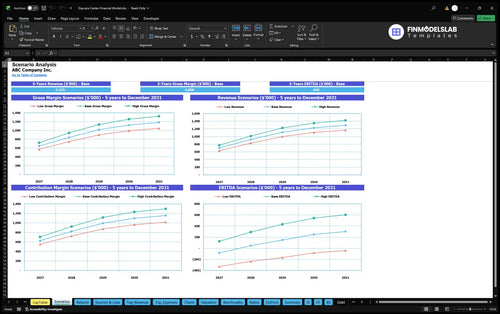
The Financial Scenario Analysis compares Low, Base, and High results for revenue, gross margin, contribution margin, and EBITDA. It helps isolate sensitivity to tuition, utilization, and operating-cost assumptions without treating any scenario as an observed outcome.
Valuation, Benchmarks, ratios, and financial statements offer additional views. Use the workbook for business planning, budgeting, or financing discussions alongside independent licensing and operating due diligence.
These answers explain the workbook’s assumptions, available planning controls, and boundaries of the illustrated case.
Yes. Change planned places and occupied share in Revenue; the model allocates the resulting child-months across the five age programs.
Yes. Infant, toddler, two-year-old, three-year-old, and Pre-K programs each have their own realized monthly tuition assumptions and revenue allocation.
Yes. Payroll includes teacher and relief FTE, center leadership, office support, and a cook, with editable staffing and salary controls.
Yes. CAPEX, working-capital settings, preopening cash items, and owner funding support investment planning separately from the operating expense forecast.
Yes. The workbook includes projected Income Statement, Cash Flow, and Balance Sheet reports. The illustrated numerical case supplied here is documented only through EBITDA.
Yes. Low, Base, and High scenario controls vary revenue and major expense categories, allowing comparisons of projected operating margins and EBITDA.
No. It is an illustrative 2030 operating projection for the stated Raleigh case, not observed earnings, net profit, or verified cash generation.
No. The workbook supports financial planning, but licensing, staffing ratios, local costs, and cash sufficiency require independent checks against actual conditions.
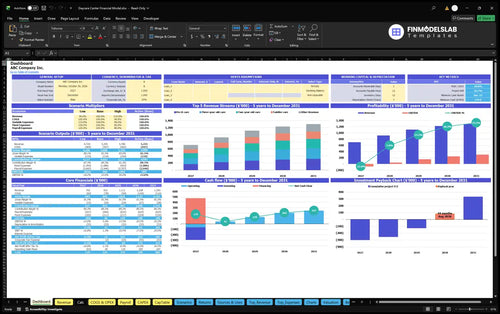
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
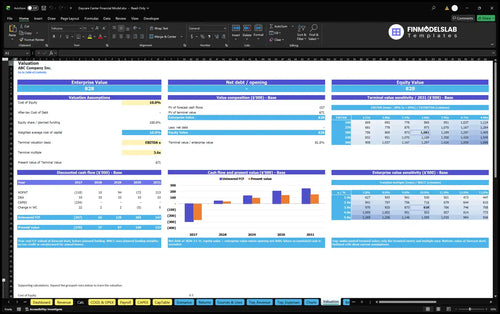
DCF valuation and sensitivity analysis.
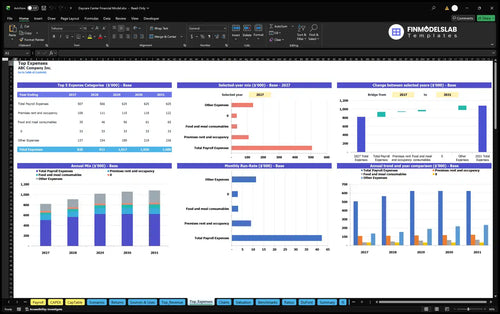
Largest costs and spending trends.
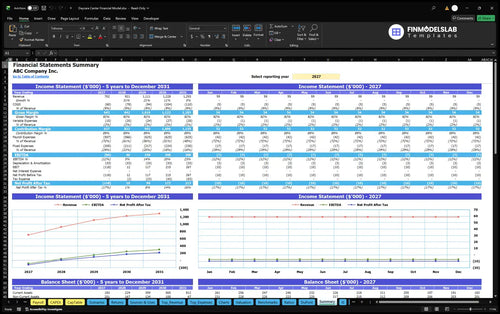
Annual and monthly financial performance.
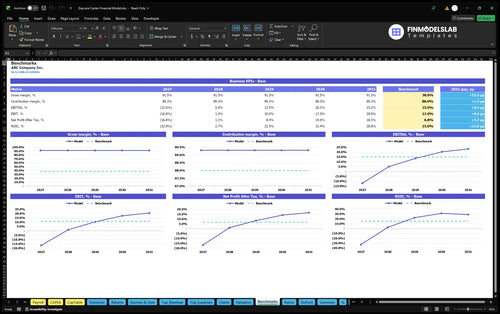
Compare margins and returns to benchmarks.

This template pulled statements and charts out of scattered files and into one clean view. I saved about 3 hours before my lender call because everything was easy to find and share.
I finally had a clear view of margins and break-even without digging through formulas. It made planning a lot easier, and I booked a meeting with my partner the same day to review the numbers.
Low, base, and high cases were ready to compare instead of being a pain to rebuild each time. I cut scenario prep from half a day to under an hour and could explain the assumptions clearly.