

Revenue and Calc
Set harvest capacity, annual utilization, selling prices, live-weight allocations, and launch timing; Calc turns these inputs into monthly channel revenue.


The Fish Farming Financial Model is an Excel financial planning template for a leased, indoor tilapia recirculating aquaculture system (RAS). It builds monthly production, five sales channels, operating costs, staffing, and financial projections from editable operating assumptions.
The illustrated 2026–2030 case models a North Carolina operation with staggered, prestocked fish cohorts, outsourced processing, and an estimated 300,000-live-pound annual nameplate capacity. Its optimistic pricing case increases estimated selling prices by 15% without changing harvest volumes, production mix, or staffing.
The workbook connects aquaculture operating inputs to monthly calculations, financial statements, and investment analysis.
Set harvest capacity, annual utilization, selling prices, live-weight allocations, and launch timing; Calc turns these inputs into monthly channel revenue.
Separate feed, fingerlings, processing, logistics, utilities, rent, and salaried staff. Supporting schedules carry spending and headcount into projected results.
Plan equipment purchases, ownership contributions, and optional financing structures. Debt schedules track draws, interest, and repayments when facilities are entered.
Review the Income Statement, Cash Flow Statement, Balance Sheet, management KPIs, and selected Low, Base, or High scenario.
Use break-even, payback, ROIC, valuation sensitivity, expense trends, ratio analysis, and reconciliations to evaluate assumptions and outputs.
Available RAS harvest capacity, utilization, channel allocations, and selling prices drive the tilapia revenue forecast.
The case uses 25,000 live pounds of monthly nameplate capacity. Estimated annual utilization increases from 55% in 2026 to 85% in 2030; prestocked cohorts allow a normal January 2026 harvest and level monthly output within each forecast year.
Each harvested pound enters only one channel: live tilapia 45%, chilled whole 25%, farmgate whole 15%, fresh fillets 10%, or smoked fillets 5%. Prices for processed products already reflect processing yield, so the model does not sell the same fish twice.
The Revenue Forecast combines available harvest volume, utilization, channel mix, and realized selling prices. Updating these inputs changes the monthly fish-farm sales calculations and the resulting annual revenue by channel.
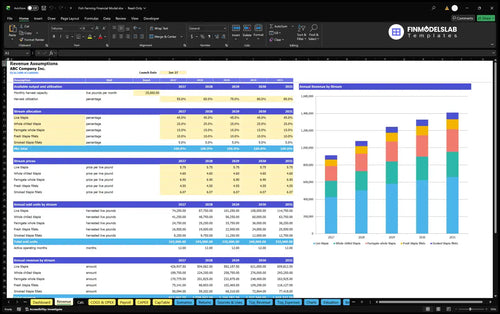
25,000 live pounds × 55% = 13,750 live pounds; 13,750 × $5.5315 estimated realization ≈ $76,058 monthly revenue.
The supplied optimistic scenario applies a 15% selling-price uplift to the original estimated prices while preserving the original quantities, utilization calendar, channel mix, and payroll. This is a planning assumption, not verified market pricing.
Direct production costs, sales-related variable expenses, fixed facility overhead, and payroll determine operating EBITDA.
Direct COGS assumptions include fish feed at 19.13% of revenue, fingerlings at 6.96%, oxygen and buffering at 2.61%, fish health supplies at 1.30%, outsourced processing at 4%, and ice and packaging at 1.74%. These are estimated revenue-linked inputs.
Separate variable expenses cover live haul and cold-chain delivery at 4%, payment processing at 1.2%, and sales development at 2%. Fixed monthly categories include the facility lease, power, water, maintenance, insurance, compliance, software, and sanitation.
The COGS and Operating Expenses forecast distinguishes direct aquaculture production costs, variable selling expenses, and fixed overhead. Changing feed or processing rates and monthly facility spending flows through the cost structure and operating margins.
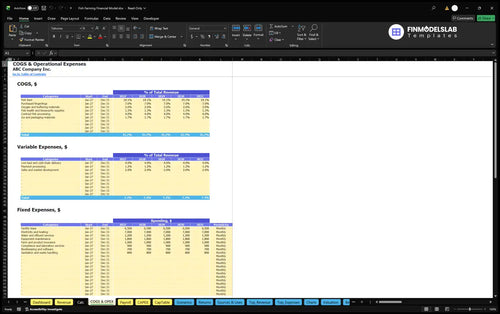
The illustrative lease is $6,500 per month for 12 paid months. As sales scale, revenue-linked feed, fingerling, processing, and distribution expenses rise, while the documented fixed cost and base-pay staffing assumptions stay constant across the five years.
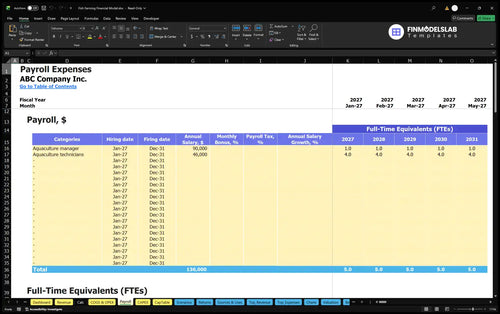
The Payroll Forecast organizes aquaculture staffing by role, full-time equivalents, and compensation. The case assigns one manager at $90,000 and four technicians at $46,000 each, totaling $274,000 in annual base pay.
Opening funding covers physical RAS assets, non-asset launch spending, inventory and trade balances, and an operating reserve.
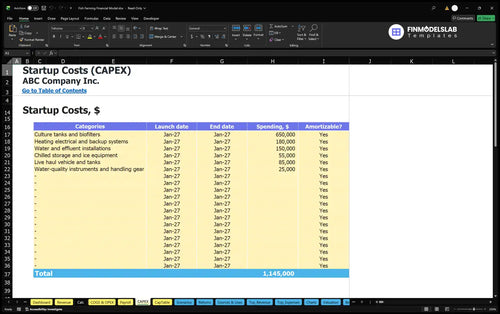
The estimated startup asset budget is $1,145,000, including $650,000 for culture tanks and biofilters, $180,000 for heating and backup systems, and $150,000 for water and effluent installations. Chilled storage, handling gear, and live-haul equipment are also asset categories.
The Capital Expenditure Plan records asset purchases, spending dates, and depreciation treatment. It separates equipment investment from running costs, helping connect aquaculture system commissioning with later financial statements.
The model assumes $117,000 of prelaunch cash costs, $77,821 of opening net working capital, and a $226,176 three-month operating reserve. Accounts-receivable, accounts-payable, and inventory day controls are 7, 12, and 80 respectively.
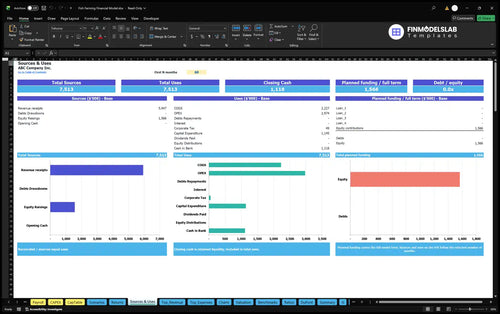
The Sources and Uses of Funds report organizes cash inflows and outflows, including equity, debt when modeled, operating payments, and investment. For this example, estimated initial owner funding is $1,565,997, with no committed external financing assumed.
The selected optimistic pricing case projects higher harvest utilization and operating EBITDA from 2026 through 2030.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $912,698 | $904,704 | $7,993 |
| 2027 | $1,078,643 | $975,960 | $102,683 |
| 2028 | $1,244,588 | $1,047,215 | $197,372 |
| 2029 | $1,327,560 | $1,082,843 | $244,717 |
| 2030 | $1,410,533 | $1,118,470 | $292,062 |
Forecasts, not observed results. Amounts are rounded independently to the nearest dollar.
In the 2030 case, $1,410,533 of projected revenue less $1,118,470 of operating expenses yields approximately $292,062 of EBITDA, a 20.71% EBITDA margin. Compared with the unchanged-price Year 5 case, the 15% price uplift increases forecast sales and operating earnings.
The Income Statement extends beyond EBITDA into depreciation, interest, taxes, and net profit. Those downstream case results have not been verified in the supplied operating brief, so the EBITDA figures above must not be treated as net income.
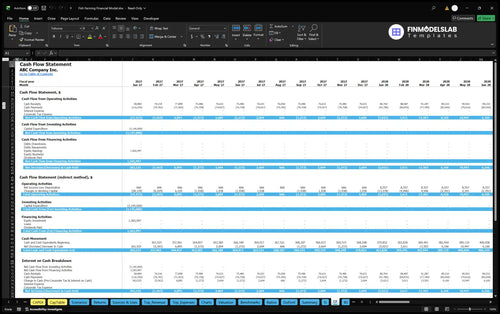
The Cash Flow Forecast separates operating receipts and payments, capital expenditure, equity and debt flows, and closing cash. It helps test whether an aquaculture operation can cover investments and working-capital timing even when projected EBITDA is positive.
Scenario controls on the Dashboard can compare Low, Base, and High revenue and cost multipliers. The accompanying Summary, Charts, Ratios, and model Checks help review statement connections; they do not establish additional case-specific results without recalculation.
The workbook provides separate tools for operating thresholds, cash recovery, invested-capital returns, and valuation sensitivity.
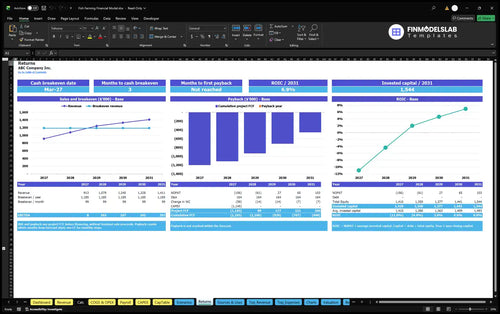
Sales break-even compares forecast revenue with the amount needed to cover modeled costs. Cash break-even concerns when cash generation becomes sufficient, while investment payback follows cumulative project cash flow until the initial outlay is recovered.
Annual return on invested capital (ROIC) measures a different relationship between operating returns and invested capital. None of these results can be inferred reliably from the $292,062 projected 2030 EBITDA alone.
The Returns analysis presents break-even, cash break-even, investment payback, and ROIC as distinct outputs. Use it to examine whether the farm’s operating margin and forecast cash flows justify the equipment and opening capital committed.
Valuation and sensitivity tools offer a discounted cash flow framework, while Debt Controls can model repayment structures when borrowing is entered. No loan commitment, valuation amount, tested payback period, or specific ROIC has been established for this example.
The template is suited to testing harvest volumes, pricing policies, operating costs, and capital requirements before committing resources.
Compare harvest utilization ramps, channel prices, feed costs, processing fees, and fixed utility expenses. A change in one assumption passes from the relevant worksheet to calculations, reports, and decisions about pricing, capacity, staffing, or financing.
This is a scenario for an estimated indoor, owner-operated tilapia RAS with outsourced processing—not verified local market performance. Replace estimated values with supplier quotes, customer terms, site utility estimates, and actual biological and production data before relying on projections.
Answers about editable assumptions, operating results, and the financial reports included in the workbook.
The example covers a leased indoor North Carolina tilapia RAS with staggered cohorts, outsourced processing, and estimated annual harvest capacity of 300,000 live pounds.
Monthly harvest capacity is multiplied by annual utilization, then allocated once among five sales channels and priced using their estimated live-weight realization.
Yes. Revenue inputs and Dashboard scenarios support alternative prices, utilization assumptions, and revenue or cost sensitivities.
Yes. Payroll schedules track staffing and compensation, while COGS & OPEX separates feed, fingerlings, outsourced processing, delivery, and fixed farm expenses.
Yes. The workbook includes projected Income Statement, Cash Flow Statement, and Balance Sheet reports, with supporting investment and financing schedules.
No. It is 2030 EBITDA in the optimistic pricing case; depreciation, interest, taxes, and net profit are separate calculations and are unverified for this supplied case.
Yes. CapTable records equity contributions, and Dashboard Debt Controls feed repayment schedules when loan assumptions are entered. The example assumes owner funding without committed external debt.
No. Returns tools calculate break-even, payback, and ROIC, but the supplied operating brief does not verify their case-specific values.
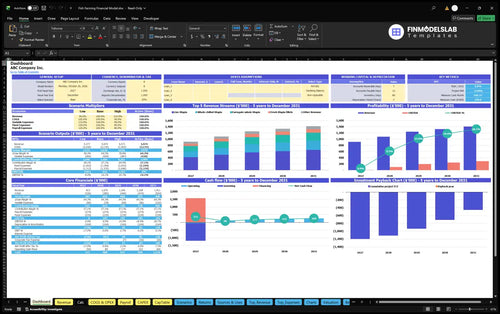
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
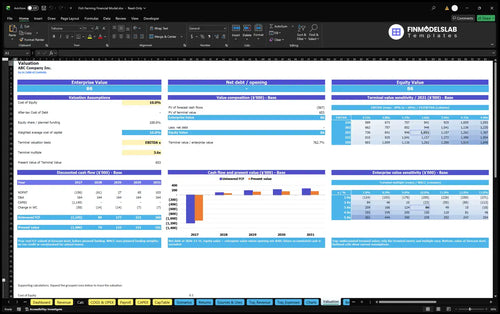
DCF valuation and sensitivity analysis.
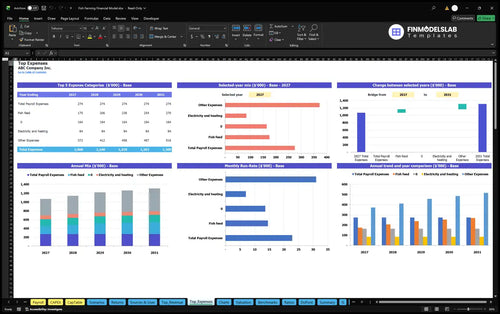
Largest costs and spending trends.
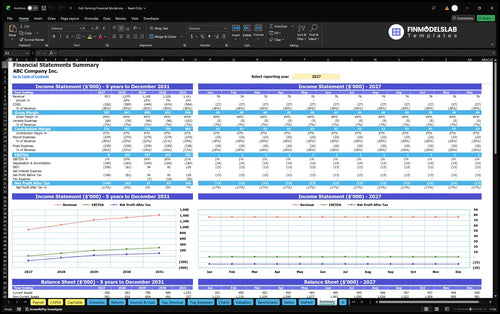
Annual and monthly financial performance.
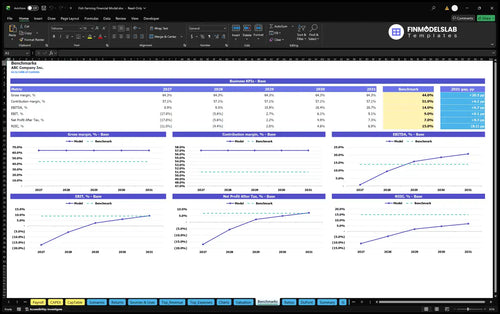
Compare margins and returns to benchmarks.

I’m not strong with advanced Excel, so this template made the model easy to follow and edit. I was able to update the inputs without getting lost in formulas.

Building the forecasts by hand would have taken me days, but this template cut that down to an afternoon. I had a clean five-year view ready for a meeting the same day.
The pricing, feed costs, and growth inputs were all in one place, so the model finally felt organized. That made it much easier to review the numbers and talk through them with my partner.