

Revenue & Calc
Set fleet capacity, utilization, seasonality, training mix, and hourly prices; monthly calculations allocate a shared aircraft-hour pool.


The Flight School Financial Model is an Excel planning template for an independent Central Florida flight-training operator. It turns aircraft capacity, utilization, hourly prices, costs, and staffing into a 2026–2030 forecast.
The example models a Part 61-style school operating four owned, used IFR-equipped Cessna 172 aircraft. It covers flight instruction and rental, excluding airline academy services, simulators, student housing, and separately billed ground school.
Linked operating schedules, financial statements, and decision reports turn flight-hour assumptions into a connected planning workbook.
Set fleet capacity, utilization, seasonality, training mix, and hourly prices; monthly calculations allocate a shared aircraft-hour pool.
Plan fuel, routine maintenance, instructor delivery pay, payment processing, marketing, premises, insurance, and other recurring school expenses.
Budget management and administrative FTE separately from contractor instructors, and schedule aircraft purchases, equipment spending, and depreciation.
Review KPIs and Low, Base, and High cases, plus Dashboard debt controls.
Review projected Income Statement, Cash Flow Statement, Balance Sheet, and a consolidated Summary, supported by reconciliation checks.
Explore break-even, project payback, ROIC, valuation, and funding analysis.
Revenue starts with one shared fleet capacity pool, then allocates flown hours to five mutually exclusive flight services and their hourly prices.
The model schedules four aircraft for eight hours per day and 26 service days per month. Utilization rises from 40% in 2026 to 65% in 2030, reflecting weather, downtime, and unfilled bookings.
Hour allocation is 5% discovery flights, 40% private pilot dual, 25% instrument dual, 15% commercial dual, and 15% solo rental. Corresponding wet hourly rates are $180, $230, $250, $245, and $180, producing a blended rate of $227.25 per aircraft hour.
The Revenue Forecast shows aircraft availability, utilization, service-hour mix, and wet hourly pricing. Its monthly Calc schedule applies the 12 seasonal multipliers and launch timing before consolidating the resulting service revenue into annual projections.
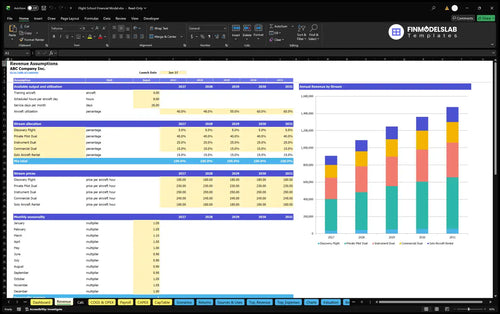
4 aircraft × 8 hours/day × 26 days/month × 12 months × 40% utilization × $227.25 per flown hour ≈ $907,546 of 2026 revenue.
The 2026 case allocates about 3,994 flown hours across the five services without duplication. Nominal prices remain flat, and monthly seasonality changes revenue timing.
Dual prices include instruction and 0.30 paid briefing hour per dual flight hour; solo rental excludes instruction. The model excludes separate student-volume and ground-school sales.
The operating model links direct flying costs to delivered aircraft hours, then adds revenue-based expenses, fixed overhead, and separately budgeted employees.
Each flown hour consumes 8.5 gallons of fuel at $6.50 per gallon and incurs $35 of routine maintenance. Instructors receive $50 per contact hour, with 1.30 paid hours per dual flight hour.
Direct costs total $581,069 in 2026. Payment processing at 2.5% of revenue and enrollment marketing at 2% add $40,840 of variable expenses.
The COGS and Operating Expenses Forecast separates aircraft fuel, routine maintenance, contract instructor costs, transaction charges, marketing, and fixed school overhead. This separation shows which expenses move with flying activity or revenue and which continue when utilization falls.
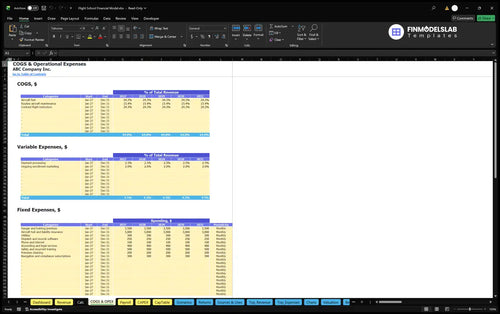
Annual fixed expenses are $102,600, covering premises, insurance, utilities, software, professional services, safety training, cleaning, and subscriptions. Hangar and premises are budgeted at $3,500 monthly.
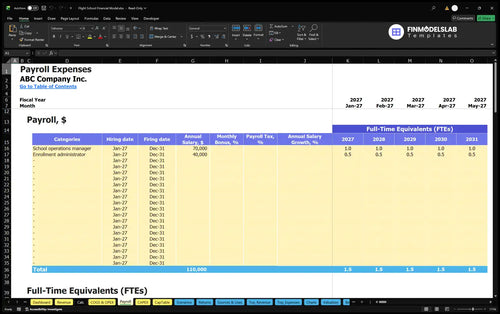
Payroll includes one operations manager at $70,000 annually and 0.5 enrollment-administrator FTE at $40,000 per full-time equivalent. Total annual base payroll is $90,000; contract instructors remain exclusively in COGS.
The Payroll Forecast tracks manager and enrollment-administrator FTE, salary assumptions, employment dates, and personnel costs. This case excludes employer taxes, benefits, and personal taxes.
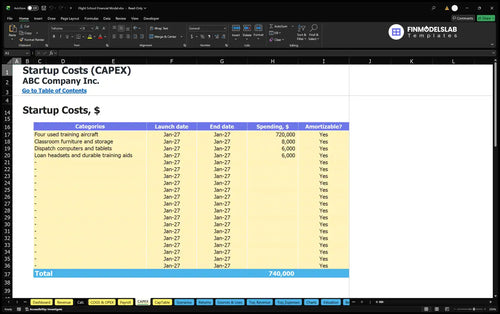
Opening aircraft purchases, other startup uses, and owner equity are planned separately from recurring flight-training operating expenses.
Startup assets include $720,000 for four used aircraft, $8,000 in classroom furniture, $6,000 in dispatch devices, and $6,000 in headsets and training aids, totaling $740,000.
Other opening cash covers a refundable deposit, prebuy inspections, ferry costs, formation, marketing, staff setup, and website/software setup. These expenses are separate from annual operations.
The Capital Expenditure Plan schedules aircraft and durable training-equipment purchases, classifies depreciable items, and calculates related depreciation and net book value. Asset spending affects investing cash flows and the balance sheet rather than being treated entirely as current-period EBITDA expense.
Initial owner funding is $985,232 for assets, startup spending, opening fuel stock, and a three-month operating reserve. The case has no committed outside financing; Dashboard debt controls allow alternatives.
Receivable, payable, and inventory days are all zero; flights are paid when delivered. Working-capital settings do not establish that future cash balances will suffice.
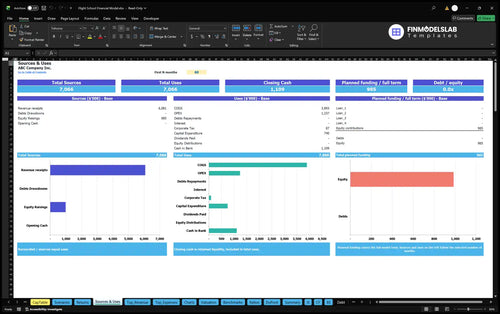
The Sources and Uses of Funds report reconciles equity, any modeled borrowing, operating payments, capital spending, and retained cash. It separates money raised to fund the school from revenue earned by flying.
The documented Base planning case grows revenue as utilization rises while keeping the four-aircraft fleet and nominal hourly prices unchanged.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $907,546 | $814,508 | $93,037 |
| 2027 | $1,089,055 | $938,890 | $150,165 |
| 2028 | $1,247,875 | $1,047,724 | $200,151 |
| 2029 | $1,361,318 | $1,125,463 | $235,856 |
| 2030 | $1,474,762 | $1,203,201 | $271,561 |
Illustrative planning outputs, not historical results. Rounded whole-dollar amounts may differ slightly when subtracted.
In 2026, $907,546 of modeled training and rental revenue less $814,508 of operating expenses produces $93,037 of EBITDA. By 2030, the Base case reaches $1,474,762 of revenue and $271,561 of EBITDA as utilization rises to 65%.
By 2030, each aircraft flies about 135 hours monthly, an ambitious assumption to assess against weather, maintenance, instructors, and demand. These are estimates, not observed outcomes.
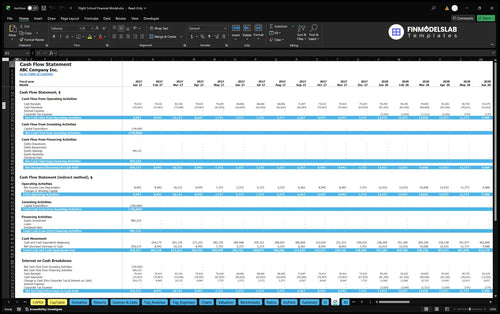
The Cash Flow Forecast shows cash receipts and payments across operating, investing, and financing activities, including projected opening and closing cash. Use it alongside startup spending and funding schedules because positive EBITDA does not by itself establish liquidity or cash sufficiency.
Linked Returns and valuation reports help compare operating resilience, cash recovery, and investment outcomes without equating any of them with EBITDA.
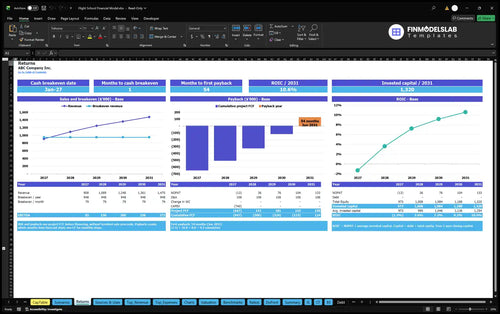
The Returns report separates operating sales break-even, cash break-even, investment payback, and annual ROIC. None follows directly from EBITDA alone.
The Valuation report uses discounted unlevered free cash flow and terminal assumptions for enterprise and equity values, with sensitivity analysis. Its outputs are estimates, not verified sale prices.
The Break-Even, Payback and ROIC report compares revenue with break-even requirements, cumulative project free cash flow, and annual return on invested capital. The documented example supplies no verified payback month or ROIC figure, so those outcomes must be read from the recalculated workbook.
Use the model to test aircraft utilization, training mix, rates, staffing, capital investment, and funding choices. Linked financial statements and scenario comparisons help assess a launch or expansion.
The supplied case is an owner-funded four-aircraft school through 2030. Customize assumptions and review cash flow, financing, and working capital separately from operating EBITDA.
These answers clarify the business scope, editable assumptions, and financial reports included in the workbook.
Yes. Revenue inputs include aircraft count, scheduled daily hours, service days, annual utilization, calendar seasonality, revenue mix, and hourly rates.
No. The supplied example is capacity-based: delivered aircraft hours drive revenue, and it has no separate student-volume control.
No. Contract instructor delivery pay is a direct COGS item; the operations manager and enrollment administrator are budgeted separately in Payroll.
No. Aircraft and durable equipment purchases are scheduled through CAPEX and investing cash flows, with depreciation treated separately from EBITDA.
Yes. It includes linked projected Income Statement, Cash Flow Statement, and Balance Sheet reports, but the supplied Base brief provides numeric results only through EBITDA.
Yes. Dashboard debt controls and the Debt schedule can model financing facilities; the supplied case itself assumes owner funding with no committed outside financing.
No. The documented operating results end at EBITDA; net profit, payback, ROIC, and cash sufficiency require separate recalculation and review of their respective reports.
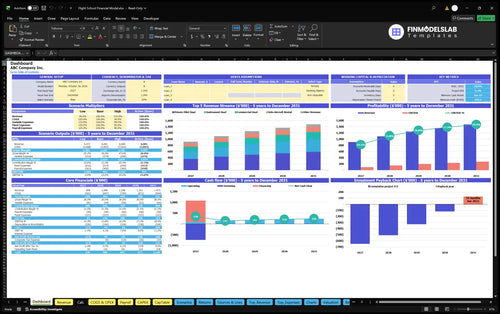
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
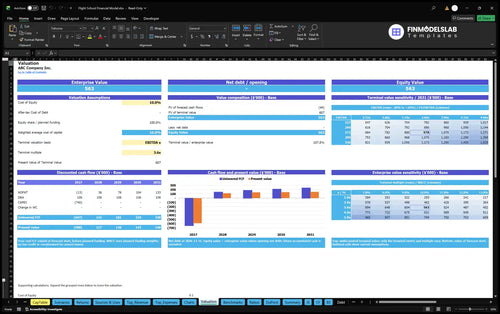
DCF valuation and sensitivity analysis.
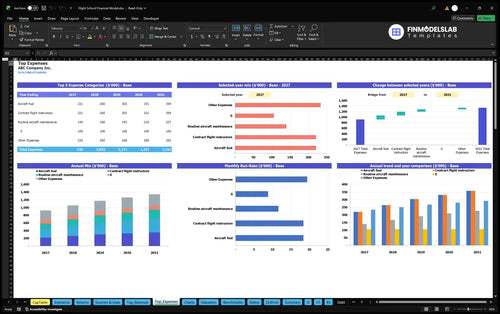
Largest costs and spending trends.
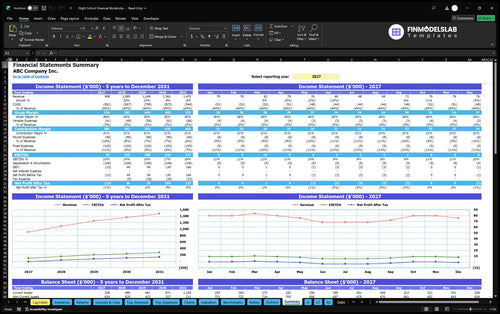
Annual and monthly financial performance.
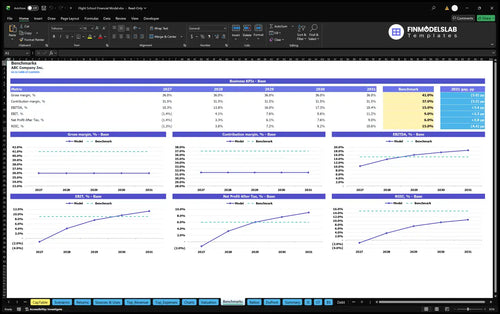
Compare margins and returns to benchmarks.

This template helped me organize pricing, costs, and growth assumptions without digging through scattered tabs. I saved about 4 hours on setup and could finally explain the model cleanly.

I could see runway and likely shortfalls much sooner, which made planning a lot less stressful. It turned a messy cash view into something I could share with my team in one meeting.
The low, base, and high cases were easy to compare instead of being a manual chore. I cut scenario work from an afternoon to under an hour, and the numbers stayed consistent.