

Revenue and Calc
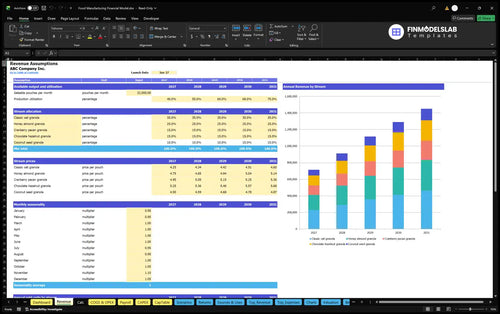
Set saleable production capacity, five flavor shares, wholesale prices, seasonal multipliers, and annual utilization. The monthly calculation schedule allocates the shared pouch pool and consolidates sales.


The Food Manufacturing Financial Model is an Excel template for planning a regional granola production business from pouch capacity and wholesale pricing through operating expenses, staffing, EBITDA, and financial reporting. It links editable operating assumptions to monthly calculations and annual projections.
The illustrated case uses one semi-automatic production line in a leased 5,000-square-foot Columbus, Ohio facility. Five 12-ounce granola flavors share one 32,000-pouch monthly saleable-capacity pool, with regional wholesale distribution and a 2026–2030 forecast beginning January 31, 2026.
Connected worksheets turn production choices into operating projections, financial statements, and decision-oriented reports.
Set saleable production capacity, five flavor shares, wholesale prices, seasonal multipliers, and annual utilization. The monthly calculation schedule allocates the shared pouch pool and consolidates sales.
Plan ingredients, packaging, production utilities, trade allowances, outbound freight, fixed overhead, and staff costs in separate schedules. Review how each category contributes to operating expenses.
Enter equipment investments, their dates, owner contributions, and optional debt facilities. Supporting schedules distinguish asset purchases, equity, principal repayment, and interest.
Review the Income Statement, Cash Flow Statement, Balance Sheet, reconciliations, and management Dashboard. Additional reports cover scenarios, break-even, returns, valuation, and financial ratios.
One production pool determines total saleable pouches; flavor allocations and wholesale prices determine the sales value.
The model starts with 32,000 saleable pouches per month, applies annual utilization of 40%, 50%, 60%, 68%, and 75%, and then applies a repeating monthly seasonal profile. It does not add independent demand forecasts that could overstate the line’s capacity.
The output is allocated 35% classic oat, 25% honey almond, 15% cranberry pecan, 15% chocolate hazelnut, and 10% coconut seed granola. Each flavor’s monthly pouches are multiplied by that year’s wholesale pouch price, and the five streams sum to revenue.
The Revenue Forecast connects capacity, utilization, seasonal multipliers, flavor allocations, and wholesale selling prices to monthly pouch sales and annual revenue. Change these inputs to see how production mix and price increases alter projected sales.
32,000 pouches/month × 40% utilization × 12.0 seasonal-month equivalents × $4.655 weighted wholesale price/pouch = $715,008 annual revenue.
In 2026, the example wholesale prices range from $4.25 for classic oat to $5.25 for chocolate hazelnut. The weighted $4.655 price reflects all five allocation shares; it is not an additional product price or a second production stream.
Direct costs, variable selling costs, fixed overhead, and base salaries remain separate so each payment is counted once.
Estimated direct costs total 42% of revenue: ingredients and inbound freight 30%, packaging 8%, production gas and electricity 2.5%, and cleaning consumables 1.5%. Variable expenses total 10.3%, including brokers, trade promotions and returns, outbound freight, transaction fees, and credit losses.
The COGS and Operating Expenses forecast organizes production-related direct costs, revenue-linked selling expenses, and monthly fixed overhead. Separate categories allow margin sensitivity checks as pouch volume grows without mixing trade allowances or outbound shipping into ingredient costs.
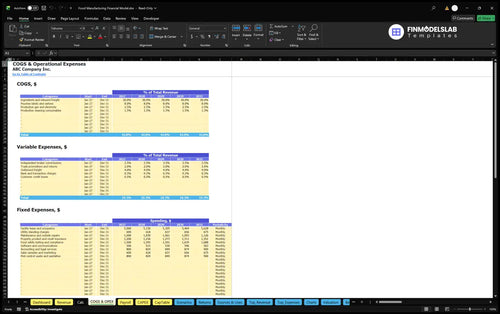
Fixed costs include the lease, standing utilities, maintenance, insurance, testing and compliance, sanitation, software, professional services, and marketing. Facility lease and occupancy begin at $5,000 per month in the 2026 illustration; total fixed operating costs are $144,000 for that year.
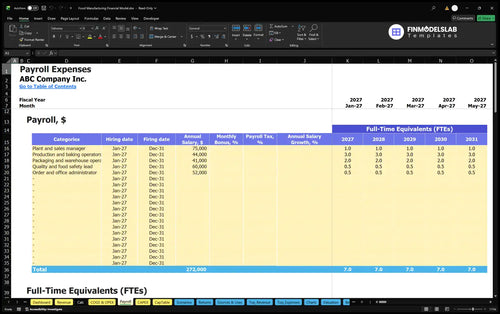
The Payroll Forecast models staffing FTE, role-specific salaries, hiring dates, and personnel expenses. This manufacturing case uses seven annual-average FTE across plant management, production, packaging, quality, and administration, with $345,000 of annual base payroll.
Opening equipment, preopening spending, inventory funding, and owner contributions serve different purposes from recurring EBITDA.
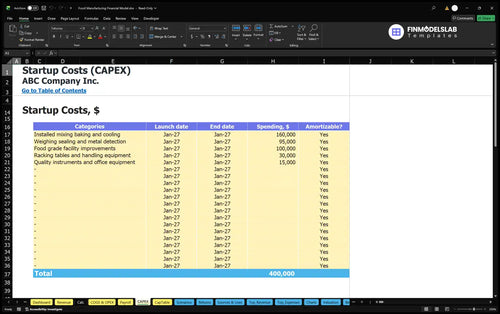
The illustration includes $400,000 in startup assets, including $160,000 for mixing, baking, and cooling equipment; $95,000 for weighing, sealing, and metal detection; $100,000 in facility improvements; and $30,000 for handling equipment. Other assets include quality instruments and office equipment.
The Capital Expenditure Plan records equipment and facility investments, acquisition dates, and depreciation settings. Use it to distinguish the initial manufacturing line and later asset spending from the recurring costs used in the operating EBITDA forecast.
A separate $53,000 covers distinct preopening cash items such as lease deposits, recipe and label development, permits, safety training, and launch promotion. Working-capital controls use 27 receivable days, 18 payable days, and 41 inventory days to model cash tied up in operations.
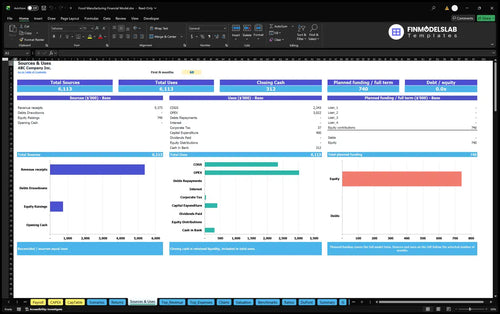
The Sources and Uses of Funds report reconciles operating cash receipts, owner equity, any modeled borrowing, investment spending, and payments. The example enters $740,238 of initial owner funding and no committed external financing; the reserve is not a demonstrated peak cash requirement.
In this example scenario, increasing utilization and wholesale prices shift operating EBITDA from a loss in 2026 to a gain in 2028.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $715,008 | $862,949 | -$147,941 |
| 2027 | $911,635 | $970,105 | -$58,470 |
| 2028 | $1,115,842 | $1,081,355 | $34,487 |
| 2029 | $1,289,905 | $1,176,973 | $112,932 |
| 2030 | $1,451,150 | $1,266,025 | $185,125 |
Planning estimates for the documented case, rounded to whole dollars; displayed rounding can produce small differences.
The projected 2026 EBITDA loss of $147,941 reflects low initial utilization against fixed overhead and base payroll. By 2030, modeled revenue reaches $1,451,150 and EBITDA reaches $185,125 as the production line is used more fully.
EBITDA measures operating earnings before depreciation, interest, and taxes. It is not net profit, free cash flow, a verified return on invested capital, or proof that the opening funding covers the highest cash deficit.
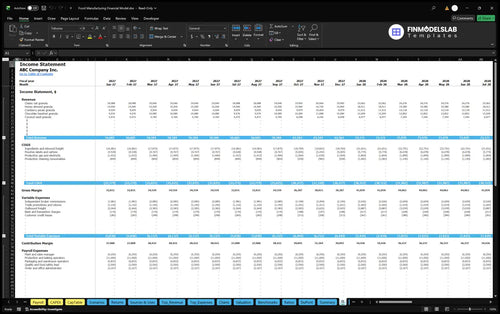
The Projected Income Statement presents revenue, direct costs, operating expenses, payroll, EBITDA, and subsequent accounting lines. It lets users trace operating margins into a wider profit-and-loss forecast without treating the displayed EBITDA figures as net earnings.
Use the 27-day receivables assumption and 41-day inventory assumption to evaluate why wholesale growth can increase cash requirements. The 18-day payables setting also affects payment timing; none of these working-capital days changes the definition of EBITDA.
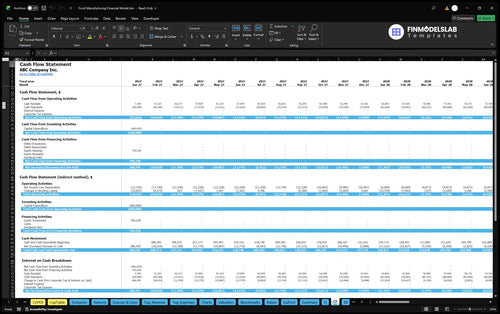
The Cash Flow Forecast separates operating cash movement from equipment purchases, owner contributions, borrowing, debt service, and the opening-to-closing cash balance. Review it when testing whether cash collections and inventory financing support production growth.
Returns and scenario reports examine distinct decisions that cannot be inferred from a positive EBITDA figure alone.
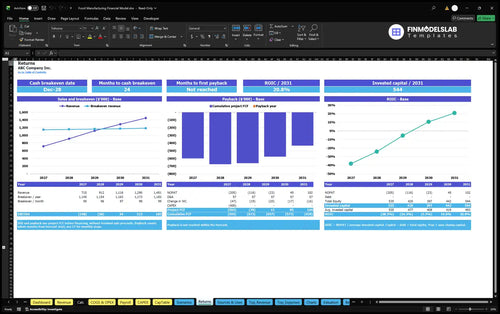
The Returns report distinguishes sales break-even from cash break-even, examines cumulative investment cash flows for payback, and calculates annual ROIC. It does not establish a payback month or return percentage from the operating assumptions quoted here.
The Returns analysis compares modeled sales with break-even requirements, tracks project and cumulative free cash flow for investment payback, and reports return on invested capital. These are separate tests of operating coverage, cash recovery, and investment efficiency.
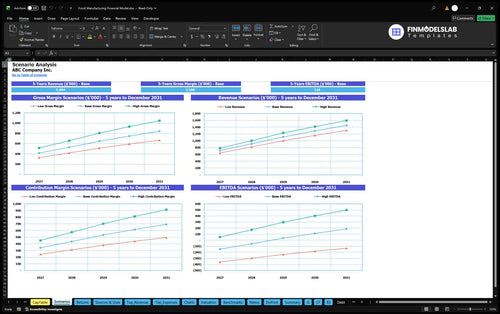
Low, Base, and High Dashboard controls vary revenue, direct costs, variable expenses, fixed expenses, and payroll. Compare how a slower utilization ramp or greater cost pressure affects EBITDA, then use the financing schedules and Cash Flow to evaluate resulting liquidity effects.
The Financial Scenario Analysis compares Low, Base, and High revenue, gross margin, contribution margin, and EBITDA. Change Dashboard multipliers to explore operating downside and upside without mistaking scenario comparisons for guaranteed manufacturing results.
Other supported reports include discounted cash flow valuation with sensitivity analysis, annual financial ratios, industry KPI benchmark comparisons, and charts. They extend review beyond EBITDA, but this product description does not assert their case-specific outputs without supplied calculations.
Answers to common questions about the production assumptions, operating forecast, and financial reports.
Yes. Change the monthly saleable pouch capacity and annual utilization assumptions; the monthly revenue calculations allocate total production among the five flavors.
No. The documented case uses available production capacity, utilization, seasonal multipliers, and flavor mix rather than a separate competing demand forecast.
Each flavor has annual wholesale prices and a share of the same production pool; the model sums monthly pouch volume multiplied by the corresponding flavor price.
No. Fixed base salaries for the seven annual-average FTE are calculated through Payroll and excluded from direct, variable, and fixed expense categories in this example.
No. It is estimated initial owner funding. The example does not assume committed outside borrowing, though separate debt controls support financing scenarios.
No. EBITDA excludes investing, financing, and working-capital cash movements. Review Cash Flow and Sources & Uses to evaluate liquidity and funding requirements.
Yes. The declared Returns report supports sales break-even, cash break-even, investment payback, and annual ROIC; none of their specific results is assumed in this description.
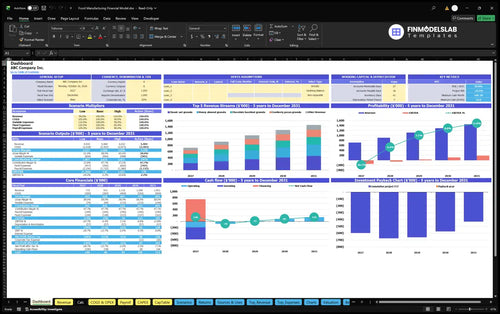
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
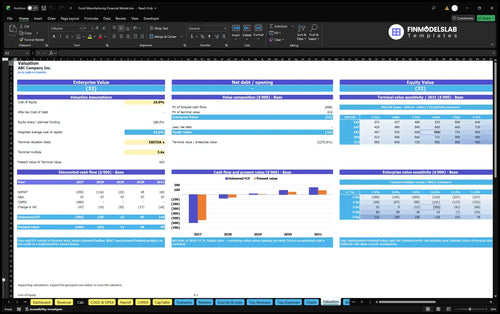
DCF valuation and sensitivity analysis.
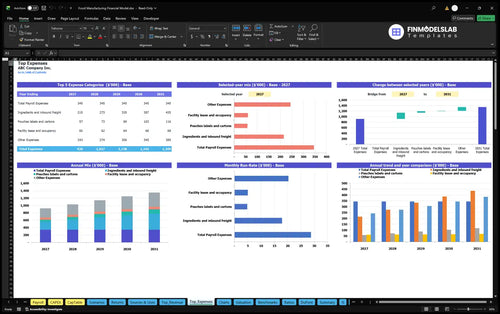
Largest costs and spending trends.
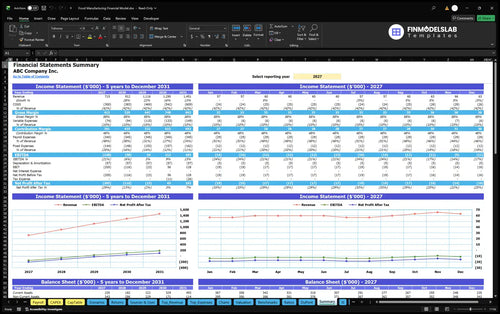
Annual and monthly financial performance.
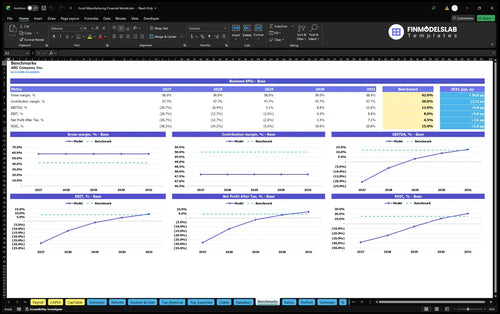
Compare margins and returns to benchmarks.

I was nervous about the Excel side of this, but the layout made advanced food manufacturing modeling feel manageable. It saved me about 6 hours of setup and let me focus on the business case instead of the spreadsheet mechanics.

One broken cell used to make me doubt the whole model, and this template gave me a cleaner way to work. I caught issues faster and finished a lender call with the numbers already checked.
Building low, base, and high cases by hand was dragging on for days, but this template organized it well. I got all three scenarios ready in one afternoon and had a clearer plan for my meeting.