

Revenue & Calc
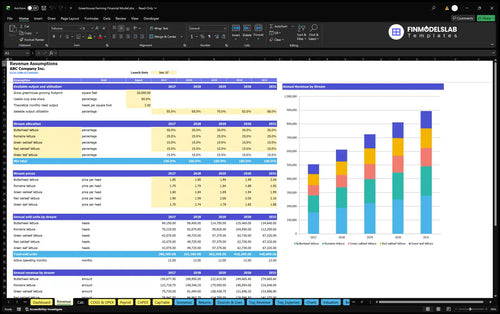
Change footprint, usable area, head output, utilization, variety shares, and prices; monthly calculations translate those inputs into sold heads and revenue.


The Greenhouse Farming Financial Model is an Excel template for planning a heated deep water culture greenhouse in Missouri. It connects growing capacity, saleable lettuce output, wholesale prices, operating costs, and staffing to financial projections.
The illustrative case uses a 20,000-square-foot greenhouse on leased land, selling five whole-head lettuce varieties to local grocers and foodservice buyers. The forecast covers 2026–2030 from a January 31, 2026 launch, in nominal US dollars excluding sales tax.
The workbook connects editable greenhouse assumptions to monthly calculations, scenario comparisons, and financial reports.
Change footprint, usable area, head output, utilization, variety shares, and prices; monthly calculations translate those inputs into sold heads and revenue.
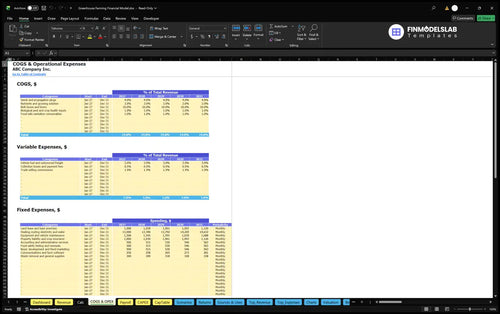
Adjust revenue-linked costs, monthly overhead, annual-average FTE, and salaries to evaluate the expense structure supporting greenhouse production and delivery.
Compare Low, Base, and High multipliers for revenue, COGS, variable expenses, fixed expenses, and payroll; the selected scenario feeds management reporting.
Review income, cash movement, assets, liabilities, and equity through the financial statements and combined summary after completing the relevant assumptions.
The revenue forecast allocates saleable heads across five mutually exclusive varieties, then multiplies each allocation by its wholesale price.
Gross area multiplied by the 85% usable share provides 17,000 square feet of crop area. At 2.5 theoretical heads per net square foot monthly, capacity is 42,500 heads before applying saleable utilization.
Utilization rises from 55% in 2026 to 88% in 2030 and already incorporates crop losses and unsold output. Continuous staggered production has no seasonal output multiplier.
| Variety | Share | 2026 price | 2030 price |
|---|---|---|---|
| Butterhead | 30% | $1.85 | $2.04 |
| Romaine | 25% | $1.75 | $1.93 |
| Green oakleaf | 15% | $1.80 | $1.99 |
| Red oakleaf | 15% | $1.90 | $2.10 |
| Green leaf | 15% | $1.70 | $1.88 |
Green leaf receives the residual share after the four selected shares; each sold head is allocated once.
The Revenue Forecast connects operating drivers, sold volume, prices, and sales by variety. Use it to examine whether higher utilization or a different variety mix supports the revenue plan.
23,375 sold heads/month × $1.8025 weighted price/head × 12 months ≈ $505,601 annual revenue.
The launch rule activates months whose period-end date falls on or after January 31, 2026, so January is included. Annual input selections determine each forecast year’s utilization and prices.
Operating expenses combine revenue-linked COGS and variable costs with fixed monthly overhead and separately calculated payroll.
Estimated COGS total 19% of revenue: seeds and plugs 4%, nutrients 3%, boxes and liners 10%, crop health inputs 1%, and sanitation supplies 1%. Variable expenses total 5%: freight and fuel 3%, collection losses and payment fees 0.5%, and selling commissions 1.5%.
Fixed overhead covers premises, heating, cooling, electricity, water, maintenance, insurance, administration, testing, marketing, software, and supplies. The 2026 land lease input is $1,000 monthly for 12 paid months; total fixed expenses are $222,600 that year.
The COGS and Operating Expenses forecast organizes direct, variable, and fixed costs by assumption and timing. It helps assess how additional sales contribute toward covering the greenhouse’s fixed overhead.
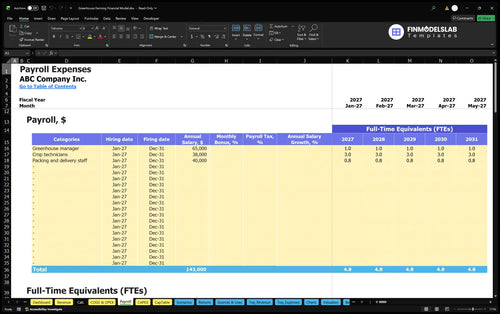
| Role | Average FTE | Annual base/FTE |
|---|---|---|
| Greenhouse manager | 1 | $65,000 |
| Crop technicians | 3 | $38,000 |
| Packing and delivery | 0.75 | $40,000 |
FTE measures staffing capacity, not necessarily the number of individual employees.
The Payroll Forecast calculates personnel costs from role-level staffing and compensation. The selected 4.75 FTE produce $209,000 of annual base payroll throughout this case, counted separately from COGS and other operating expenses.
Employer taxes, benefits, and personal taxes are excluded from the supplied case. Review these exclusions before adapting the staffing plan to your operation.
Estimated initial owner funding is $1,052,667, covering assets, other preforecast cash, opening working capital, and a three-month reserve.
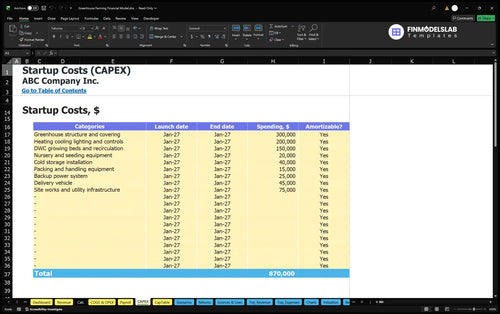
The Capital Expenditure Plan schedules asset spending and depreciation. The $870,000 startup asset budget includes the greenhouse structure, environmental controls, DWC beds, nursery equipment, cold storage, handling equipment, backup power, a vehicle, and site infrastructure.
| Funding use | Amount |
|---|---|
| Startup assets | $870,000 |
| Other preforecast cash | $29,000 |
| Opening net working capital | $15,431 |
| Three-month reserve | $138,236 |
| Initial owner funding | $1,052,667 |
Whole-dollar presentation; component rounding may cause small differences.
Sources and Uses of Funds reconciles funding sources with cash allocation over a selected period. Use it to review the planned owner contribution alongside investment and operating payments; this case has no committed external funding.
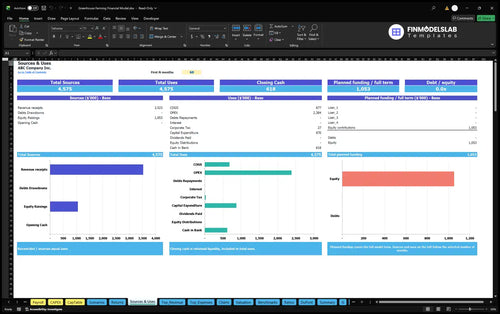
Working-capital controls assume 10 receivable days, 15 payable days, and 21 inventory days. These timing inputs affect liquidity planning; the opening working-capital allocation and reserve do not establish tested cash sufficiency.
Other preforecast cash includes refundable deposits, training and testing, launch samples and marketing, and paid crop commissioning labor. These opening items are separate from annual operating expenses.
The supplied operating forecast ends at EBITDA and illustrates how increasing saleable utilization and prices affect operating earnings.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $505,601 | $552,944 | -$47,343 |
| 2027 | $612,281 | $585,225 | $27,055 |
| 2028 | $724,455 | $619,025 | $105,430 |
| 2029 | $811,308 | $646,955 | $164,353 |
| 2030 | $893,112 | $673,885 | $219,227 |
Source results are independently rounded to whole dollars; displayed revenue less expenses can differ slightly from displayed EBITDA.
Annual EBITDA becomes positive in 2027 and reaches $219,227 in 2030. This is an illustrative operating result, not evidence of net profit, investment recovery, or cash break-even.
The case uses estimated planning inputs, not observed greenhouse performance or verified industry averages. Supporting references do not independently validate the selected assumptions.
The Cash Flow Forecast tracks operating, investing, and financing cash movements with an opening-to-closing cash reconciliation. Review collection timing, inventory, supplier payments, asset purchases, and financing before drawing conclusions about liquidity.
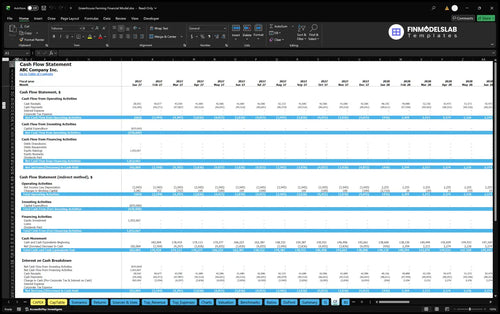
The Returns report separates sales break-even, cash break-even timing, investment payback, and annual return on invested capital.
The Returns analysis compares revenue with break-even requirements and tracks project cash flow, cumulative free cash flow, invested capital, and ROIC. Use these measures to evaluate operating coverage and investment recovery separately.
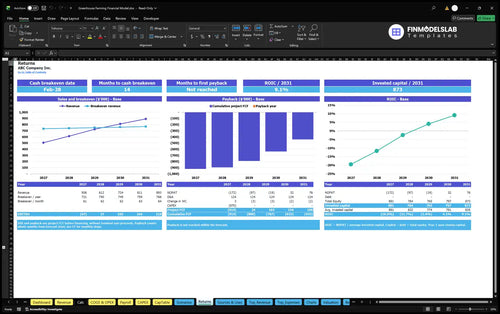
Sales break-even concerns revenue needed to cover operating costs; cash break-even concerns cash flow timing. Investment payback tracks recovery of invested cash, while annual ROIC assesses the return generated on invested capital.
Dashboard Debt Controls feed financing schedules for facility amounts, dates, interest rates, and repayment structures. Enter an actual financing proposal to evaluate debt payments; the supplied EBITDA figures establish no borrowing terms or payback date.
This template fits an owner-operated DWC greenhouse selling whole heads through a shared production area.
Use it to test utilization targets, wholesale prices, variety allocation, staffing, and overhead before committing capital. Operations with different crops, production cycles, or sales units should review the revenue mechanics before reusing this structure.
These answers clarify the case assumptions, editable drivers, and limits of the illustrated results.
Yes, edit gross footprint, usable share, monthly heads per net square foot, saleable utilization, variety shares, and wholesale prices to build a different operating case.
No, all five varieties share the same crop area, with four selected shares and one residual share allocating each saleable head once.
No, the saleable utilization assumption already includes crop losses and unsold output, so another deduction would count those losses twice.
No, EBITDA excludes depreciation, interest, and taxes and does not capture working-capital timing, asset purchases, or financing flows; review the cash flow statement separately.
No, the forecast uses estimated case assumptions and illustrates model calculations; it does not establish industry averages, guaranteed earnings, or a tested investment payback.
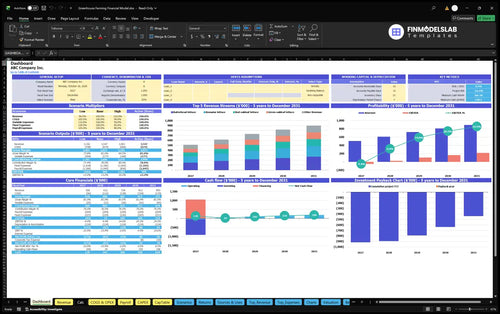
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
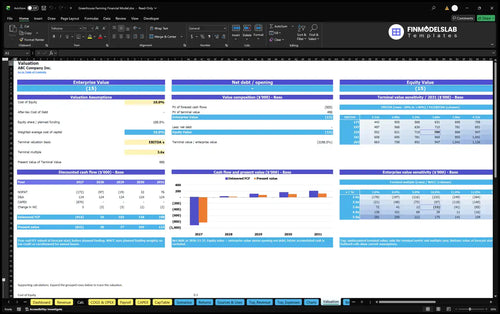
DCF valuation and sensitivity analysis.
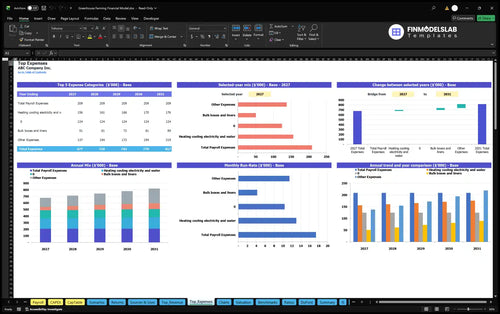
Largest costs and spending trends.
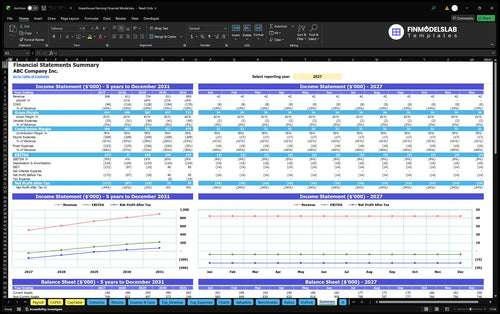
Annual and monthly financial performance.
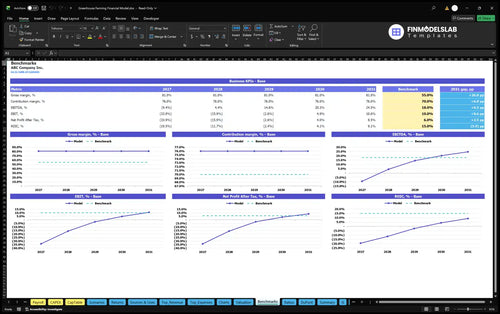
Compare margins and returns to benchmarks.

I opened the greenhouse farming model and finally had a place to start instead of a blank sheet. It cut my setup time by hours and gave me a working draft I could actually build on.
The assumption tabs kept pricing, labor, and operating costs in one place, so I could stop chasing numbers across different files. I had a cleaner forecast ready for our lender meeting the same day.
I liked having a template with the formulas already in place, because one broken cell used to throw off my whole model. This saved me from a late-night rebuild and made the numbers easier to trust.