

Revenue & Calc
Revenue inputs define service capacity, utilization, monthly seasonality, recipe mix, and net cup prices. Calc applies launch timing and builds the detailed monthly volume and revenue forecast.


This Lemonade Stand Financial Model is an Excel template for an owner-operated temporary booth in Dayton, Ohio. It converts service days, service hours, cups per hour, utilization, seasonality, recipe mix, and net cup prices into monthly and annual financial projections.
The illustrated case covers 2026 through 2030 and models five mutually exclusive 24-ounce lemonade recipes. It includes winter closure through seasonality, fixed owner compensation, direct and variable costs, recurring operating expenses, startup assets, working-capital inputs, and opening owner funding.
The workbook connects lemonade operating assumptions to monthly calculations, financial statements, funding schedules, and management reports.
Revenue inputs define service capacity, utilization, monthly seasonality, recipe mix, and net cup prices. Calc applies launch timing and builds the detailed monthly volume and revenue forecast.
COGS & OPEX separates direct, variable, and fixed operating costs, while Payroll models the working owner operator as 0.4 annual-average FTE with fixed annual base compensation.
CAPEX records startup equipment and depreciation treatment, CapTable records owner contributions, and Sources & Uses explains how funding is allocated across operating, investing, and financing needs.
The model includes projected financial statements, Scenarios, Returns, Valuation, ratios, charts, benchmark comparisons, top revenue and expense analysis, plus model reconciliations and input checks.
Revenue is capacity-driven: monthly cups equal service days × hours × cups per hour × utilization × seasonality, then cups are allocated once across the five recipes.
The base operating pool starts with 8 nominal service days per month, 6 hours per day, and 35 available cups per hour. Utilization rises from 30% in 2026 to 48% in 2030, while the monthly seasonality profile closes January, February, and December and concentrates volume in warmer months.
Each month’s available cup volume is allocated once by recipe: 40% Classic, 20% Strawberry, 15% Mango, 15% Mint, and 10% Sugar-free. Net prices are $5 for Classic and Sugar-free and $6 for the three flavored recipes.
The Revenue Forecast shows the lemonade stand’s operating drivers, recipe mix, cup prices, volume assumptions, and resulting revenue. It lets users edit service capacity, utilization, seasonality, and mix before those assumptions flow into monthly calculations.

1,680 nominal cups/month × 30% utilization × 12.0 annual seasonality sum × $5.50 weighted net price = $33,264 annual revenue.
Operating expenses are modeled separately as direct COGS, revenue-linked variable expenses, fixed monthly costs, and Payroll so each payment component is counted once.
COGS equals 24% of revenue: 16% for lemons, sweeteners, and flavoring; 5.5% for cups, lids, straws, and napkins; and 2.5% for ice, water, and sanitation supplies. Variable expenses add 3.2% card processing and 1% sales-linked promotions.
Fixed costs cover site and market fees, preparation and storage access, insurance, transport, recurring permits and inspections, bookkeeping, equipment maintenance, communications, and POS access. The example fixed-cost total is $7,080 per year.
The COGS & Operating Expense Forecast separates direct costs, revenue-linked operating expenses, and fixed recurring costs. This helps show how ingredient, packaging, payment-processing, market-fee, transport, and administrative assumptions affect margins as sales volume changes.

Payroll is separate from COGS, variable expenses, and fixed costs. The case includes one working owner operator at 0.4 annual-average FTE and $40,000 fixed annual base pay per FTE, producing $16,000 of annual Payroll in each forecast year.
The Payroll Forecast shows staffing FTE, compensation assumptions, and monthly personnel expense calculations. For this lemonade stand, it keeps the owner’s fixed base compensation distinct from ingredient, operating, and market-related costs.

Startup equipment, preopening cash items, opening inventory, and reserve funding are modeled separately from annual operating expenses and EBITDA.
Named startup assets include a $600 canopy, counter and tables package, a $200 commercial manual citrus press, $450 of coolers and beverage dispensers, and a $180 portable handwash station. Other startup assets include a POS reader, dedicated tablet, durable menu signs, and utensils.
The illustrated owner funding is $10,866, based on $2,000 of assets, $550 of setup costs, $200.95 of opening stock, and an $8,115 reserve. The case uses no outside financing.
The Capital Expenditure Plan records startup equipment purchases and whether each item is depreciable. It separates investment spending from recurring operating expenses so equipment timing and depreciation can feed the broader financial statements.

The Sources and Uses of Funds report reconciles owner funding with planned uses such as startup assets, opening stock, setup costs, operating payments, and retained cash. It helps distinguish financing sources from operating income and from the EBITDA forecast.

The illustrated base case grows revenue through higher utilization while fixed annual Payroll and fixed operating costs remain unchanged in the supplied assumptions.
| Year | Revenue | Expenses | EBITDA |
|---|---|---|---|
| 2026 | $33,264 | $32,460 | $804 |
| 2027 | $38,808 | $34,024 | $4,784 |
| 2028 | $44,352 | $35,587 | $8,765 |
| 2029 | $49,896 | $37,151 | $12,745 |
| 2030 | $53,222 | $38,089 | $15,134 |
Amounts are illustrative projections rounded to whole dollars; operating expenses include COGS, variable expenses, fixed expenses, and Payroll.
Revenue increases from $33,264 in 2026 to $53,222 in 2030 as utilization rises from 30% to 48%. Because the supplied fixed-cost and owner-pay assumptions stay level, EBITDA expands from about $804 to $15,134 in the illustrated case.
These EBITDA figures are operating projections, not net profit or cash sufficiency tests. Depreciation, financing, taxes, working-capital movements, investment spending, and funding flows are evaluated in the model’s other statements and schedules.
The Cash Flow Forecast shows operating, investing, and financing cash movements with an opening-to-closing cash reconciliation. It is the appropriate report for reviewing liquidity and funding needs rather than treating EBITDA as cash.

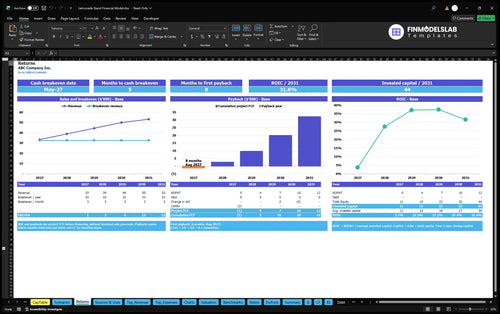
The Returns report separates sales break-even, cash break-even timing, investment payback, and annual ROIC so users can evaluate different questions without treating them as the same metric.
Sales break-even compares revenue with the level needed to cover modeled costs. Cash break-even and investment payback use cash-flow timing, while annual ROIC compares operating returns with invested capital; the supplied case does not provide a documented payback month or ROIC result to quote.
Dashboard Scenario Controls also allow Low, Base, and High multipliers for revenue, COGS, variable operating expenses, fixed operating expenses, and Payroll. This supports structured sensitivity testing without changing the underlying operating model.
The Return on Invested Capital Analysis combines sales break-even, cash break-even timing, investment payback, and annual ROIC. It helps users assess operating coverage, recovery of invested cash, and capital efficiency using the model’s projected financial flows.
For a temporary lemonade booth, these reports can be used to test whether revised prices, stronger or weaker event utilization, different seasonal demand, higher ingredient costs, or changes in owner compensation materially change financial performance.
The Financial Scenario Analysis compares Low, Base, and High cases for revenue, margins, and EBITDA. It provides a consistent way to test upside and downside assumptions across the forecast while keeping each scenario’s operating logic visible.

The model is designed for a small temporary lemonade operation with one booth, limited service days, seasonal demand, and owner-operated staffing rather than a permanent storefront or mobile truck.
It fits planning for community markets and neighborhood pop-ups where sales are constrained by service hours and cup throughput. Users can adapt the inputs for their own service schedule, prices, recipe mix, utilization, operating costs, staffing, startup investment, and funding structure.
The documented scope excludes a permanent storefront, food truck, alcohol, bottled wholesale, donations, and catering deposits. Sales tax is excluded from net prices and revenue, and the operating forecast is described through EBITDA.
These answers summarize the model’s editable assumptions, calculations, and supported reports.
Yes. The Revenue inputs let you edit net cup prices and the percentage mix assigned to each of the five lemonade recipes.
The model multiplies service days, hours per day, cups per hour, utilization, and the monthly seasonality factor, then allocates cups once across recipes.
Yes. The illustrated case models the working owner operator at 0.4 annual-average FTE with fixed annual base compensation through Payroll.
No. Startup assets, preopening cash items, opening stock, and owner funding are kept separate from recurring operating expenses and EBITDA.
Yes. The declared workbook reports include projected Cash Flow and Balance Sheet statements, plus a combined Summary and supporting funding schedules.
Yes. Dashboard Scenario Controls provide Low, Base, and High multipliers for revenue, COGS, variable expenses, fixed expenses, and Payroll.
Yes. The Returns report covers sales break-even, cash break-even timing, investment payback, and annual ROIC without assuming undocumented case results.

KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.

DCF valuation and sensitivity analysis.

Largest costs and spending trends.

Annual and monthly financial performance.
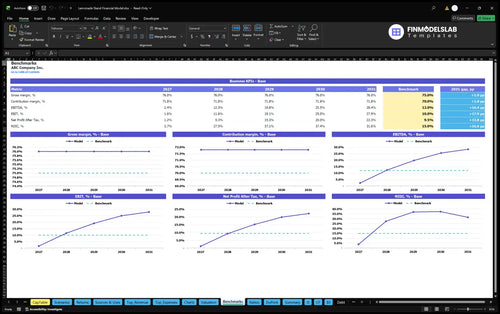
Compare margins and returns to benchmarks.

I stopped worrying that one broken formula would throw off the whole file. The checks made it easy to catch mistakes fast, and I saved about 3 hours of cleanup before sharing it.

I wasn’t sure what investors expected, but this template gave me the right outputs and order. I had a cleaner draft ready the same day, and it made my meeting prep much easier.
I’m not great with advanced Excel, so I liked that the model stayed simple to follow. I filled in the inputs without feeling lost, and it cut my planning time by nearly half.