

Operations & Revenue
Revenue and Calc convert launch timing, preparation capacity, utilization, grade mix, and realized metal prices into monthly saleable tons and sales by grade.


This Metal Recycling Financial Model is an Excel template for a leased U.S. industrial scrap collection and preparation yard. It forecasts five saleable metal grades from one shared processing-capacity pool, then links the resulting revenue to direct costs, operating expenses, payroll, working capital, capital spending, financing controls, and financial reports.
The illustrated case covers 2026 through 2030 for a secondary Midwest market and ends its documented operating forecast at EBITDA. All figures are planning assumptions or illustrative projections, not observed results, industry averages, or guarantees.
The workbook connects metal-yard operating assumptions to monthly calculations, financial statements, financing schedules, valuation, returns, and management reporting.
Revenue and Calc convert launch timing, preparation capacity, utilization, grade mix, and realized metal prices into monthly saleable tons and sales by grade.
COGS & OPEX and Payroll separate scrap purchases, hauling, processing consumables, variable operating charges, fixed yard costs, and role-based salaries so each payment component is counted once.
CAPEX, CapTable, Debt, Sources & Uses, and Cash Flow connect startup assets, owner funding, working capital, financing structures, investing cash flows, and liquidity reporting.
Dashboard, IS, BS, CF, Summary, Scenarios, Returns, Valuation, Ratios, DuPont, Benchmarks, Top_Revenue, Top_Expenses, Charts, and Checks support review of profitability, cash generation, financial position, break-even, payback, return measures, and model integrity.
Revenue comes from one shared saleable-ton capacity pool allocated across five prepared metal grades, with each grade priced at its own realized dollars per short ton.
Monthly capacity is based on 3 saleable short tons per preparation hour, 8 scheduled hours per day, and 22 operating days per month. Annual utilization increases from 50% in 2026 to 85% in 2030, while all streams begin in the selected launch month.
The capacity pool is allocated once among prepared ferrous scrap, sorted aluminum, graded copper, sorted brass, and sorted stainless. Revenue equals saleable tons multiplied by each grade share and realized price, preventing the same processing capacity from being duplicated across revenue streams.
The Revenue Forecast shows the operating inputs, grade allocation, saleable volume, realized price assumptions, and resulting revenue by metal stream. It lets the buyer test capacity utilization or pricing changes without changing the underlying revenue logic.
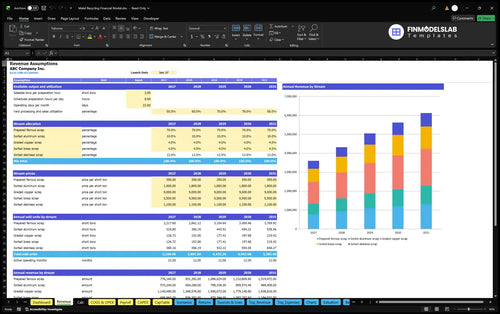
3 short tons/hour × 8 hours/day × 22 days/month × utilization = monthly saleable tons; grade tons × realized price/ton = grade revenue.
The selected planning prices are $350 per short ton for prepared ferrous, $1,800 for aluminum, $9,000 for copper, $5,500 for brass, and $1,100 for stainless. The documented mix includes 70% ferrous, 10% aluminum, 4% copper, and 4% brass, with the remaining allocation assigned to stainless in the model.
The model separates direct material and processing costs, variable operating charges, fixed yard expenses, and payroll before calculating EBITDA.
The COGS & Operating Expense Forecast shows direct costs, variable expenses, fixed operating costs, timing, and monthly calculations that feed the income statement. For this case, scrap purchases are the dominant direct cost and are modeled as a percentage of revenue.
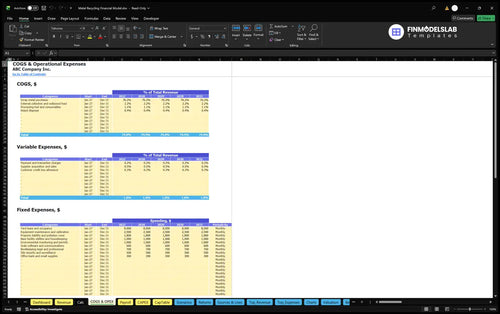
COGS assumptions include scrap metal purchases at 76.18% of revenue, external collection and outbound haul at 2.2%, processing fuel and consumables at 1.06%, and reject disposal at 0.44%. Variable operating assumptions add transaction charges, supplier acquisition and sales, and customer credit-loss allowance.
Fixed coverage includes the yard lease, equipment maintenance and calibration, insurance, utilities, environmental monitoring and permits, scale software, professional services, security, and office costs. The example yard lease is $8,000 per month for 12 paid months.
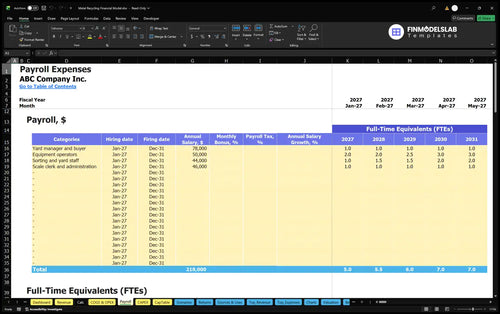
The Payroll Forecast shows staffing FTE and annual base salary assumptions by role, then converts those inputs into monthly personnel expense. The case includes a yard manager and buyer, equipment operators, sorting and yard staff, and a scale clerk and administrator.
The workbook treats opening assets, preopening cash items, working capital, and owner funding separately from annual operating expenses and EBITDA.
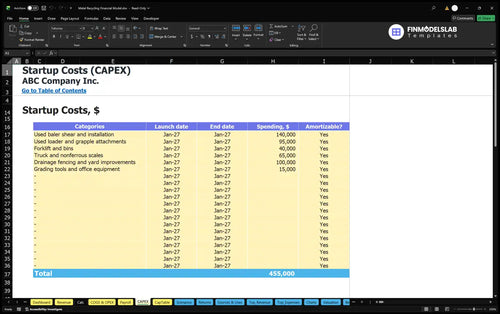
Startup assets include a used baler/shear and installation, used loader with grapple attachments, forklift and bins, truck and nonferrous scales, plus yard improvements and other equipment. The documented asset total is $455,000, with another $45,000 of separate startup cash items.
Working-capital controls use 15 accounts-receivable days, 0 accounts-payable days, and 20 inventory days. Initial owner funding is $1,650,408, based on startup assets, other opening cash, opening working capital of $305,909, and a three-month reserve of $844,499.
The Capital Expenditure Plan shows planned asset purchases, spending dates, depreciation treatment, and the monthly investment schedule. It separates startup and later capital spending from operating costs so equipment investment is not mistaken for EBITDA expense.
The funding plan assumes no uncommitted outside funding or extra buffer beyond the documented owner contribution. Debt controls are available on the Dashboard for alternative financing structures, but no debt amount or borrowing result should be inferred unless entered by the user.
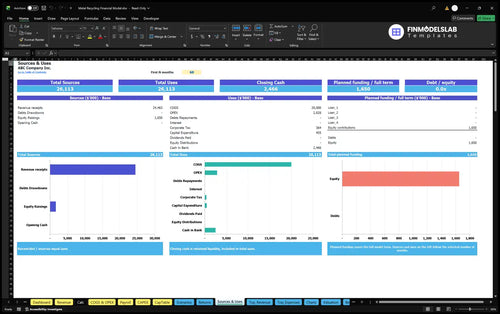
The Sources and Uses of Funds report reconciles funding sources with operating, investment, financing, and retained-cash uses over a selected period. It helps review how equity or debt funding supports startup assets, working capital, and business cash needs.
The documented case grows revenue with higher utilization and shows EBITDA after direct costs, operating expenses, and payroll, while leaving cash and financing analysis to the dedicated reports.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $3,602,016 | $3,377,998 | $224,018 |
| 2027 | $4,322,419 | $3,982,637 | $339,782 |
| 2028 | $5,042,822 | $4,590,277 | $452,546 |
| 2029 | $5,619,145 | $5,103,389 | $515,756 |
| 2030 | $6,123,427 | $5,511,236 | $612,191 |
Illustrative planning case; amounts are rounded to whole dollars and are not observed historical results.
Revenue increases from $3,602,016 in 2026 to $6,123,427 in 2030 as yard processing and sales utilization rises. EBITDA increases from $224,018 to $612,191 over the same period, reflecting the model’s documented revenue mix, cost percentages, fixed expenses, and staffing plan.
These EBITDA figures do not establish net profit or cash sufficiency. Depreciation, interest, tax, working-capital movements, capital expenditures, debt service, and equity financing are handled in the broader financial statements and schedules.
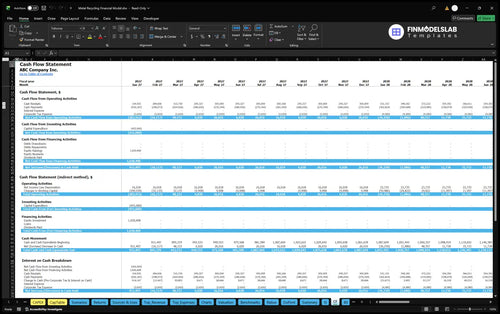
The Cash Flow Forecast shows monthly operating, investing, and financing cash movements with an opening-to-closing cash reconciliation. It is the report to review liquidity, funding requirements, capital spending, debt activity, and cash generation rather than treating EBITDA as cash.
The workbook includes separate tools for operating break-even, cash break-even, investment payback, annual ROIC, scenarios, and valuation without implying any return result that is not supported by the case inputs.
The Return on Invested Capital Analysis combines sales break-even, cash break-even timing, project and cumulative free cash flow, investment payback, invested capital, and annual ROIC. These measures answer different questions and should not be substituted for one another.
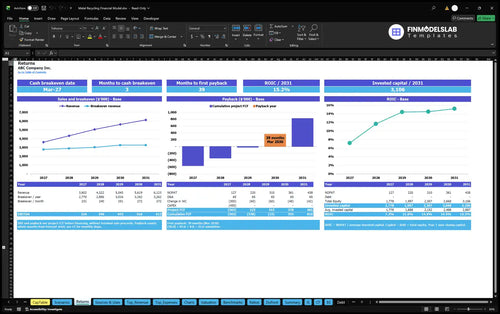
Sales break-even compares revenue with the level required to cover modeled operating costs. Cash break-even considers cash timing, while investment payback tracks recovery of invested cash and ROIC measures annual operating return relative to invested capital.
No payback month, ROIC percentage, or IRR is stated here because the documented metal-recycling case does not provide those calculated results.
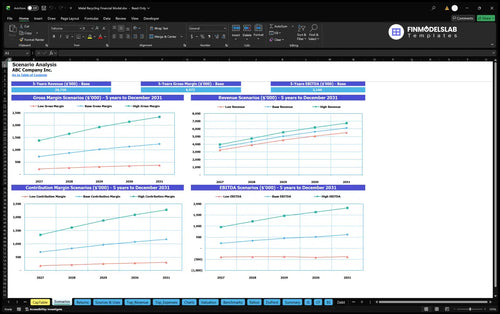
The Financial Scenario Analysis compares Low, Base, and High cases using configurable multipliers for revenue, COGS, variable operating expenses, fixed operating expenses, and payroll. It helps test how operating assumptions change revenue, margins, and EBITDA across the forecast.
Valuation and sensitivity analysis are also included as workbook functions, using discounted unlevered free cash flow and terminal assumptions. Those reports are useful for testing valuation inputs, but this description does not invent a value, discount rate, terminal multiple, or equity return.
These answers clarify what the Metal Recycling Financial Model covers and how the documented case should be interpreted.
Revenue is driven by one shared saleable-ton capacity pool, utilization, grade allocation, and realized price per short ton for five prepared metal categories.
Yes. The Revenue inputs are designed for editable operating assumptions, including utilization, grade mix, realized prices, launch timing, and related monthly calculations.
Yes. Role-based salaries are modeled through Payroll and excluded from COGS, variable expenses, and fixed expenses to avoid double counting.
Yes. The workbook includes projected IS, CF, and BS reports, while the documented operating case presented here is specifically described through EBITDA.
No. EBITDA excludes working-capital changes, capital spending, financing flows, interest, taxes, and other cash movements that are reviewed in the Cash Flow report.
Yes. Dashboard Debt Controls support up to four facilities with amount, timing, term, interest-only period, interest rate, and repayment structure, feeding the Debt schedules.
No. They are model-based planning projections using documented assumptions for a secondary Midwest U.S. yard and should not be treated as historical or benchmark results.
The case excludes smelting, shredding, auto dismantling, e-waste processing, and hazardous battery processing; it focuses on clean industrial scrap collection and preparation.
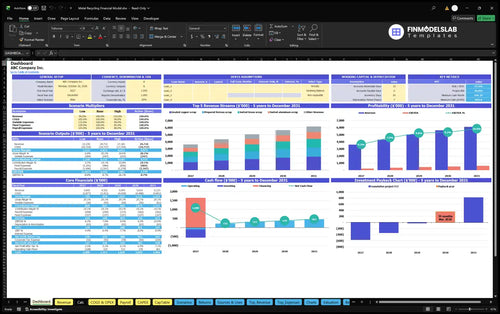
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
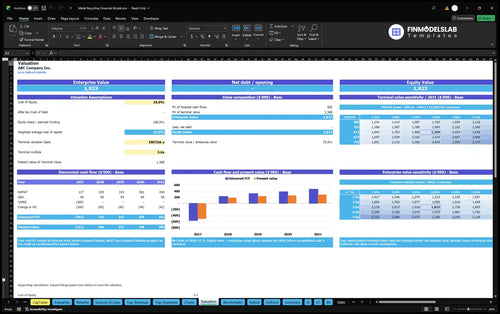
DCF valuation and sensitivity analysis.
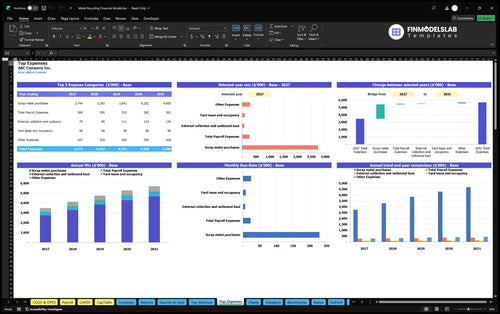
Largest costs and spending trends.
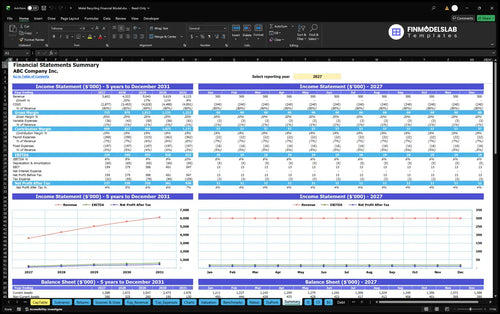
Annual and monthly financial performance.
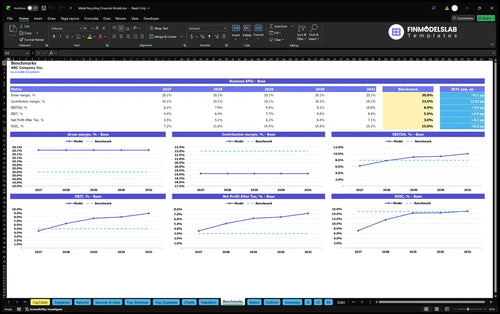
Compare margins and returns to benchmarks.

This template pulled pricing, costs, and growth into one clean view, so I could stop juggling scattered inputs. It made our first forecast easier to explain and saved me a full afternoon.
I’m not strong in Excel, and this model kept the hard parts out of the way. I got a working 5-year forecast without calling in a consultant, which meant our planning meeting happened two days sooner.

Building the financials by hand was eating up my week, but this template got me to a usable model in under a day. It saved at least 12 hours and let me focus on the business instead of formulas.