

Revenue & Calc
Edit bays, hours, utilization, seasonality, service shares, and hourly prices; Calc allocates shared hours among five appointment types.


The Photography Studio Financial Model is an Excel template for a two-bay appointment studio. It converts shooting hours, utilization, service mix, and hourly prices into monthly revenue and a 2026–2030 operating forecast.
The example is a 1,200-square-foot suburban Dallas studio with two salaried photographers and a part-time coordinator. Its revenue, costs, and EBITDA are planning estimates, not observed results.
Linked operating schedules, financial statements, and management reports turn studio assumptions into a reviewable forecast.
Edit bays, hours, utilization, seasonality, service shares, and hourly prices; Calc allocates shared hours among five appointment types.
Edit direct and variable costs, fixed overhead, salaries, and coordinator staffing; the schedules feed monthly results.
Schedule equipment and owner contributions; optional debt controls support other financing structures without assuming borrowing.
Review income, cash flow, and financial position; the example supplies results through EBITDA, not net profit or closing cash.
Compare Low, Base, and High revenue and expense assumptions and their EBITDA effects.
Examine break-even, payback, ROIC, valuation, revenue and cost composition, and model checks.
Revenue comes from one finite pool of bookable studio hours, allocated among five mutually exclusive photography services.
Two bays, six bookable hours per bay daily, and 22 operating days provide 264 available shooting hours monthly. Sold hours equal capacity multiplied by utilization and monthly seasonality, with no separate service-level demand assumption.
Sold hours go to headshots (25% at $225/hour), family portraits (25% at $300), maternity portraits (15% at $300), product photography (20% at $200), and branding (15% at $250). Shares total 100%, preventing double-counted bookings.
264 monthly hours × 30% utilization × 12 seasonality-adjusted months × $253.75 blended hourly rate = $241,164 annual revenue.
The Revenue Forecast shows the capacity, utilization, service allocation, and prices driving each photography revenue stream. Changing a service share or rate updates the monthly calculations without adding another pool of bookable hours.
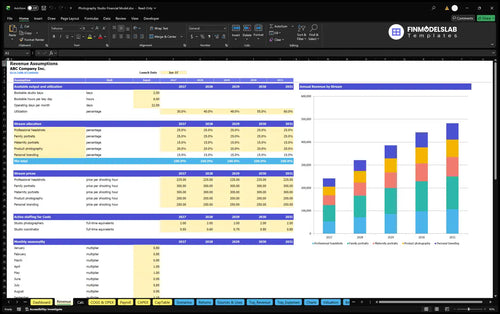
Utilization grows from 30% in 2026 to 60% in 2030. Seasonality favors September–November over January, February, and July; its monthly multipliers sum to 12 annually.
The model launches January 31, 2026, counting January as a full month and setting prelaunch revenue to zero. Adjust timing for your studio.
The operating forecast separates revenue-linked direct costs, variable operating costs, fixed overhead, and salaried staffing.
The COGS and Operating Expenses forecast applies 2.5% for shoot consumables and props, 4% for specialty retouching, and separate variable rates for processing, advertising, and client delivery. Fixed studio overhead is budgeted independently of sales volume.
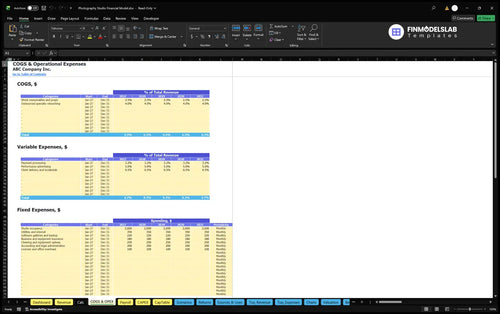
Direct costs equal 6.5% of revenue; variable operating costs equal 8.7%: processing 3.2%, advertising 5%, and delivery 0.5%. Changes in booked hours therefore affect operating contribution.
Fixed overhead totals $46,800 annually across occupancy, utilities, backup, insurance, upkeep, administration, and licenses. Occupancy is $2,600 monthly, or $31,200 over 12 paid months.
The Payroll Forecast plans two full-time photographers at $52,000 annual base pay each and a coordinator whose annual-average staffing rises from 0.5 to 0.8 FTE. Salary expense is counted in payroll, not duplicated in direct costs.
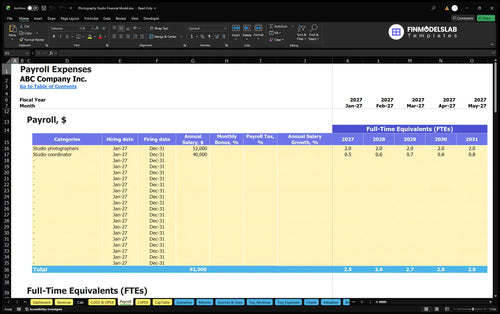
Payroll is $124,000 in 2026 with a 0.5-FTE coordinator and $136,000 in 2030 with 0.8 FTE. Selected cost assumptions exclude employer taxes, benefits, and personal taxes.
Equipment, preopening cash requirements, working capital, and owner equity are modeled separately from recurring operating expenses.
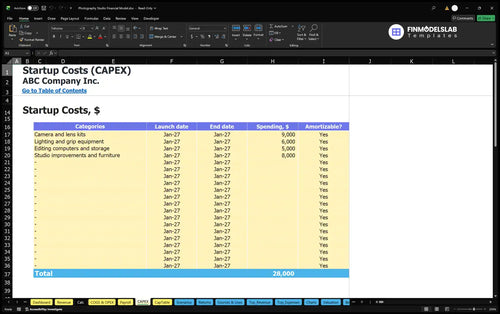
Startup assets comprise $9,000 of camera gear, $6,000 of lighting, $5,000 of editing equipment, and $8,000 of improvements and furniture, totaling $28,000 before launch cash items.
The Capital Expenditure Plan schedules studio equipment and improvement purchases and distinguishes investment spending from the depreciation and asset schedules. Buying cameras or lights is not equivalent to an annual COGS or payroll expense.
Other opening needs include a lease deposit, permits, launch marketing, and preopening cash. Working-capital inputs are six receivable days, zero payable days, and 12 inventory days; they affect cash timing, not EBITDA directly.
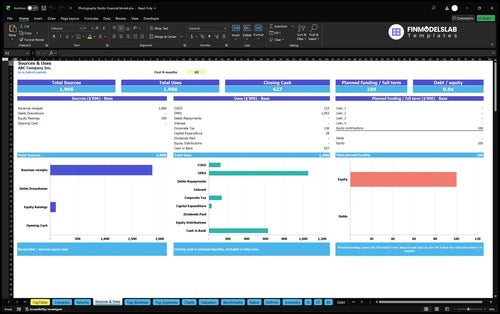
The Sources and Uses of Funds report organizes financing inflows and cash allocations. The sample plans $100,224 of initial owner funding, based on startup assets, launch cash, opening working capital, and three months of first-year operating cash outflows.
Higher utilization increases projected revenue while the model holds its two-photographer base and fixed-cost assumptions as specified.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $241,164 | $207,457 | $33,707 |
| 2027 | $321,552 | $223,676 | $97,876 |
| 2028 | $385,862 | $237,451 | $148,411 |
| 2029 | $442,134 | $250,004 | $192,130 |
| 2030 | $482,328 | $256,114 | $226,214 |
Projected case amounts are rounded to whole dollars; totals may differ slightly due to displayed rounding.
Revenue grows from $241,164 to $482,328 as utilization rises from 30% to 60% between 2026 and 2030. EBITDA rises from $33,707 to $226,214 under the stated assumptions.
EBITDA deducts direct costs, variable costs, fixed overhead, and payroll from revenue. It is not net profit; net earnings, loan payments, valuation, and cash balances are not supplied.
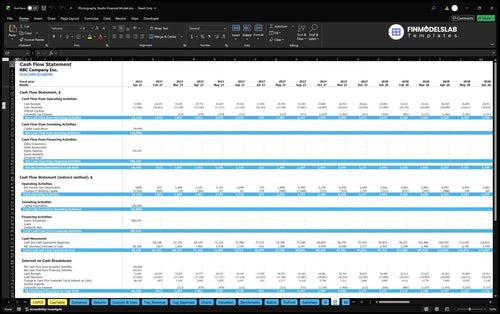
The Cash Flow Forecast tracks operating cash movement alongside capital spending and equity or debt funding flows. It helps assess whether payment timing, equipment purchases, and cash reserves support the studio plan beyond its projected EBITDA.
The Returns and scenario tools help test the operating threshold and investment economics without assuming a favorable outcome.
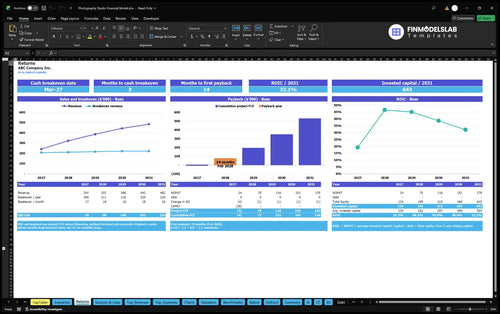
Sales break-even measures required revenue; cash break-even also considers payment timing. Payback follows cumulative project cash flows; annual ROIC compares returns to invested capital. None can be inferred from EBITDA alone.
The Returns analysis compares projected revenue with break-even requirements and traces investment payback and annual ROIC. These calculations become more useful after you adjust the studio cost base, startup spending, and cash-flow assumptions.
Dashboard scenario controls compare Low, Base, and High revenue and expense multipliers, and Valuation provides discounted cash flow and sensitivity analysis. No specific payback date, ROIC percentage, or valuation amount is established by the supplied photography example.
This structure fits founders, existing studio operators, and advisers evaluating an appointment-based photography business.
Test utilization, prices, seasonality, photographer capacity, coordinator staffing, and startup funding. The shared-hour design fits studios where portraits, product work, and branding compete for the same rooms.
These are not Dallas market benchmarks or guaranteed results. Replace estimates with your own bookings, quotes, staffing costs, and payment timing.
Answers to common questions about the editable studio assumptions and projected results.
Yes. Change studio bay count, shooting hours per day, operating days, and utilization to recalculate the shared monthly shooting-hour capacity.
No. Headshots, family, maternity, product, and branding work share one sold-hour pool; their allocation percentages add to 100%.
Yes. Twelve editable monthly seasonality multipliers adjust sold hours, with the supplied pattern strongest in September through November.
Yes. Payroll plans role-level salaries, dates, and annual-average FTE, including the two salaried photographers and part-time coordinator.
No. It is illustrative opening owner funding for startup assets, preopening items, working capital, and operating reserves—not sales, EBITDA, or profit.
Yes. It contains projected Income Statement, Cash Flow, and Balance Sheet reports; the supplied case brief provides numeric operating examples only through EBITDA.
The Returns report calculates investment payback using projected cash flows, but no verified payback date is supplied for this illustrative case.
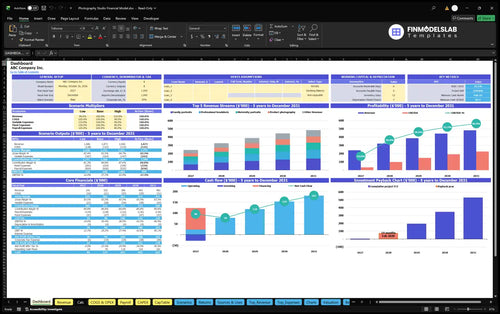
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
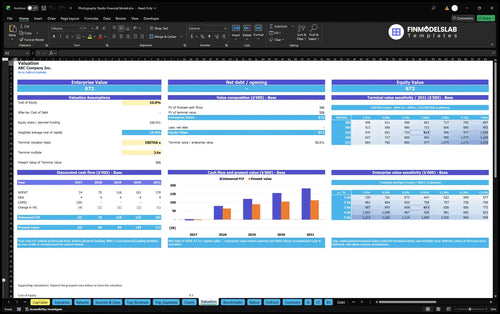
DCF valuation and sensitivity analysis.
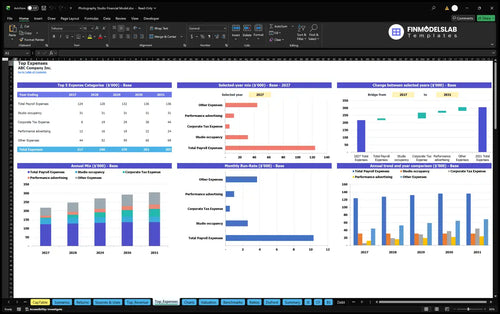
Largest costs and spending trends.
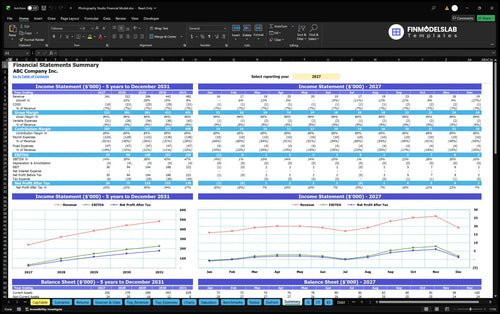
Annual and monthly financial performance.
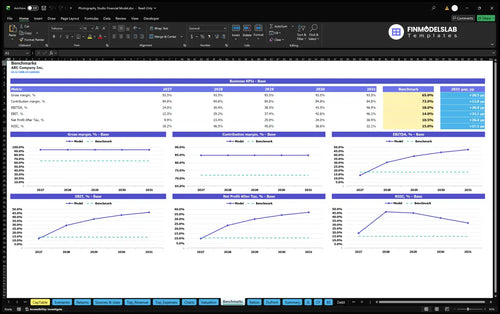
Compare margins and returns to benchmarks.

I stopped hunting through scattered files for charts and statements. Now everything sits in one template, and I could send a cleaner update to our lender the same day.
Building the full model by hand was eating up my evenings. This template cut the setup to one afternoon, so I could spend about 6 hours on pricing and bookings instead.
I could finally see margins and break-even without guessing. That made it much easier to plan our next shoot calendar and explain the numbers in one client meeting.