

Capacity and rentals
Revenue and Calc link table count, hours, utilization, booking formats and prices to monthly sales.


The Pool Hall Financial Model is an Excel template for a 12-table, approximately 5,000-square-foot suburban U.S. billiards hall. It links table-hour capacity, utilization, prices, staffing and operating costs to monthly forecasts for 2026–2030.
The all-ages example sells five exclusive formats of table time: off-peak, peak, league, tournament and private events. Food, alcohol, retail and instruction revenue are excluded.
Connected operating schedules and financial reports help translate a table-rental plan into a five-year business forecast.
Revenue and Calc link table count, hours, utilization, booking formats and prices to monthly sales.
COGS & OPEX tracks supplies, transaction charges and fixed expenses; Payroll models manager and attendant salaries.
CAPEX schedules assets, CapTable records equity, and Dashboard debt controls connect financing to Debt and Sources & Uses.
Income Statement, Cash Flow, Balance Sheet, Scenarios, Returns, Valuation and Checks connect performance, funding and model review.
The forecast sells a utilization-based share of 4,320 available table-hours per month and allocates every paid hour to one booking format.
Available time equals 12 tables × 12 daily hours × 30 operating days per month. Paid utilization rises from 25% in 2026 to 32%, 38%, 43% and 48% in later years.
Of sold table-hours, 30% are off-peak at $12 per hour, 35% peak at $20, 15% league at $14, 10% tournament at $16 and 10% private events at $30. The 100% allocation prevents duplicate revenue.
The Revenue Forecast connects available hours, utilization, format shares and prices to five rental streams. Monthly Calc applies launch timing; external organizer entry fees and prizes are excluded.
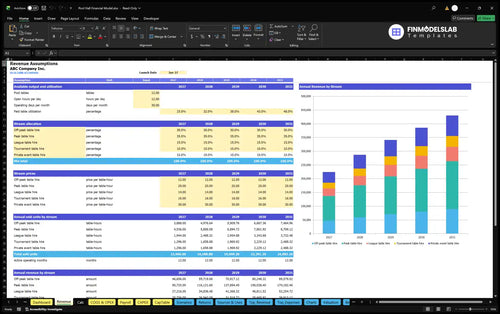
4,320 available table-hours/month × 25% paid utilization × $17.30 blended price per sold table-hour × 12 months = $224,208 in annual revenue.
The $17.30 blended rate weights the five prices by their shares. Annual-average utilization reflects weekly demand variation; no separate monthly seasonality is assumed.
Changes to capacity, rates, mix or utilization update monthly and annual sales, helping compare lower opening-year traffic with a more heavily booked hall.
The model separates direct supplies, revenue-linked selling expenses, recurring fixed costs and role-based payroll so labor is not counted twice.
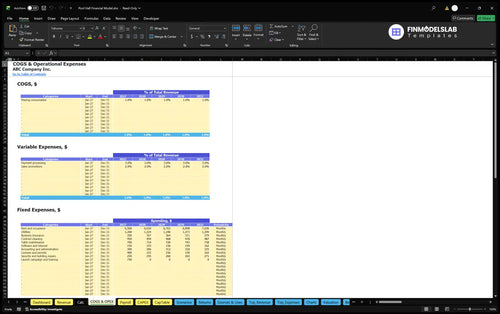
Playing consumables are COGS at 1% of revenue; payment processing is 3% and promotions 2%, both variable expenses.
Fixed costs include occupancy, utilities, insurance, cleaning, maintenance, software, administration, licenses, security, repairs and launch spending. Example monthly rent rises from $6,500 in 2026 to about $7,036 in 2030.
The COGS & Operating Expense Forecast separates consumables, variable charges and fixed payments. Expenses flow to operating results without duplicating Payroll salaries.
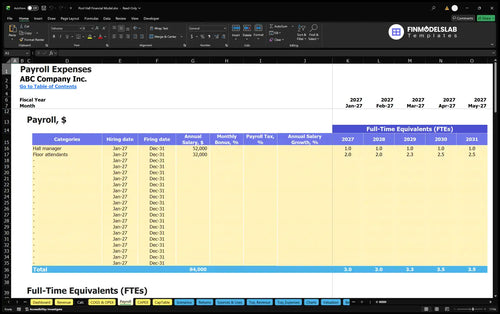
Payroll begins with one $52,000 manager and two attendant FTE at $32,000 per FTE annually. Attendants rise to 2.5 annual-average FTE in 2029–2030.
Payroll rises from $116,000 in 2026 to $132,000 in 2030. Employer taxes, benefits and personal taxes are excluded from this case.
The Payroll Forecast tracks role, FTE, salary and effective dates. It isolates manager and attendant costs from supplies, processing fees and occupancy expenses.
In 2026, COGS are $2,242, variable expenses $11,210, fixed expenses $132,600 and payroll $116,000. Unrounded figures reconcile to operating expenses.
The opening plan separates durable equipment, preopening cash items, stock and a recurring-expense reserve from future operating earnings.
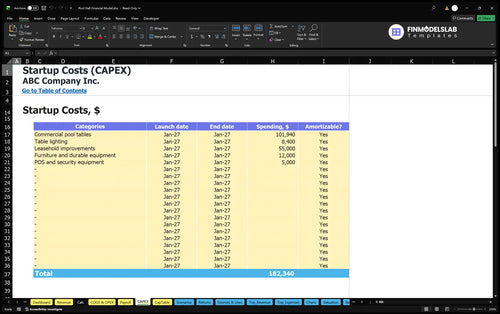
Startup assets total $182,340: commercial tables $101,940, lighting $8,400, leasehold work $55,000, furniture and equipment $12,000, plus POS and security equipment.
Other opening cash is $25,000 for the lease deposit, permits, campaign and training. Initial stock is $186.84 and the three-month recurring reserve approximately $62,513.
The Capital Expenditure Plan schedules tables, lighting, leasehold work and other durable equipment, with applicable depreciation. Capital spending is separate from maintenance and salaries.
The opening components total about $270,040 of owner funding. No outside debt is committed; optional debt controls allow separate borrowing assumptions.
Receivables and payables are set to zero days and inventory to 30 days. These cash-timing assumptions do not prove reserve sufficiency.
Sources and Uses of Funds tracks equity, optional borrowing, receipts, equipment purchases and other cash uses against planned funding.
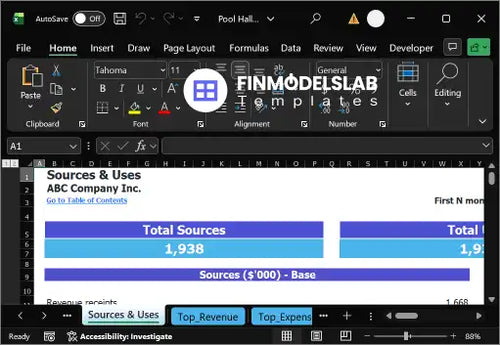
Equity, refundable deposits and CAPEX are not table-rental sales; inspect Cash Flow and Sources & Uses for cash effects.
The documented base-case illustration shows an EBITDA loss in 2026 and positive annual EBITDA from 2027 as paid utilization increases.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $224,208 | $262,052 | -$37,844 |
| 2027 | $286,986 | $256,231 | $30,755 |
| 2028 | $340,796 | $269,920 | $70,876 |
| 2029 | $385,638 | $283,120 | $102,518 |
| 2030 | $430,479 | $288,370 | $142,109 |
Forecasts are illustrative planning outputs, not historical performance or industry averages. USD values are rounded to whole dollars.
Revenue rises from $224,208 in 2026 to $430,479 in 2030 as utilization grows on the same 12 tables. Fixed costs and staffing determine EBITDA.
EBITDA excludes depreciation, interest and taxes. Later positive EBITDA does not establish net profit, free cash flow or investment payback.
The Cash Flow Forecast separates operating receipts, investments, equity and borrowing flows, reconciling opening and closing cash beyond the EBITDA table.
Income Statement, Balance Sheet and Summary support broader accounting projections; no specific net income, balance-sheet or cash-balance amounts are claimed here.
The Returns and scenario reports help test whether table-hour demand can cover operating costs and whether the project might recover its investment.
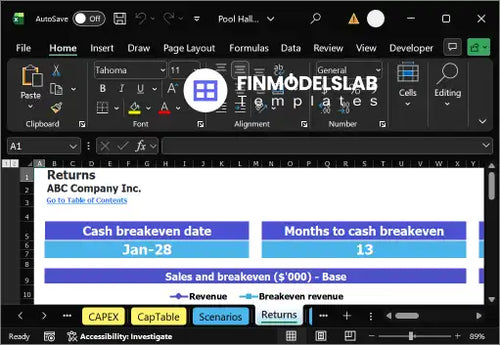
Sales break-even compares revenue and operating costs; cash break-even examines cumulative project cash flow. Payback tracks invested capital recovery, while annual ROIC measures returns on capital.
None equals EBITDA or net profit. The example establishes no tested break-even point, payback month, ROIC or IRR.
The Return on Invested Capital Analysis distinguishes sales break-even, cash break-even, payback and annual ROIC using the modeled business and funding inputs.
Dashboard Low, Base and High scenarios adjust revenue, COGS, variable costs, fixed costs and payroll to compare EBITDA sensitivity.
Valuation, sensitivity and financing results depend on edited inputs and cannot be inferred from the illustrative EBITDA figures.
The model is designed for planning a table-rental-centered pool hall rather than a full-service sports bar or restaurant.
Owners can assess capacity, pricing, utilization and the balance between public play, leagues and events before leasing space or ordering tables.
Existing operators can substitute local costs and bookings to compare staffing, EBITDA and liquidity. Food, drinks, lessons and retail require additional modeling.
Answers to common questions about the model’s bookings, expenses, funding and financial reports.
Yes. Edit the table count, daily hours, operating days and paid utilization to update available table-hours and the linked revenue forecast.
No. League and tournament bookings use dedicated shares of the same sold table-hours; organizer player entry fees and prize obligations are excluded.
No. The documented operation is an all-ages, table-rental-focused billiards hall without food, alcohol, retail or instruction revenue.
Yes. Payroll separately models one hall manager and floor-attendant FTE; the illustrative case excludes employer taxes and benefits.
Yes. It separately plans pool tables, improvements, other opening cash and owner equity, with optional debt inputs but no committed outside borrowing in the example.
No. EBITDA excludes investment and financing cash movements; inspect Cash Flow and Sources & Uses to evaluate liquidity and funding timing.
Yes. Returns includes sales break-even, cash break-even, investment payback and annual ROIC, without a guaranteed outcome or stated payback date.
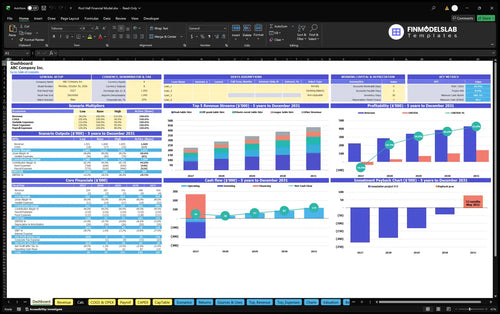
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
DCF valuation and sensitivity analysis.
Largest costs and spending trends.
Annual and monthly financial performance.
Compare margins and returns to benchmarks.

The pricing, cost, and growth inputs were all over the place before this. I cleaned them up in an hour and could finally explain the numbers without flipping between tabs.

I used to struggle to spot where the business actually made money. This model made break-even and margin checks clear enough that I could review them with my partner in one meeting.
I was worried one bad formula would throw off the whole sheet. The layout made it easy to trust the calculations and save a full afternoon of second-guessing.