SLOT MACHINE BUSINESS PLAN
I. Executive Summary
Company Description
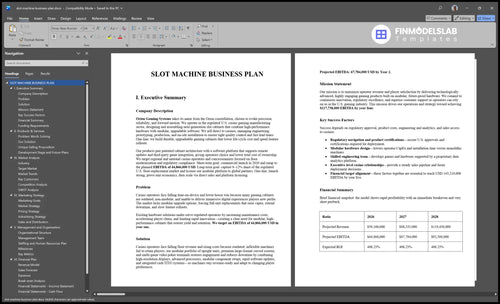
Orion Gaming Systems takes its name from the Orion constellation, chosen to evoke precision, reliability, and forward motion. We operate in the regulated U.S. casino gaming manufacturing sector, designing and assembling next-generation slot cabinets that combine high-performance hardware with modular, upgradable software. We sell direct to casinos, managing engineering, prototyping, production, and on-site installation to ensure tight quality control and fast lead times. One-line: we build durable, upgradeable gaming cabinets that lower life-cycle cost and speed feature rollouts.
Our products pair patented cabinet architecture with a software platform that supports remote updates and third-party game integration, giving operators choice and lower total cost of ownership. We target regional and national casino operators and concessionaires focused on floor modernization and regulatory compliance. Short-term goal: commercial launch in 2026 and ramp to the planned EBITDA of 44,866,000 USD. Long-term goal: capture 8–12% share of the regulated U.S. floor-replacement market and license our modular platform to global partners. One-line: launch strong, prove unit economics, then scale via direct sales and platform licensing.
Problem
Casino operators face falling time-on-device and lower house win because many gaming cabinets are outdated, non-modular, and unable to deliver immersive digital experiences players now prefer. The market lacks modular upgrade options, forcing full-unit replacements that raise capex, extend downtime, and slow feature rollouts.
Existing hardware solutions under-serve regulated operators by increasing maintenance costs, accelerating player churn, and limiting rapid innovation—creating a clear need for modular, high-performance cabinets that restore yield and retention. We target an EBITDA of 44,866,000 USD in year one.
Solution
Casino operators face falling floor revenue and rising costs because outdated, inflexible machines fail to retain players; our modular portfolio of upright units, premium large-format curved screens, and multi-game video poker terminals restores engagement and reduces downtime by combining high-resolution displays, advanced processors, modular component swaps, rapid software updates, and integrated cash/TITO systems—so machines stay revenue-ready and adapt to changing player preferences.
Projected EBITDA: 67,784,000 USD by Year 2.
Mission Statement
Our mission is to maximize operator revenue and player satisfaction by delivering technologically advanced, highly engaging gaming products built on modular, future-proof hardware. We commit to continuous innovation, regulatory excellence, and superior customer support so operators can rely on us in the U.S. gaming industry. This mission drives our operations and strategy toward achieving $117,738,000 EBITDA by year four.
Key Success Factors
Success depends on regulatory approval, product costs, engineering and analytics, and sales access to casinos.
-
Regulatory navigation and product certifications—secure U.S. approvals and certifications required for deployment.
-
Modular hardware design—lowers operator CapEx and installation time versus monolithic machines.
-
Skilled engineering team—develops games and hardware supported by a proprietary data analytics platform.
-
Executive-level casino relationships—provide a steady sales pipeline and faster deployment decisions.
-
Financial target alignment—these factors together are essential to reach USD 143,210,000 EBITDA by year five.
Financial Summary
Brief financial snapshot: the model shows rapid profitability with an immediate breakeven and very short payback.
Ratio |
2026 |
2027 |
2028 |
Projected Revenue |
$59,100,000 |
$88,335,000 |
$119,450,000 |
Projected EBITDA |
$44,866,000 |
$67,784,000 |
$92,388,000 |
Expected ROI |
498.25% |
498.25% |
498.25% |
Financial requirements include a minimum cash buffer of $1,523,000 and planned capex of $1,680,000; the plan targets breakeven in Jan-26 with a one-month payback and a high return on equity.
Outlook: strong revenue growth, expanding EBITDA, and rapid investor payback.
Funding Requirements
We require USD 3,203,000 to build operations, buy inventory, stand up IT, and maintain minimum cash for Jan-26 launch.
Categories |
Amount, USD |
Manufacturing assembly line |
500,000 |
Product development (R&D lab, software, testing) |
450,000 |
Office & showroom buildout |
150,000 |
IT infrastructure & servers |
100,000 |
Initial inventory purchase |
300,000 |
Delivery vehicle fleet |
180,000 |
Working capital (minimum cash, Jan-26) |
1,523,000 |
Total funding required |
3,203,000 |
One-liner: USD 3,203,000 funds the build, inventory, IT, and first-month cash to reach year-five EBITDA target.
Breakeven: January 2026. Year‑1 EBITDA: USD 44,866,000; Year‑5 EBITDA: USD 143,210,000. Units: 3,600 → 10,800 annually. Return on equity: 498.25%; payback period: very short.