

Revenue and Monthly Calc
Set class places, daily schedules, operating days, utilization, seasonal demand, and realized prices for five yoga formats. Monthly calculations apply launch timing and consolidate paid attendance into the revenue forecast.


The Yoga Studio Financial Model is an Excel financial planning template that turns class capacity, attendance utilization, program pricing, operating expenses, and staffing into monthly calculations and annual financial projections for 2026 through 2030.
Its illustrative case is an independent, unheated yoga studio in Raleigh-Durham, North Carolina, with one teaching room, 24 mat places, and five prepaid class formats. It models a defined operating setup, not an industry average or guaranteed business outcome.
The workbook links yoga-specific input schedules to financial statements, scenario comparisons, and management reports.
Set class places, daily schedules, operating days, utilization, seasonal demand, and realized prices for five yoga formats. Monthly calculations apply launch timing and consolidate paid attendance into the revenue forecast.
Model direct class consumables, revenue-linked fees, recurring facilities expenses, and salaried staffing separately. Monthly operating schedules connect these assumptions with costs and margins in the Income Statement.
Plan opening equipment and leasehold improvements in CAPEX, enter owner contributions in CapTable, and review funding movements through Sources & Uses and the Cash Flow Statement.
Dashboard controls select Low, Base, or High scenarios. Summary, Charts, Returns, Valuation, and Checks help inspect financial projections, break-even logic, investment measures, and model consistency without replacing underlying assumptions.
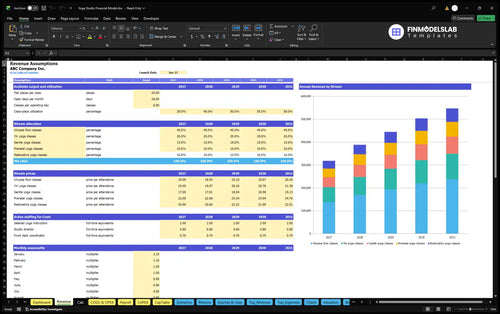
The revenue forecast sells a single pool of available class places across five prepaid formats.
One 24-mat room runs six one-hour classes per operating day for 26 days each month. That makes 3,744 available class places monthly before utilization and seasonality; the model allocates paid attendance once instead of counting separate full capacities for each format.
The initial attendance allocation is 45% Vinyasa, 20% Yin, 15% Gentle, 10% Prenatal, and 10% Restorative. Their respective 2026 realized prices are $18, $19, $17, $22, and $20 per attendance, producing a $18.65 weighted average.
The Revenue Forecast combines class-place capacity, utilization, seasonal multipliers, program shares, and realized prices. Its annual output reconciles the five format allocations into one studio revenue total, while monthly Calc applies the launch date and repeating seasonality.
3,744 monthly places × 38% average utilization × $18.65 weighted price × 12 months ≈ $318,405 revenue.
Average class-place utilization increases from 38% in 2026 to 58% in 2030, while prices rise by format. January carries a 1.15 demand multiplier; even in 2030, the resulting 66.7% January utilization stays within the shared room capacity.
Direct costs, revenue-linked expenses, fixed overhead, and salaries are forecast as distinct components.
Class consumables and minor props equal 1% of revenue in the illustrative assumptions. Payment processing and recurring local marketing each use 3.5%; refund and chargeback leakage adds 0.5%, making total variable expenses 7.5% of sales.
The COGS and Operating Expenses forecast separates direct class consumables, variable fees, and monthly fixed bills. Fixed lines cover rent, utilities, cleaning, insurance, software, subscriptions, maintenance, and professional services without including salaries already recorded in Payroll.
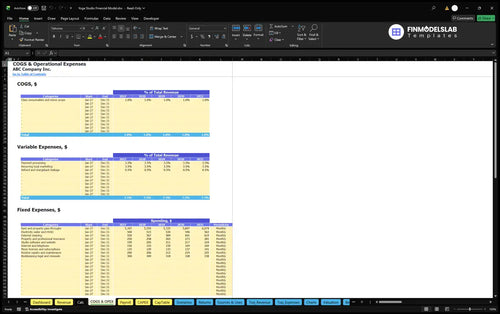
| Cost category | 2026 | 2030 |
|---|---|---|
| COGS | $3,184 | $5,469 |
| Variable expenses | $23,880 | $41,021 |
| Fixed expenses | $92,048 | $103,601 |
| Base-pay payroll | $164,000 | $164,000 |
Category amounts are rounded; employer taxes and benefits are outside this illustrative base-pay EBITDA scope.
The Payroll Forecast organizes salaried yoga instructors, a studio director, and front-desk coverage by FTE and base salary. In this case, two instructors, a 0.8-FTE director, and a 0.7-FTE coordinator contribute $164,000 in annual base payroll.
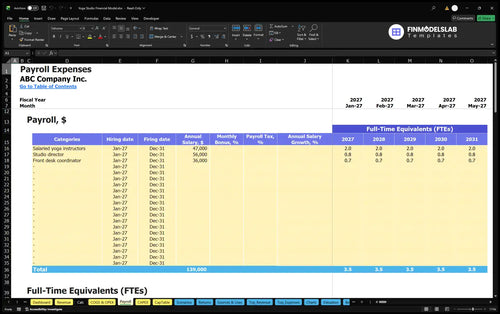
The salary calculation is 2 × $47,000 plus 0.8 × $56,000 plus 0.7 × $36,000. The staffing schedule totals 3.5 FTE, not necessarily 3.5 people, and salaries are not duplicated in direct or fixed operating costs.
Opening investment and liquidity reserves are separate from annual studio operating earnings.
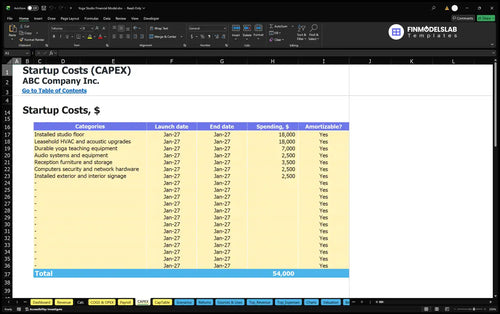
The startup plan includes an $18,000 installed floor, $18,000 in HVAC and acoustic improvements, $7,000 in durable yoga equipment, and a $2,500 audio system. Additional asset items include reception fittings, hardware, and signage.
The Capital Expenditure Plan records asset purchases, planned spending dates, and depreciation treatment. For a leased yoga studio, it helps distinguish physical fit-out and equipment investments from the recurring costs of teaching and keeping the space open.
Separate opening cash items include refundable deposits, permits, professional setup, launch marketing, preopening rent, training, utilities, and branding. The illustrative plan sets receivable and payable days at zero and inventory days at 30.
The Sources and Uses of Funds report reconciles contributions and other funding with planned operating, investment, and financing cash uses. The example assumes $157,630 of initial owner funding and no external borrowing, but this is a planning reserve, not a tested peak cash requirement.
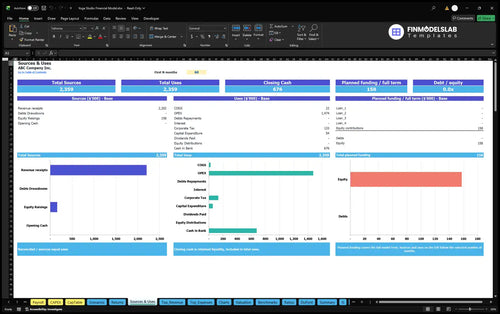
The base operating case projects growing revenue against a comparatively stable salary and fixed-cost structure.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $318,405 | $283,112 | $35,292 |
| 2027 | $388,370 | $291,821 | $96,549 |
| 2028 | $444,540 | $299,440 | $145,100 |
| 2029 | $503,586 | $307,388 | $196,197 |
| 2030 | $546,949 | $314,092 | $232,858 |
Illustrative model outputs, rounded to whole dollars; rounding can create $1 differences between displayed columns.
In the example, annual revenue rises from $318,405 in 2026 to $546,949 in 2030 as utilization and realized prices increase. EBITDA rises from $35,292 to $232,858; it remains an operating measure before depreciation, interest, taxes, and investment cash flows.
The Cash Flow Forecast tracks operating, investing, and financing cash movements and reconciles opening to closing cash. It serves a different purpose from the operating EBITDA table: users can inspect whether planned equipment spending, contributions, or debt affect liquidity.
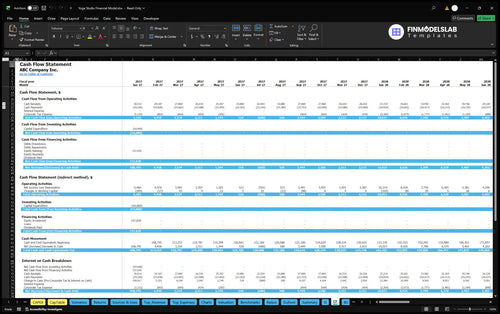
The workbook also includes projected Income Statement, Balance Sheet, Summary, and Checks reports. Their functions are available for scenario review, but the figures above do not establish net profit, an end-of-year cash position, or an independently tested funding need.
The financial model includes return analysis and scenario controls for evaluating alternative studio plans.
Sales break-even asks how much class revenue covers modeled operating costs. Cash break-even asks when cash inflows cover outflows; project payback measures recovery of invested cash, while annual ROIC relates operating returns to invested capital. These are not interchangeable.
The Returns analysis presents sales break-even, project and cumulative free cash flow, investment payback, and annual ROIC. Use it to test whether a class schedule and pricing plan could justify the initial investment, not to treat EBITDA as cash recovered.
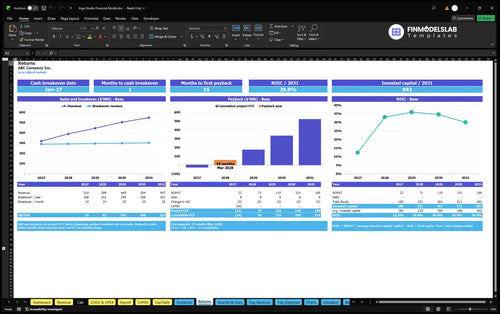
On Dashboard, Low, Base, and High controls adjust revenue and cost multipliers for scenario comparisons; Scenarios and Charts visualize their effects. Valuation adds discounted cash-flow and sensitivity analysis, but no specific valuation, ROIC, IRR, or payback date is established by the supplied operating example.
The template is designed for evaluating a class-based, unheated studio rather than unrelated fitness revenue models.
Use the model to change mat capacity, class cadence, demand seasonality, attendance mix, format prices, rent, staffing, and opening investment before reviewing the projected operating result. It is most relevant to an independent studio with one shared teaching-room capacity pool.
The example excludes retail, online or private instruction, franchise fees, and hot-yoga equipment. Assumptions are editable planning estimates; the illustrative 2026–2030 outputs are neither observed Raleigh-Durham industry results nor guarantees of customer attendance or financing.
These answers clarify which assumptions drive the template and what the illustrated outputs do not prove.
It applies monthly utilization and seasonality to 3,744 available class places, allocates attendance once among five formats, and multiplies each format by its realized price.
Yes. Revenue, Payroll, and operating input schedules support changes to class places, teaching frequency, pricing, FTE, salaries, and cost assumptions.
No. The documented illustrative operating case contains five prepaid group-yoga formats and excludes retail sales, private instruction, and online classes.
No. EBITDA excludes capital spending, financing cash flows, interest, taxes, and other adjustments; use the Cash Flow Statement to evaluate projected liquidity.
No. The initial owner funding is an estimated setup and operating reserve, not a validated maximum cash deficit or an external financing commitment.
The Returns report supports break-even, project cash-flow payback, and annual ROIC analysis; no specific payback date or ROIC result is supplied for this example.
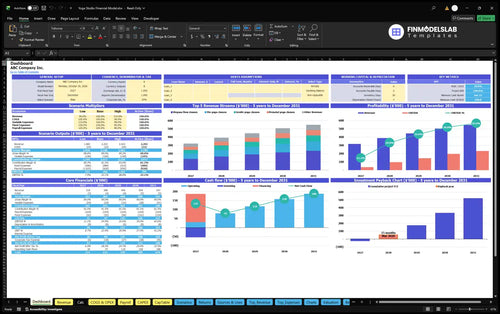
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
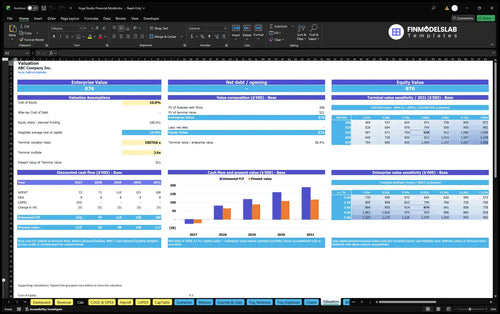
DCF valuation and sensitivity analysis.
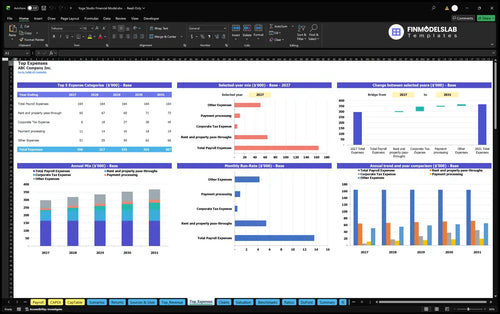
Largest costs and spending trends.
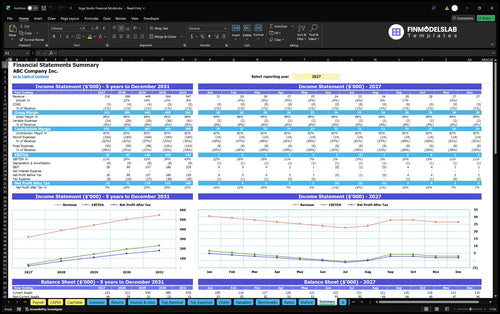
Annual and monthly financial performance.
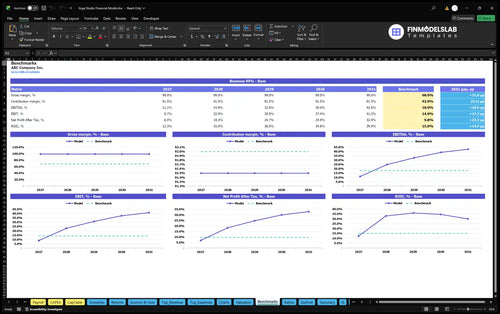
Compare margins and returns to benchmarks.

This template put pricing, costs, and growth in one place, so I stopped chasing numbers across tabs. I saved about 4 hours of cleanup and could explain the assumptions in one meeting.

The break-even and margin views made profitability obvious without me building extra sheets. I had a clear answer for our lender in under an hour, which was a big change from my usual guesswork.
Low, base, and high cases were already set up, so I wasn’t rebuilding the model three times. That cut a half day of scenario work and made our planning review much easier.