Where Does Owner Income Come From in a Bowling Alley?
Bowling Alley Bundle
A 20-lane, owner-operated Bowling Alley in the United States can reasonably produce $0 to $563,040 a year of owner income after modeled tax and reinvestment reserves, with a base case of $248,040 on $1.74 million of annual revenue. The model is an independent center with bowling, shoe rental, a bar/grill, modest arcade, leagues, and group events. The main constraints are lane utilization, spend per occupied lane-hour, payroll, facility costs, and financing. The figures exclude sale proceeds, real-estate appreciation, and personal tax liability beyond the calculator's reserve.
Owner income$248KNet margin14%Revenue for target pay$1.62MBusiness difficultyHard
Owner income calculator
Adjust bowling-center revenue, margin, staffing, facility costs, debt, and reserves to estimate residual owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Paid lane-hour utilization
31% base
With 20 lanes open about 12 hours a day, moving average paid utilization from 31% to 36% adds roughly 360 occupied lane-hours a month before any price change.
2
Revenue per occupied lane-hour
$65 base
Lane fees, shoes, food, drinks, and arcade spend combine into one practical yield metric; a $5 lift at base utilization adds about $11,000 of monthly sales.
3
Events and league mix
30% planned
The model targets roughly 30% of sales from prebooked groups and repeat league traffic so weekday and shoulder-hour lanes do not rely entirely on walk-ins.
4
Labor productivity
24% of sales
Base employee payroll is $35,000 a month before owner pay. Owner coverage of the general-manager role protects cash, but it also means the modeled income is partly compensation for work.
5
Blended direct-cost control
84% margin
Food product, payment fees, arcade sharing, and consumables are kept outside payroll; losing three margin points at base sales cuts gross profit by $4,350 a month.
6
Facility and debt load
$50K/month
Base fixed overhead plus debt service is $50,000 monthly before payroll and marketing. That load makes a bowling center unforgiving when lane traffic softens.
Want to test a full bowling-center forecast?
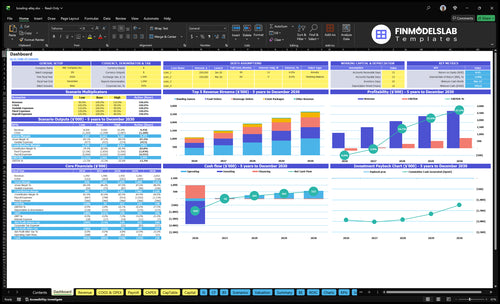
The Bowling Alley Financial Model and Projections Template provides a business-specific dashboard for testing revenue, payroll, operating costs, capital spending, cash flow, and low/base/high scenarios. Use the preview to compare lane utilization, food-and-beverage mix, staffing, debt, and reserve assumptions in one forecast.
How does a bowling alley turn lane traffic into owner income?
Think of revenue as occupied lane-hours multiplied by revenue per occupied lane-hour, then cross-check it against guest visits and booked events. In the base case, 20 lanes open about 12 hours a day create roughly 7,200 available lane-hours per 30-day month. At 31% paid utilization and a $65 blended yield from bowling, shoes, food, beverage, arcade, and events, sales land near $145,000 a month. The $65 is a planning yield, not a posted lane price: Lucky Strike Glendale pricing varies by daypart and charges shoes separately, showing why party size and add-on spend matter.
Base revenue engine
7,200 available lane-hours per month.
31% paid utilization, or about 2,232 occupied lane-hours.
$65 blended revenue per occupied lane-hour.
Result: about $145,000 monthly revenue and $1.74 million annually.
Why mix matters
Bowling is the traffic anchor, but food, drinks, shoes, arcade, and events raise yield.
Fiscal 2025 Lucky Strike revenue was 46% bowling, 35% food and beverage, and 19% amusement and other, an adjacent large-chain mix rather than a small-center target.
Use your own POS mix to decide which revenue stream actually carries contribution.
The mix matters because the U.S. Census notes that bowling centers often provide food and beverage, while a large public operator reports diversified sales. Its fiscal 2025 Form 10-K is an adjacent operating proxy, not a promise that an independent center will match chain economics.
How much revenue must a bowling alley make to pay the owner $180,000?
Under the base cost structure, the calculator needs about $134,615 a month, or $1.615 million a year, to support a $15,000 monthly owner-pay target after the modeled 25% tax reserve and 10% reinvestment reserve. Pure operating break-even is lower: with $90,000 of monthly labor, overhead, marketing, and debt service and an 84% gross margin, the center needs about $107,143 a month, or $1.29 million a year, just to reach zero profit before reserves.
Three different thresholds
About $1.29M annual revenue: operating break-even before owner reserves.
About $1.62M: supports $180K annual target owner pay after modeled reserves.
$1.74M base revenue: produces $248,040 modeled owner income after reserves.
Revenue is not profit, and profit is not automatically distributable cash.
Scale is normal, not optional
2023 Census County Business Patterns counted 3,154 U.S. bowling-center establishments.
The same table shows most establishments in employee-size bands of 10 to 49 workers.
A 20-lane owner-operated center can be smaller than a chain site, but it still carries a real facility and staffing base.
The 2023 Census County Business Patterns table for NAICS 713950 is a useful reality check on operating scale. It does not report owner earnings, so the owner-income figures here come from the reconciled planning model rather than from a Census profit statistic.
Can a bowling alley run without the owner working as general manager?
Yes, but the required revenue rises because a manager-run center must pay for work that the owner covers in this base case. The model carries $35,000 of monthly employee payroll and benefits before owner pay. April 2025 BLS data put average hourly earnings for employees in bowling centers around $19.41 per hour, so even a modest schedule quickly becomes a five-figure monthly payroll before payroll taxes, benefits, overtime, and management premiums.
Owner-operated case
The owner acts as general manager and absorbs scheduling, vendor, event, and financial oversight.
Employee payroll stays at $35,000 in the base month.
The $248,040 annual owner-income output therefore compensates both invested capital and substantial owner labor.
Do not call the entire amount passive investment income.
Manager-run case
Add a market manager salary, payroll burden, and enough supervisory coverage for nights and weekends.
At the same revenue, every extra $8,000 of monthly payroll reduces pre-reserve profit by $8,000.
With the base 35% combined reserves, that $8,000 cost reduces modeled owner cash by about $5,200 a month while profit stays positive.
Higher revenue or a lower owner draw is required to make the business more passive.
A much larger operator illustrates the staffing complexity: its 2025 filing says a typical location has a general manager, two operations managers, a facilities manager, and roughly 20 to 30 associates. An independent 20-lane center may run leaner, but that comparison explains why owner absence is not free.
How do seasonality, events, and leagues affect owner cash flow?
A bowling alley can look profitable on a full-year P&L and still feel cash-starved in weak months. Lucky Strike reports that bowling sales are seasonal, with its highest bowling sales volumes typically occurring in its fiscal third quarter because of leagues, holidays, and weather; the same filing warns that school schedules and weather shift demand by region. That seasonality disclosure is why this model treats $145,000 as an average month rather than a flat monthly guarantee.
Build a cash calendar
Forecast lane-hours by weekday, daypart, and season instead of dividing annual sales by 12.
Require deposits for large parties and corporate events where local practice allows.
Schedule lane maintenance and remodel work away from the strongest booked periods.
Keep enough operating cash that a slow summer or storm week does not force an owner draw reversal.
Use repeat traffic to fill weak hours
Leagues can stabilize recurring weekday lane use.
Birthday and corporate events create prebooked blocks and larger food-and-beverage baskets.
Track deposits, cancellations, repeat bookings, and revenue per occupied lane-hour separately.
Measure marketing by booked gross profit, not clicks or impressions.
The industry's ownership mix also favors operator-level discipline: BPAA's current Bowl Expo materials report 68% single-unit owners among the audience profile it presents. That is not a national ownership census, but it reinforces why local booking cadence, owner attention, and repeat traffic matter economically.
Key Takeaways
Base owner income is $248,040 after modeled reserves on $1.74M annual revenue, but the downside case produces no safe owner distribution.
Operating break-even is about $1.29M annual revenue; supporting a $180K owner-pay target needs about $1.62M under the base cost structure.
Owner-operated and manager-run economics are different: the base model assumes the owner performs the general-manager role and does not double-count owner pay in labor.
Safe cash comes after direct costs, employee payroll, facility overhead, marketing, debt service, tax reserve, and reinvestment reserve—not simply after positive EBITDA.
What has to be paid before owner cash is safe to distribute?
Start with gross profit, then pay employee payroll, occupancy and maintenance, marketing, and debt service before treating any residual as profit available for reserves. The base case produces $31,800 of monthly profit before reserves; a 25% tax reserve and 10% reinvestment reserve hold back $11,130, leaving $20,670 of modeled monthly owner income. SBA guidance says 7(a) rates are negotiated subject to program maximums and loan terms are generally 10 years or less unless real estate or equipment supports a longer term, so financing structure can materially change cash service; see the SBA 7(a) lender guidance.
The $14,000 monthly debt-service assumption roughly matches financing about $1.1 million over ten years at a 9% planning rate, but it is illustrative. With no debt and all else equal, modeled owner cash would rise about $9,100 a month after the 35% combined reserves. A variable-rate loan or shorter amortization can reverse that benefit without any sales change.
Revenue is sales; gross profit is sales after the direct costs modeled above. EBITDA or operating profit is not the same as distributable cash because debt principal, capital spending, taxes, and working-capital movements can sit outside that measure. Owner salary pays for work; an owner draw or distribution is residual equity cash after obligations and reserves.
Owner salary and distributions must stay separate. This calculator treats owner pay as residual cash and excludes owner wages from labor. If your entity puts the owner on payroll, move that wage into labor and reduce the residual draw; do not count the same dollars twice. The 25% tax reserve is a planning placeholder, not an effective tax rate. The IRS estimated-tax guidance explains that taxpayers without enough withholding may need estimated payments; use entity-specific tax advice for the actual reserve.
What do low, base, and high owner-income cases look like?
The scenarios do not hold costs flat. The low case keeps most facility and debt obligations while demand weakens; the high case raises payroll, marketing, and overhead for heavier traffic. The NAICS 713950 definition also recognizes that bowling centers often provide food and beverage. The owner-income row is after each case's modeled tax and reinvestment reserves.
Bowling Alley owner income scenarios
Three coherent 20-lane cases using the same calculator formulas and different demand, margin, staffing, overhead, marketing, and reserve assumptions.
Low, base, and high planning cases for a 20-lane owner-operated U.S. bowling center.
Scenario factor
Low CaseDemand stress
Base CasePlanning case
High CaseStrong demand
Launch modelOperating posture
20 lanes
Owner covers GM role
Weak walk-in traffic
20 lanes
Bar/grill + modest arcade
Balanced events, leagues, walk-ins
20 lanes
Strong events + peak traffic
More hourly staffing
Typical setupRevenue and yield
$90,000 monthly revenue
82% gross margin
About 22% paid lane utilization
$145,000 monthly revenue
84% gross margin
About 31% paid lane utilization
$220,000 monthly revenue
86% gross margin
About 42% paid lane utilization
Cost driversMonthly cash costs
$25,000 labor
$34,000 fixed overhead
$3,000 marketing
$14,000 debt service
$35,000 labor
$36,000 fixed overhead
$5,000 marketing
$14,000 debt service
$48,000 labor
$41,000 fixed overhead
$8,000 marketing
$14,000 debt service
Owner income rangeAfter modeled tax + reinvestment reserves
$0
$248,040
$563,040
Best fitHow to use the case
Stress-test a slow ramp, soft weekdays, and fixed-cost pressure with no safe owner distribution.
Plan normal operations with owner-led management, disciplined staffing, and a balanced traffic mix.
Test strong utilization only with the added labor, marketing, utilities, maintenance, and reserves required to support it.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Capital intensity is why the downside case can reach zero owner income while the center stays open. A current equipment-supplier guide quotes roughly $45,000 to $80,000 per installed commercial lane for mid-range packages, before many building and site costs. Treat that as supplier planning evidence, not a national construction average; retrofit scope and working capital can materially change financing.
What are the six biggest bowling alley income drivers?
The six drivers below control revenue density, contribution, and fixed-cost load. BPAA's current industry materials describe both traditional centers and bowling entertainment centers with many single-unit operators, so owner-level operating decisions matter more than assumed chain efficiencies.
1. Paid lane-hour utilization
Fill the lane-hours that already carry rent and debt
The base model has about 7,200 available lane-hours per month and uses 31% paid utilization, or roughly 2,232 occupied hours. At the base $65 blended revenue per occupied lane-hour, each additional five utilization points adds about 360 occupied hours and roughly $23,400 of monthly revenue before extra direct cost and staffing. That is why an empty Tuesday lane is not merely missed sales: the rent, HVAC, scoring system, insurance, and debt service are still there.
Published pricing confirms that daypart yield can vary materially. For example, Bowlero Orange County's current walk-in rates range from lower weekday pricing to higher Friday and Saturday evening pricing, with shoes separate. Your utilization KPI should therefore be revenue-weighted, not just a count of games.
Track lane yield by daypart
Use 30-minute or hourly blocks so discounts that fill lanes do not quietly destroy yield.
Paid lane-hours ÷ available lane-hours.
Revenue per occupied lane-hour.
Peak versus off-peak utilization.
Walk-in turnaways and unused reserved time.
2. Revenue per occupied lane-hour
Raise the basket, not only the game price
The base $65 lane-hour yield combines bowling, shoes, food, beverages, arcade, and event economics. A $5 increase in that yield at the same 2,232 monthly occupied lane-hours adds about $11,160 of revenue per month. Because bowling itself has relatively low product cost, a mix shift toward profitable add-ons can improve owner cash faster than chasing raw foot traffic.
Lucky Strike's fiscal 2025 results reported 46% of revenue from bowling, 35% from food and beverage, and 19% from amusement and other in its annual filing. An independent center may differ, but the mix shows why lane-adjacent spending matters.
Track the full guest wallet
Separate price from mix so you know whether higher sales came from more lane-hours or better monetization.
Bowling revenue per occupied lane-hour.
Food and beverage per bowler visit.
Shoe-rental attachment rate.
Arcade and event add-on revenue.
3. Events and league mix
Convert weak hours into contracted or repeat demand
This model uses a planning target of roughly 30% of revenue from leagues, parties, corporate outings, and other prebooked or repeat business. The exact percentage is site-specific, but the financial mechanism is clear: recurring blocks improve utilization in hours that casual traffic may not fill, while event packages can bundle lanes, shoes, food, and drinks into a larger ticket. If a center adds just four $1,500 events per month without displacing peak walk-ins, that is $72,000 of annual revenue before fulfillment costs.
Marketing should be attached to this economics. The base $5,000 monthly marketing budget is 3.4% of sales. Spend it against trackable event leads, local partnerships, league reactivation, and CRM offers rather than treating marketing as an undifferentiated overhead line.
Track booked gross profit
Do not optimize only for event count. A heavily discounted event that blocks prime lanes can be worse than normal walk-in demand.
Event lead-to-booking conversion.
Average event revenue and contribution.
League retention by season.
Deposits collected and cancellation rate.
4. Labor productivity and the owner's role
Decide whether owner income pays for labor, capital, or both
Base employee payroll is $35,000 a month, about 24% of revenue, before any owner pay. The April 2025 BLS bowling-center earnings figure of about $19.41 per hour makes it easy to see how schedule creep erodes profit: an extra 400 paid hours at that average wage is about $7,764 of wages before payroll burden. With the base reserve structure, an $8,000 monthly labor increase cuts modeled owner cash by about $5,200 while profit remains positive.
The owner-operated assumption matters. If the owner works 50 or 60 hours a week as GM, the $248,040 output is not a passive distribution. A buyer should normalize a market management wage before comparing investment returns.
Track payroll against demand
Schedule around booked lane-hours and food-service demand rather than using static staffing by habit.
Labor cost ÷ revenue.
Revenue per paid labor hour.
Overtime and split-shift coverage.
Owner hours replaced by paid managers.
5. Blended direct-cost and gross-margin control
Reconstruct margin so labor is not counted twice
The base gross margin is 84%, meaning non-labor direct costs consume 16% of sales. This is intentionally not copied from a reported restaurant-style gross margin. Lucky Strike's fiscal 2025 food-and-beverage product cost was about 22% of its food-and-beverage revenue, while payroll and location operating costs were reported separately. That structure supports a reconstructed bowling-center margin in which food product, transaction fees, arcade revenue share, and consumables sit above gross profit while all employee payroll stays in labor cost.
At $145,000 monthly sales, losing three gross-margin points removes $4,350 of monthly gross profit. After base reserves, that can reduce modeled owner cash by about $2,828 a month if profit remains positive. Track menu cost, bar pour cost, payment fees, shoe loss, and revenue-sharing agreements separately.
Track contribution by revenue stream
High sales are not useful if the direct-cost mix shifts faster than pricing.
Food and beverage product cost percentage.
Card fees and third-party commissions.
Arcade payout or revenue-share percentage.
Blended gross margin before payroll.
6. Facility overhead, maintenance, and debt load
Protect cash from the asset-heavy part of the model
Base fixed overhead is $36,000 a month and debt service is another $14,000, so the center carries $50,000 a month of facility-and-financing cash load before employee payroll and marketing. The equipment itself is specialized: one current supplier planning guide places installed commercial lane packages around $45,000 to $80,000 per lane, excluding many building costs. That is not a national average, but it explains why scoring, pinsetters, lane surfaces, kitchen systems, HVAC, and electrical capacity require continuing capital attention.
The 10% base reinvestment reserve holds back $3,180 a month when pre-reserve profit is $31,800. It is not depreciation or a guarantee against major failure; it prevents distributing every profitable dollar. Debt should also be stressed above the initial note rate because variable-rate payments can change.
Track fixed cash before owner draws
Owner distributions should be the last claim, not the first budget line.
Rent and occupancy cost ÷ revenue.
Repairs and maintenance per lane.
Debt-service coverage and rate sensitivity.
Replacement-capital reserve balance.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.