Can the Owner of a Car Rental Build a Sustainable Income?
Car Rental Bundle
For an independent, owner-operated U.S. off-airport car rental company with roughly 30 to 55 rentable vehicles, a realistic planning range in this model is about $33,696 to $175,392 a year of owner income after modeled tax and reinvestment reserves, with a base case of $62,736 on $732,000 of annual revenue. The base case assumes roughly 40 rentable vehicles, about 72% utilization, about $70 of revenue per rental day, a 72% gross margin after non-labor direct vehicle and transaction costs, $11,000 of monthly payroll, $9,000 of fixed overhead, $3,000 of marketing, and $13,000 of debt service. It assumes the owner works as the location manager; it excludes airport concession economics, franchise royalties, a separate hired general manager, final personal taxes, and any guaranteed distribution.
Owner income$62.7KNet margin9%Revenue for target pay$752KBusiness difficultyHard
How much can a car rental owner realistically make?
For this off-airport, owner-operated model, the center of gravity is about $63,000 a year after the modeled reserves, not the much larger revenue number. The base case uses $61,000 of monthly sales, or $732,000 annually. That sales level is consistent with roughly 40 vehicles producing about 875 rental days a month at a $70 revenue-per-day assumption. As an adjacent large-fleet benchmark, Avis Budget Group reported Americas revenue per day of $70.20 and vehicle utilization of 73.2% in its Q2 2026 SEC-filed key metrics. Hertz reported $62.11 of Americas revenue per day and 79% total utilization in its Q2 2026 earnings release. Those are scale operators, so they are useful operating proxies rather than small-business profit benchmarks.
Sales do not equal owner pay. At a 72% gross margin, the base case leaves $43,920 a month after non-labor direct costs. Payroll, fixed overhead, marketing, and debt service consume $36,000, leaving $7,920 before reserves. Tax and reinvestment reserves hold back $2,692, so modeled owner income is $5,228 per month, or $62,736 per year. It is residual planning cash, not guaranteed W-2 salary, GAAP net income, or EBITDA.
Owner income calculator
Test how rental revenue, fleet economics, staffing, debt, and reserves change owner take-home.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Fleet utilization
65%-80%
More paid rental days spread fixed site, staffing, and fleet costs across productive inventory; a few utilization points can move owner cash by thousands each month.
2
Revenue per rental day
$62-$70/day
Rate, class mix, length of rental, and add-ons determine how much each occupied vehicle day contributes before payroll, overhead, and debt.
3
Fleet carrying cost and debt
$13K/mo debt
The base planning case carries substantial principal-and-interest service, so purchase price, loan terms, resale value, and replacement timing directly constrain distributions.
4
Direct vehicle cost and downtime
28% direct cost
The base 72% gross margin assumes non-labor direct costs stay near 28% of sales; claims, repairs, cleaning, insurance allocation, and downtime can erase that spread quickly.
5
Labor productivity and owner role
$11K/mo payroll
The base is owner-managed. Hiring management or overstaffing counter, cleaning, and lot coverage reduces residual cash unless rental-day volume rises with payroll.
6
Direct demand, add-ons, and acquisition
$3K/mo marketing
Local search, repeat renters, corporate accounts, and well-priced add-ons can improve contribution, but paid demand must earn back its acquisition cost in completed rental days.
Want to test fleet utilization and owner pay in a full forecast?
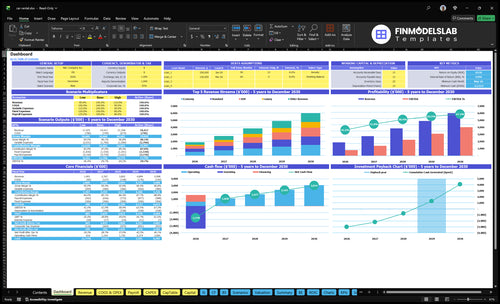
The Car Rental Financial Model Template in Excel provides a dashboard for testing revenue, cash flow, fleet assumptions, and scenarios. Use the preview to pressure-test rental-day volume, pricing, payroll, financing, break-even, and cash runway against the owner-income assumptions above.
What revenue and fleet size can support a $72K owner target?
The base case needs about $62,626 of monthly revenue, or $751,512 annualized, to support a $6,000 monthly owner-income target after the modeled reserves. Base sales of $61,000 miss that target by $772 of owner cash. The revenue build is roughly 40 vehicles times 30.4 days, 72% utilization, and $70 revenue per occupied vehicle day. The FTC's rental-car consumer guidance notes that fees, fuel, mileage, tolls, additional drivers, equipment, and waiver products can affect the total price, so operators should separate earned revenue from taxes and pass-throughs.
Revenue build
About 40 rentable vehicles in the base case
About 875 paid rental days per month
$70 modeled revenue per rental day
Approximately $61,000 monthly revenue
Target-pay bridge
$62,626 monthly revenue required
$61,000 base monthly revenue
-$772 monthly target-pay gap
Price, utilization, or cost must improve
How much utilization is enough to break even?
At the base cost structure, about 59% utilization covers operating cash costs before owner income and reserves, while roughly 74% utilization is needed to support the $6,000 monthly owner target at the same $70 revenue per day. The math is straightforward: $36,000 of monthly operating costs divided by a 72% gross margin equals $50,000 of revenue needed before reserves and owner pay. Across 40 vehicles and 30.4 days, that is about 59% utilization. For perspective, Avis reported 70% vehicle utilization in its Q1 2026 operating results; a small local fleet should not assume it can match a national network every month.
Operating break-even
$36,000 monthly operating costs
72% modeled gross margin
$50,000 monthly revenue threshold
About 59% utilization at $70 per day
Owner-pay threshold
$62,626 monthly revenue needed
About 74% utilization at the same fleet and rate
Base utilization is 72%
Downtime makes the gap harder to close
How do staffing and debt change the owner's distribution?
Base payroll is $11,000 and debt service is $13,000, consuming $24,000 each month before fixed overhead and marketing. In 2025, BLS rental and leasing data showed median hourly wages of $18.60 for counter and rental clerks, $17.74 for vehicle cleaners, and $27.90 for first-line retail supervisors in its NAICS 532 wage table. The base owner fills the location-manager role, so owner labor is excluded from payroll and take-home is the residual.
A supervisor at roughly $27.90 an hour is about $4,800 a month in wages before employer taxes and benefits. An illustrative $5,500 all-in manager cost requires about $7,639 of extra monthly revenue at a 72% gross margin to preserve pre-reserve cash. The SBA 7(a) program terms show monthly principal-and-interest repayment and rate caps tied to a base rate; the $13,000 debt line here is a planning assumption, not a quoted SBA payment.
Owner-operated case
Owner works as location manager
$11,000 monthly employee payroll
Owner pay is not buried in labor
Residual cash becomes modeled owner income
Debt sensitivity
$13,000 monthly base debt service
Every $1,000 reduction lifts pre-reserve cash by $1,000
At base reserves, about $660 remains for owner income
Fleet terms can matter as much as rate increases
What has to be paid before car rental cash is safe to distribute?
Safe distribution comes after direct vehicle costs, payroll, fixed overhead, marketing, debt service, taxes, and a fleet-replacement reserve. AAA's consumer-use study is not a rental-fleet benchmark, but its 2025 vehicle ownership analysis reported $4,334 of annual depreciation on its average new vehicle, illustrating why asset value loss matters. Rental operators also face commercial insurance, claims, repairs, downtime, financing, and remarketing risk.
Keep the labels separate. Revenue is earned rental and add-on sales before expenses. Gross profit here is revenue after non-labor direct rental costs. “Profit before reserves” is a cash-planning residual after labor, overhead, marketing, and debt service; it is neither EBITDA nor GAAP net income. EBITDA can be positive while distributable cash is weak because loan principal, replacement vehicles, deductibles, and working capital still consume cash.
Owner salary and distributions also need separate treatment. This base case puts no owner wage in labor; the residual $5,228 monthly output is modeled owner take-home after reserves. If the company pays the owner through payroll, that wage belongs in labor and distributions are only the cash left afterward. Counting both would double-count compensation.
Key Takeaways
The base case produces $62,736 of annual owner income after modeled reserves on $732,000 of revenue.
About $751,512 of annualized revenue is needed to support a $72,000 owner target at the base cost structure.
Owner labor is not free: hiring a manager must be matched by more revenue, higher margin, or a lower distribution.
Cash held for taxes, claims, repairs, fleet replacement, and debt comes before a safe owner draw.
What do low, base, and high owner-income cases look like?
The modeled annual owner-income outcomes are $33,696 in the low case, $62,736 in the base case, and $175,392 in the high case, all after each scenario's tax and reinvestment reserves. The high case is not simply higher revenue with unchanged expenses: it also carries more labor, higher fixed overhead, more marketing, and more debt service to support a larger fleet and greater volume. The low case keeps minimum costs that do not disappear just because demand is weaker.
Owner income scenarios
Compare a smaller slow-demand fleet, the owner-operated base case, and a larger stronger-demand case with matching cost increases.
Low, base, and high car rental owner-income planning cases.
Scenario factor
Low CaseLow income
Base CaseBase income
High CaseHigh income
Launch modelFleet and revenue posture
About 30 vehicles, owner-run, with $42,000 monthly revenue and slower demand.
About 40 vehicles, owner-managed, with $61,000 monthly revenue and balanced utilization.
About 55 vehicles with scaled staff, $104,000 monthly revenue, and stronger utilization and mix.
Typical setupCore financial assumptions
70% gross margin
$7,000 labor
$7,500 fixed overhead
$2,000 marketing and $9,000 debt
18% tax plus 10% reinvestment reserve
72% gross margin
$11,000 labor
$9,000 fixed overhead
$3,000 marketing and $13,000 debt
22% tax plus 12% reinvestment reserve
74% gross margin
$17,000 labor
$12,500 fixed overhead
$5,500 marketing and $18,000 debt
24% tax plus 15% reinvestment reserve
Cost driversWhat can squeeze cash
Low utilization
Minimum site overhead
Fleet debt that does not flex with demand
Owner covers management shifts
Utilization near the pay threshold
Rate and add-on discipline
Direct vehicle cost control
Owner-managed labor structure
Higher payroll and overhead
More marketing
More fleet debt
Higher claims and downtime exposure
Owner income rangeAfter tax + reinvestment reserves
$33,696
Annual owner income after modeled reserves.
$62,736
Annual owner income after modeled reserves.
$175,392
Annual owner income after modeled reserves.
Best fitHow to use the case
Stress-test a smaller fleet when demand is soft, debt still has to be paid, and owner cash is thin.
Use as the central planning case for an owner-operated independent off-airport business with balanced demand.
Test upside only when stronger demand can support the additional vehicles, staffing, marketing, overhead, and financing.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move car rental owner income the most?
These six levers connect operations to owner cash: productive rental days, revenue per day, fleet carrying cost, direct margin, labor burden, and acquisition economics. Track utilization, contribution per rental day, cost per rentable unit, and cash left after financing and reserves.
1. Fleet utilization
Turn available car days into paid car days
Utilization is the strongest lever because fleet and site costs remain when cars sit idle. Forty vehicles times 30.4 days and 72% utilization produces about 875 paid rental days; at $70 per day, that is about $61,300 of monthly revenue before rounding. Avis reported 73.2% Americas utilization in Q2 2026 company results, but an independent location has less network balancing power.
A five-point utilization gain creates about 61 extra rental days monthly, or roughly $4,256 of revenue at $70 per day. At a 72% margin, about $3,064 reaches gross profit; after the base reserves, roughly $2,022 could reach owner cash if other costs stay unchanged.
Track productive days, not just fleet count
A bigger fleet helps only when it adds rentable days that customers actually buy. Separate demand downtime from maintenance, recalls, accident repair, cleaning delay, and vehicles held for sale.
Paid rental days divided by available car days
Out-of-service days by cause
Utilization by vehicle class
Revenue per available vehicle day
Owner income improves when the same capital base produces more paid days without triggering equal growth in payroll or claims.
2. Revenue per rental day
Price the occupied day, not the sticker rate
Revenue per day captures rate, class mix, rental length, discounts, and ancillary income. Hertz reported $62.11 of Americas RPD and 79% total utilization in its Q2 2026 operating metrics, while Avis reported about $70. The base uses $70 as a planning assumption; replace it with net realized revenue from your bookings.
At about 875 paid days a month, every $5 change in realized RPD moves monthly revenue by roughly $4,378. With a 72% gross margin and no other cost change, that is about $3,152 of monthly gross profit before reserves. A rate increase that causes utilization to drop can therefore be worse than a slightly lower rate that keeps vehicles moving.
Track net RPD and mix together
Do not congratulate the business for a higher posted rate if discounting, commission, or weak utilization reduces contribution. Compare rate by class, channel, length of rental, and weekday or weekend.
Net revenue per paid rental day
RPD by vehicle class and channel
Discount rate versus utilization
Add-on revenue per rental day
The owner benefits when higher RPD survives direct costs and does not require disproportionate acquisition spend.
3. Fleet carrying cost and debt
Buy and finance vehicles for the cash they can earn
Fleet cost includes financing, depreciation or lease economics, registration, insurance structure, and disposal value. Large fleets provide context: Hertz reported $304 of monthly depreciation per unit in Americas RAC in Q2 2026, and Avis reported per-unit fleet costs near $301. Those are not independent-dealer budgets because scale, vehicle mix, holding periods, and remarketing differ.
The base uses $13,000 of monthly debt service. Every $100 of monthly carrying-cost difference across 40 vehicles equals $4,000 a month. Principal payments can leave little distributable cash even when EBITDA is positive, so model acquisition price, term, down payment, resale timing, and amortization by unit.
Track the all-in cost per rentable unit
Match each vehicle's monthly carrying cost to its rental days and realized revenue. A vehicle that looks profitable before financing can still destroy cash when it sits idle or sells below the assumed residual value.
Debt service per rentable vehicle
Depreciation or resale loss per unit
Loan balance versus expected resale value
Fleet age and replacement schedule
Distribution capacity rises when each financed vehicle pays for its own capital burden before the owner treats the remaining cash as earnings.
4. Direct vehicle cost and downtime
Protect the 72% modeled gross margin
The base assumes direct rental costs of about 28% of revenue, leaving a 72% gross margin; that is a planning assumption, not a published small-fleet benchmark. Direct costs include variable maintenance, tires, cleaning supplies, commercial insurance and claims, roadside support, registration, processing, and booking-linked charges. May 2025 BLS data show a $24.34 median hourly wage for automotive service technicians in the national occupational wage table.
Here's the sensitivity: a three-point direct-cost deterioration turns a 72% gross margin into 69%. On $61,000 of monthly revenue, that removes $1,830 from profit before reserves. With the same 34% combined reserves, about $1,208 of monthly owner cash disappears. Downtime can be worse because it creates repair cost and removes sellable car days at the same time.
Track cost per rental day and days lost
Monthly repair dollars are incomplete without a denominator. Divide variable vehicle costs by paid rental days, then separately track how many available days each repair or claim removes.
Direct cost per paid rental day
Maintenance cost per 1,000 miles
Net claim and deductible cost
Repair days out of service
The owner earns more when cost control protects both the margin on each rental day and the number of days available to sell.
5. Labor productivity and owner role
Price owner labor before calling the rest profit
The base carries $11,000 of monthly employee labor while the owner manages the location. BLS's 2025 rental and leasing data show median hourly pay of $18.60 for counter clerks, $17.74 for vehicle cleaners, and $27.90 for first-line retail supervisors in the rental and leasing industry wage series. Benefits, payroll taxes, workers' compensation, and overtime raise actual cash cost.
If replacing the owner with a manager costs an illustrative $5,500 a month, roughly $7,639 of extra monthly revenue is needed at a 72% margin to keep pre-reserve cash unchanged. Without that growth, active owner income becomes a lower passive distribution.
Track payroll against completed rental work
Schedule counter, cleaning, shuttle, and lot coverage to reservation peaks rather than using a fixed staffing pattern. Log owner hours separately so the P&L does not hide unpaid management labor.
Payroll dollars per paid rental day
Reservations handled per labor hour
Cleaning turns per paid hour
Owner hours by role each week
Owner distributions become more durable when the business can fund management labor without relying on unpaid owner coverage.
6. Direct demand, add-ons, and acquisition
Make marketing pay for completed rental days
The base spends $3,000 a month on marketing, which should be judged against contribution, not clicks. The FTC's rental guidance describes charges and optional products such as fuel, mileage, tolls, equipment, additional-driver fees, and damage waivers. They can raise customer revenue, but operators must disclose them appropriately and cannot assume every renter buys add-ons.
At $70 RPD and a 72% gross margin, one incremental paid day contributes about $50.40 before labor, overhead, debt, and reserves. So $3,000 of marketing needs about 60 incremental paid days to cover itself at gross-profit level without repeat value. Corporate accounts, referrals, repeat renters, and local search can spread acquisition cost across more bookings.
Track acquisition cost to realized contribution
Measure completed rentals by source, then compare marketing spend with rental-day contribution and repeat behavior. Treat add-on revenue as a separate KPI so a higher total ticket is not mistaken for a higher base rate.
Customer acquisition cost per completed rental
Direct booking share
Repeat-renter rate
Add-on revenue per rental day
Owner cash improves when marketing creates profitable rental days that recur, not when it merely fills the top of the booking funnel.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.