

Revenue and Calc
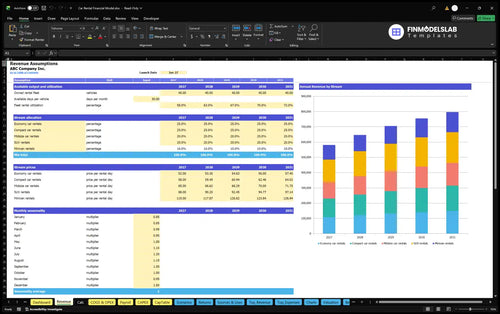
Edit fleet capacity, utilization, class mix, prices, and seasonality. Calc produces the monthly revenue forecast.


This Excel car rental financial model translates fleet capacity, rental prices, utilization, and seasonality into monthly revenue, expenses, and illustrative five-year projections.
The case models an off-airport Atlanta branch with 40 owned vehicles in five classes, launching January 31, 2026. Forecast years are 2026–2030, in US dollars; the launch month counts as full.
The workbook links rental-day assumptions to monthly calculations, financial statements, investment schedules, and decision-ready reports.
Edit fleet capacity, utilization, class mix, prices, and seasonality. Calc produces the monthly revenue forecast.
Plan revenue-based costs, monthly commitments, and role-based FTE and salaries.
Separate vehicle and equipment investments from opening cash expenses, equity contributions, and optional financing facilities with repayment schedules.
Review the Income Statement, Cash Flow Statement, Balance Sheet, and supporting reconciliations. The illustrative business-case figures provided below cover operating performance through EBITDA only.
Explore Dashboard scenarios, Sources & Uses, Returns, Valuation, Benchmarks, and charts; report functions are not verified outcomes.
One shared pool of rentable vehicle-days is allocated across five classes, then multiplied by each class’s daily rental price.
Capacity is 40 cars at 30 available days per car per month. Estimated utilization climbs from 58% in 2026 to 72% in 2030; monthly seasonality averages 1.00.
Economy and compact each receive 25% of rented days; midsize and SUV, 20% each; and residual minivans, 10%. Each class draws from one shared pool.
The Revenue Forecast shows capacity, utilization, class mix, daily prices, and class revenue. Calc applies launch timing and monthly seasonality to derive rented days and sales.
40 vehicles × 30 days × 58% utilization × 0.85 seasonality = 591.6 rented vehicle-days.
At $52 per economy day, the 25% share produces about $7,691 in January economy revenue. Rates change annually; the fleet remains at 40 vehicles.
There is no independent class demand forecast. Customer taxes, refundable deposits, optional products, disposals, and fleet refresh proceeds are excluded.
The financial model applies revenue-based cost percentages, pays fixed monthly commitments, and calculates role-based salaries without duplication.
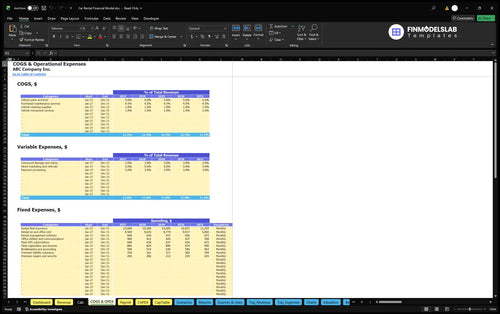
COGS percentages are parts and tires 5%, purchased maintenance 4.5%, cleaning supplies 1%, and vehicle movement 1%. Variable expenses are damage and claims 3%, marketing and referrals 5%, and processing 3% of revenue.
Fixed expenses cover insurance, rent, software, GPS, utilities, registration, accounting, and premises upkeep. Fleet insurance starts at $10,000 monthly in 2026, paid twelve times.
The COGS and Operating Expenses forecast separates direct costs, variable revenue-based charges, and fixed monthly commitments. It shows how increasing sales affect costs differently from insurance and rent.
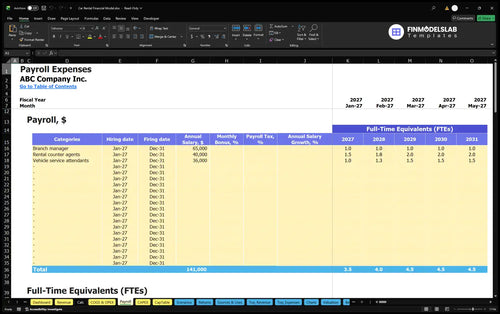
Payroll is separate: the 2026 plan has one $65,000 branch manager, 1.5 counter-agent FTE at $40,000 per FTE, and one $36,000 service attendant.
Counter-agent and attendant FTE rise later; management stays at one FTE. Salaries appear once; employer taxes and benefits are excluded from this example.
The Payroll Forecast shows staffing plans, annual-average FTE, pay per role, and the resulting personnel expense schedule. For this car rental case, the documented annual base-pay total increases from $161,000 in 2026 to $199,000 in 2030.
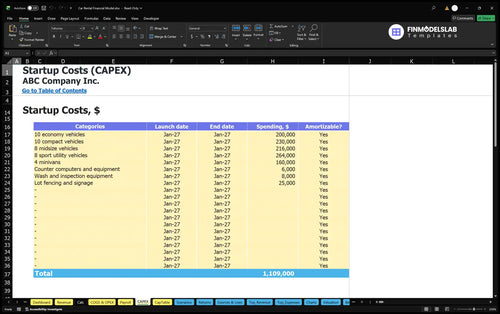
Opening fleet assets and setup cash are planned separately from recurring rental operations and EBITDA.
Estimated startup assets total $1,109,000: ten economy cars for $200,000, ten compacts for $230,000, eight midsize cars for $216,000, and eight SUVs for $264,000, plus minivans and equipment.
The Capital Expenditure Plan records vehicle and equipment purchases, expenditure dates, depreciable items, and related asset schedules. These initial investments are not the same as recurring repairs, maintenance, or operating payroll.
Opening needs add $28,000 setup cash, about $1,433 material inventory, and a $126,798 three-month reserve. Owner funding is estimated at $1,265,231; outside funding is unconfirmed.
Working-capital controls use zero receivable days, zero payable days, and eight inventory days. They affect cash timing, not the demonstrated EBITDA.
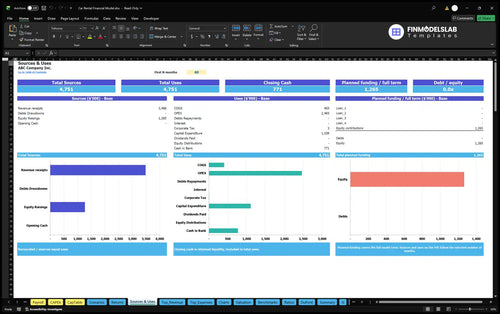
The Sources and Uses of Funds report reconciles equity, debt, operating receipts, investing, and financing payments. It distinguishes opening funds from rental operating earnings.
The selected Atlanta branch assumptions produce increasing annual rental revenue and EBITDA from 2026 through 2030.
| Year | Revenue | Expenses | EBITDA |
|---|---|---|---|
| 2026 | $581,299 | $507,192 | $74,107 |
| 2027 | $647,183 | $547,478 | $99,705 |
| 2028 | $705,486 | $586,252 | $119,234 |
| 2029 | $755,526 | $604,367 | $151,159 |
| 2030 | $796,542 | $620,657 | $175,886 |
Example projections, not actual results or industry averages. Whole-dollar rounding can create small differences between displayed figures.
The 2026 case projects $581,299 revenue, $507,192 operating expenses, and about $74,107 EBITDA. In 2030, projected revenue is $796,542 and EBITDA is $175,886.
EBITDA is earnings before interest, taxes, depreciation, and amortization. The case details do not establish a net profit, final cash balance, or shareholder return; those require separate financial-statement and financing assumptions.
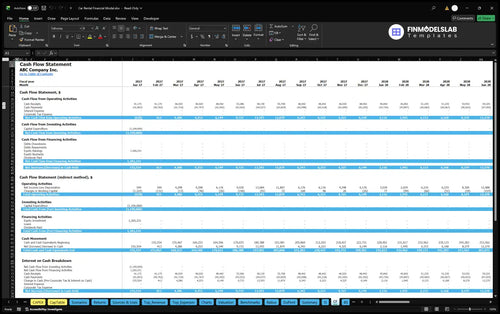
The Cash Flow Forecast tracks operating, investing, and financing movements and reconciles opening to closing cash. Use it to assess liquidity after fleet purchases and funding flows.
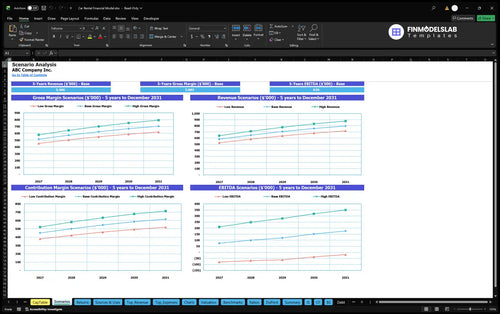
Dashboard multipliers compare Low, Base, and High cases for revenue, COGS, variable expenses, fixed costs, and payroll. These are alternatives, not guarantees.
The Financial Scenario Analysis compares revenue, margins, and EBITDA under Low, Base, and High multipliers. It helps assess downside expenses and alternative sales outcomes.
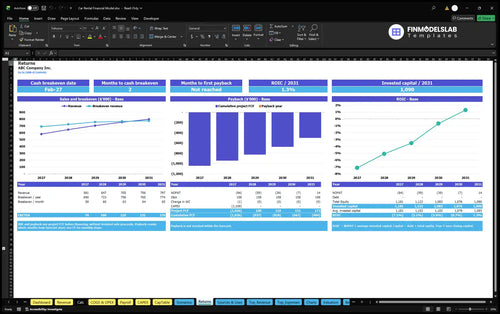
The available investment reports help distinguish operating coverage, cash recovery, and returns on invested capital.
Sales break-even measures cost coverage; cash break-even measures cash timing. Payback tracks recovery of the initial investment through cumulative project cash flow, whereas annual ROIC relates returns to invested capital.
EBITDA is not any of these metrics. The case gives no verified break-even point, payback month, ROIC, or valuation.
The Returns report combines operating sales break-even, cash break-even, investment payback, and annual ROIC calculations. It helps test whether the proposed 40-vehicle branch economics and its substantial opening asset investment justify further review.
Other reports cover valuation sensitivity, ratios, KPI benchmarks, and revenue and expense trends. No return, valuation, or benchmark result is asserted here.
The template is suited to planning and comparing an owned-fleet rental branch with class-level pricing and a defined asset budget.
Operators can test rental rates, utilization, seasonality, staffing, and overhead while keeping vehicle investment separate from operating earnings.
Change the estimates for a different fleet, location, or financing structure, and review Checks. Atlanta figures are illustrative, not transferable outcomes.
These answers clarify the workbook inputs, the illustrative operating case, and the difference between earnings and investment cash flows.
Yes. The Revenue inputs start with 40 owned vehicles, but you can change fleet capacity, utilization, class allocation, and daily rates to test another plan.
No. One utilization-adjusted pool of rented vehicle-days is allocated across the five rental classes, avoiding double counting.
No. Startup fleet and equipment purchases are modeled as capital investments; EBITDA reflects the documented operating revenue and expenses.
Yes. Twelve monthly multipliers adjust rented days, and the launch gate excludes months before January 31, 2026.
Yes. Payroll plans role-level FTE and salaries separately from revenue-based and fixed operating expenses.
Yes. The workbook includes CapTable, debt controls, Cash Flow, and Sources & Uses, but the example documents only estimated owner funding.
No. EBITDA is not free cash flow; payback and ROIC require separate investment and cash-flow analysis.
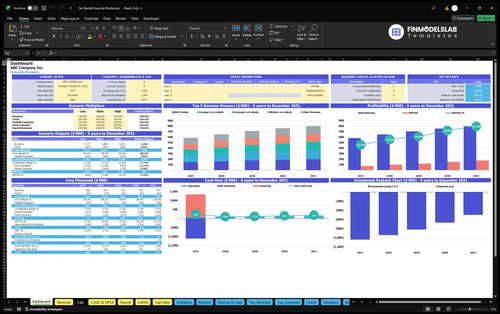
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
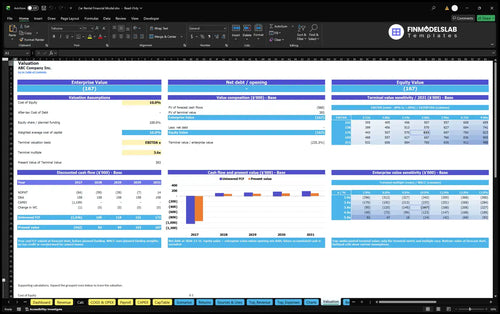
DCF valuation and sensitivity analysis.
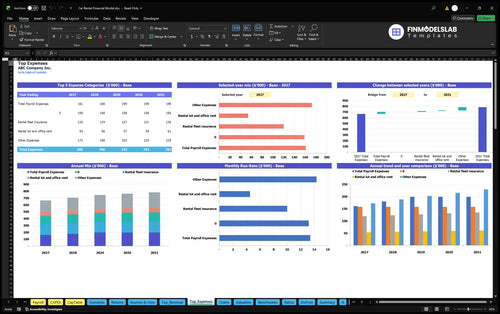
Largest costs and spending trends.
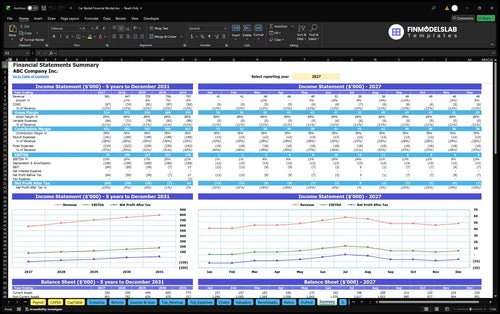
Annual and monthly financial performance.
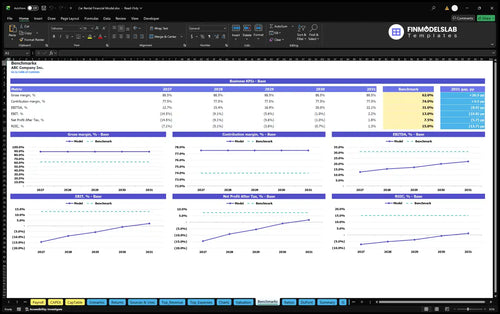
Compare margins and returns to benchmarks.

This template put pricing, fleet costs, and growth assumptions in one place, so I could finally see the numbers clearly. It saved me a full day of rework and made the forecast easier to explain.

I’m not deep in Excel, and this model kept the formulas and tabs simple to follow. I got my first full 5-year projection built without hiring a spreadsheet expert.
Building a car rental forecast from scratch would have taken me days, but this template had the structure ready to go. I cut the setup time down to one afternoon and moved straight into planning.