How Do Revenue and Margin Affect Owner Pay in a Nonprofit Organization?
A founder of a small U.S. 501(c)(3) public charity can realistically earn about $79,000 a year in the base case modeled here, with a low case near $15,000 and a stronger $1.08 million-revenue case supporting about $142,000. This article models a community-focused nonprofit with one paid founder/executive director, mixed donations and grants, with no equity owners. Base revenue is $780,000 a year, direct non-labor program costs consume 32% of usable revenue, hired payroll before founder pay is $294,000 a year, and other operating costs include facilities, administration, fundraising, and modest debt service. A nonprofit founder cannot take an owner draw or dividend: the IRS 501(c)(3) rules prohibit net earnings from inuring to private individuals, while reasonable compensation for actual services is allowed. The modeled “owner income” therefore means annual compensation capacity after a 15% reinvestment reserve, not a distribution of surplus. It excludes the founder's personal income taxes, state-specific charitable-solicitation costs, unusual restricted grants, and any compensation level the board cannot support with comparability data.
Owner income$79KNet margin10%Revenue for target pay$779KBusiness difficultyHard
How much founder pay can this nonprofit model support?
The base case supports $6,545 a month, or $78,540 a year, after setting aside 15% of positive operating surplus for reinvestment. That result is close to the compensation market rather than an arbitrary draw: the BLS May 2025 national wage table reports a $88,880 mean annual wage for social and community service managers and a $38.65 median hourly wage. A founder's actual salary can be higher or lower depending on duties, geography, budget size, and comparable organizations, but it must be compensation for work, not a claim on net assets.
Owner income calculator
Test how usable revenue, program costs, payroll, reserves, and a target founder salary change compensation capacity.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Usable Funding Mix
$65K/mo
Founder pay depends on revenue that can legally and practically cover shared payroll and overhead, not simply the gross amount sitting in the bank.
2
Contribution Margin
68%
After non-labor program costs, each usable dollar must leave enough contribution to cover payroll, administration, reserves, and executive compensation.
3
Staffing Load
$24.5K/mo
Hired payroll is the largest modeled cash cost before founder pay, so adding roles faster than funding grows compresses compensation capacity quickly.
4
Donor Retention
43.3%
Sector retention makes repeat giving a major planning variable; weak renewal forces the organization to spend more to replace lapsed donors.
5
Reserve Discipline
15%
The base model retains part of positive surplus before founder compensation capacity so grant delays or program shocks do not immediately hit payroll.
6
Compensation Governance
3 comparables
For organizations under $1 million in gross receipts, IRS guidance allows three comparable organizations as part of reasonable-compensation support.
What revenue level supports a paid nonprofit executive director?
In this model, about $644,000 of annual usable revenue covers operating costs before founder compensation and reserves, while about $779,000 supports the $78,000 annual target compensation after the 15% reinvestment reserve. The distinction between gross receipts and spendable cash matters: IRS reporting treats gross receipts as total amounts received before expenses, but a board still has to ask whether particular grants or gifts can pay shared costs. The IRS Form 990 filing thresholds also show that a $780,000 organization is firmly in full Form 990 territory, which brings more reporting and governance work than a tiny volunteer charity.
Revenue that can carry payroll
Base usable revenue: $65,000 per month.
Base direct non-labor program costs: 32% of revenue.
Base hired payroll before founder pay: $24,500 per month.
Operating break-even before founder pay: about $53,676 per month.
What changes the threshold
A restricted grant may fund a program but not the executive director.
Higher payroll can require new grant capacity before any salary increase.
A 1-point contribution-margin change is worth $7,800 a year at $780,000 revenue.
Debt and reserve policy raise the cash hurdle even when accounting surplus is positive.
Why can a nonprofit show a surplus but still have no safe founder pay?
Because surplus, liquidity, and compensation are three different decisions. A nonprofit can report positive change in net assets while cash is tied to donor restrictions, receivables, prepaid program commitments, or a reserve policy. The National Council of Nonprofits reserve guidance notes that many nonprofits operate with less than three months of reserves and emphasizes that no single reserve standard fits every organization. For this article, the 15% reinvestment reserve is a planning assumption, not a universal rule.
Accounting surplus is not a draw
Revenue minus expenses can create an accounting surplus.
Debt principal is a cash outflow that can exceed the income-statement interest expense.
Restricted net assets may be unavailable for general payroll.
Equipment, insurance renewals, and grant-match obligations still need cash.
Compensation must stand on its own
Founder salary is payment for services, not residual ownership profit.
Board approval should be independent of the founder receiving the pay.
Comparability data should match duties, budget, geography, and complexity.
Distributions of net earnings to insiders are not a nonprofit compensation method.
Want to test funding mix, payroll, and runway in a full forecast?
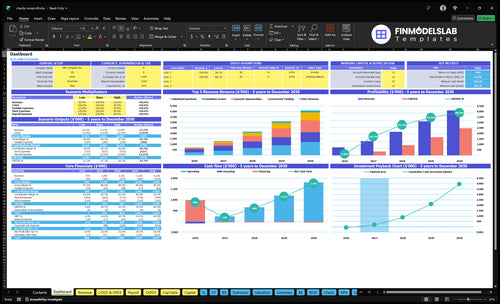
The Charity Nonprofit Financial Model Template for Excel and Google Sheets includes a nonprofit dashboard view for revenue streams, payroll, cash flow, and scenario testing. The screenshot is useful for checking whether a proposed executive salary is supported by recurring unrestricted funding, whether direct program costs leave enough contribution, and how reserves behave when grants arrive unevenly. Treat the template as a forecasting tool; the compensation and operating assumptions in this article come from the external benchmarks and planning logic discussed here.
How do donor retention and grant restrictions change founder income?
They change both the amount and timing of cash available for compensation. The Fundraising Effectiveness Project's Q4 2025 results put overall donor retention at 43.3% while donor counts fell 3.6%, so a nonprofit that assumes every donor repeats is building salary on fragile revenue. At the same time, the broader giving pool is large: Giving USA 2026 estimates $617.20 billion in U.S. charitable giving during 2025. National growth does not guarantee a local charity's renewal rate, grant wins, or unrestricted share.
Fundraising math to watch
If 1,000 donors average $300 a year, donations produce $300,000.
At 43.3% retention, only about 433 of those donors repeat without replacement.
A $100,000 grant can be valuable but still unusable for executive pay if restricted.
Recurring unrestricted gifts reduce the amount of annual reacquisition needed.
Grant overhead is a negotiation
Federal awards distinguish direct from indirect costs.
The 2 CFR 200.414 de minimis rule allows eligible recipients without a negotiated rate to elect up to 15% of modified total direct costs.
That leaves less room for compensation even if program revenue is growing.
Key Takeaways
A nonprofit founder is paid for work; there is no lawful owner distribution of net earnings.
The base model needs about $779,000 of annual usable revenue to support a $78,000 compensation target after reserves.
Payroll, direct program cost, donor renewal, and restricted cash can matter more than headline fundraising totals.
Board-approved comparability, adequate liquidity, and clear separation of salary from surplus are part of the financial model, not paperwork added later.
How should salary, surplus, and distributions be separated?
For a 501(c)(3), the cleanest answer is: salary can be paid for actual services, surplus belongs to the organization, and owner distributions are $0. The IRS reasonable-compensation standard looks to what like enterprises pay for like services under like circumstances. The 2025 Form 990 instructions add a practical safe-harbor concept: for organizations with gross receipts below $1 million, compensation data from three comparable organizations in similar communities can be appropriate evidence. That means a founder should not set pay by simply taking whatever is left over at year-end.
Keep the labels separate. Revenue is the top line; contribution is revenue after direct non-labor program costs. Operating profit or EBITDA measures operating performance, while accounting surplus can differ because restrictions and accounting treatment matter. Founder salary is payroll for services; an owner draw or distribution is $0 for a 501(c)(3). Cash available for compensation is unrestricted cash after program obligations, staff payroll, debt service, and board reserves. The calculator excludes founder pay from labor cost so its fixed formula can show residual compensation capacity. Once the board approves salary, bookkeeping puts it in payroll; never count the same $78,000 again as a distribution. For payroll context, BLS June 2025 employer-cost data show benefits were 29.8% of private-industry compensation costs; this article's nonprofit payroll is still a planning assumption.
Compare low, base, and high founder-compensation scenarios
The three cases change revenue, contribution margin, hired staffing, overhead, fundraising spend, debt service, reserve policy, and target pay together. They are not predictions. The low case assumes $540,000 annual usable revenue and a leaner team; the base case uses $780,000; the high case reaches $1.08 million but also carries more staff, fundraising, overhead, and a 20% reinvestment reserve. The modeled annual founder compensation capacity after reserves is exactly $14,580, $78,540, and $141,600.
Founder compensation scenarios
Low, base, and high cases reconcile to the calculator and show how funding quality, cost structure, and reserves change compensation capacity.
Nonprofit Organization low, base, and high founder-compensation planning cases
Scenario factor
Low CaseConservative
Base CasePlanning
High CaseStretch
Launch modelFunding posture
Lean local charity with part-time founder compensation and cautious hiring.
Stabilized small public charity with one paid founder-executive and mixed funding.
Larger small charity with stronger recurring giving and grant capacity plus added staff.
Typical setupRevenue and margin
$45,000 monthly revenue
65% contribution margin
10% reinvestment reserve
$65,000 monthly revenue
68% contribution margin
15% reinvestment reserve
$90,000 monthly revenue
70% contribution margin
20% reinvestment reserve
Cost driversMonthly cash load
$18,000 hired payroll
$6,500 fixed overhead
$3,000 fundraising
$400 debt service
$24,500 hired payroll
$7,500 fixed overhead
$4,000 fundraising
$500 debt service
$33,000 hired payroll
$9,000 fixed overhead
$5,500 fundraising
$750 debt service
Owner income rangeAfter modeled reserves
$14,580
Annual founder compensation capacity after modeled reserves.
$78,540
Annual founder compensation capacity after modeled reserves.
$141,600
Annual founder compensation capacity after modeled reserves.
Best fitUse case
Stress-test a slow fundraising ramp before committing to full-time founder compensation.
Plan a stable small charity with a market-aware executive salary and growing reserves.
Test a stronger funding base that can support a larger team and higher board-approved executive compensation.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Six nonprofit income drivers that determine founder compensation capacity
These six drivers are the same levers summarized above, expanded into operating decisions. The point is not to maximize founder pay at the expense of mission. It is to know what level of compensation the organization can support without underfunding programs, shortchanging staff, ignoring restrictions, or draining cash reserves.
1. Usable funding mix
Separate raised dollars from spendable dollars
The base case needs $65,000 a month of usable operating revenue. A practical funding mix could combine recurring individual giving, unrestricted foundation support, corporate sponsorship, government contracts, and program-service fees. The national pool is broad, but 2025 Giving USA data show that giving sources behave differently: individuals supplied $394.2 billion nationally, foundations $117.15 billion, bequests $62.19 billion, and corporations $43.67 billion. Your local mix will be much smaller and more concentrated.
Here's the quick math: if $15,000 of a $65,000 monthly inflow is restricted to direct program supplies that are already fully funded elsewhere, the bank balance may rise while general operating capacity does not. Founder compensation should be supported by unrestricted or appropriately budgeted funding, not by counting every deposit as flexible cash.
Track unrestricted coverage
Measure how much of the next 12 months of payroll and overhead is covered by unrestricted cash and committed grants whose budgets actually allow those costs.
Unrestricted revenue as a share of total revenue.
Largest donor or grant as a share of usable funding.
Committed funding versus pipeline funding.
Months of payroll covered by unrestricted cash.
Founder pay becomes safer when the salary is supported by recurring, flexible funding rather than one large, temporary award.
2. Contribution margin after direct program costs
Protect the dollars that fund the organization itself
The model uses a 68% contribution margin after non-labor direct program costs. That means $65,000 of monthly revenue leaves $44,200 before payroll, fixed overhead, fundraising, debt service, reserves, and founder compensation. This is a planning assumption because direct-cost structures vary enormously between a scholarship fund, a food-relief organization, an arts nonprofit, and a policy institute.
A 1-point margin change at $780,000 annual revenue is worth $7,800 before reserves. If direct non-labor program cost rises from 32% to 35% while revenue stays flat, gross profit falls by $23,400 a year. That is nearly 30% of the base founder-compensation capacity. The answer is not automatically to cut mission spending; it is to price grants, contracts, and fundraising goals so direct delivery and shared infrastructure are both funded.
Track contribution by funding stream
Do not use one blended margin if different programs have different restrictions or reimbursement rules.
Direct non-labor cost per service unit.
Contribution dollars by grant or program.
Payment and fundraising-platform fees.
Unfunded indirect cost by contract.
When the contribution margin slips, the loss reaches payroll and founder compensation before it shows up as an obvious cash crisis.
3. Staffing load before founder pay
Hire only when recurring funding can carry the role
Base hired payroll is $24,500 a month, or $294,000 a year, before founder compensation. The high case increases that to $33,000 a month as revenue rises to $1.08 million. That step-up is deliberate: a high-revenue charity normally needs more program, finance, development, or operations capacity. Using the same staff cost in every scenario would overstate upside.
Wages are only part of payroll. In June 2025, BLS employer-cost data showed private-industry wages and salaries were 70.2% of compensation and benefits 29.8%. A nonprofit's actual ratio can differ materially, but the lesson is useful: a $50,000 salary is not a $50,000 cash cost once payroll taxes, health coverage, leave, and retirement are included.
Track fully loaded payroll
Keep founder hours visible even while the calculator excludes founder pay from labor cost. That prevents the organization from treating executive work as free.
Total payroll as a share of usable revenue.
Fully loaded cost per full-time equivalent.
Vacancy savings versus program backlogs.
Founder hours that would require a replacement hire.
If hiring a $60,000 employee really costs closer to $75,000-$85,000 after burden, the funding plan should cover the full amount before the board increases executive compensation.
4. Donor retention and acquisition efficiency
Replace fewer donors before chasing more volume
The 2025 Fundraising Effectiveness Project reported 43.3% overall donor retention. Use that as a sector context point, not a guarantee for one organization. If a nonprofit begins with 1,000 donors and behaves exactly like that aggregate rate, roughly 433 donors repeat and 567 must be replaced just to keep donor count flat. That replacement burden consumes fundraising time and cash.
In the base model, fundraising and marketing cost is $4,000 a month. If retention improves enough to avoid replacing 100 donors and the all-in acquisition cost averages a planning assumption of $80 per new donor, that could avoid roughly $8,000 of acquisition spend. Whether that money supports more program delivery, staff capacity, or compensation is a board decision, but the cash effect is real.
Track cohort economics
Average gift alone can hide whether revenue comes from loyal repeat donors or expensive one-time acquisition.
First-year and repeat-donor retention.
Cost to acquire a new donor.
Average annual gift by donor cohort.
Recurring-gift cancellation rate.
Founder compensation is more defensible when the organization can show repeatable fundraising economics rather than one unusually strong campaign.
5. Reserve discipline and cash timing
Protect payroll before increasing compensation
The base calculator retains 15% of positive operating surplus, which equals $1,155 a month at the modeled run rate. That is only one contribution to liquidity, not a complete reserve policy. The National Council of Nonprofits notes that nonprofits are often advised to keep three to six months of operating funds on hand when possible, while also emphasizing that the right amount depends on the organization.
At base operating costs of $36,500 a month before founder pay and direct program costs already embedded in gross margin, three months of those operating costs alone is $109,500. If grants reimburse after expenses are incurred, the working-capital need can be higher. A board that pays an extra $20,000 of compensation while carrying only a few weeks of unrestricted cash may create payroll risk even if the annual budget still shows surplus.
Track unrestricted liquidity
A 13-week cash forecast is more useful for compensation decisions than a year-end surplus percentage.
Months of unrestricted cash on hand.
Largest expected grant-payment delay.
Next 13 weeks of payroll and vendor obligations.
Board-designated reserve floor.
Compensation increases should be tested against the cash low point, not the average month.
6. Compensation governance and compliance
Prove the salary is reasonable before paying it
The financial model can show capacity, but the board must still establish the compensation amount. The 2025 Form 990 instructions describe a rebuttable presumption process built around approval by a conflict-free authorized body, appropriate comparability data, and contemporaneous documentation. For organizations with gross receipts below $1 million, the instructions say data from three comparable organizations in the same or similar communities can be appropriate.
Startup compliance also has cash costs. The IRS currently lists a $600 Form 1023 user fee and a $275 Form 1023-EZ fee, before legal, accounting, state registration, insurance, and fundraising-registration costs. Those fees are small relative to a $780,000 budget, but they illustrate the larger point: compliance is part of operating capacity, and compensation comes after the organization funds that capacity.
Track the compensation file
Make the governance evidence as concrete as the budget so the salary is defensible to the board, donors, auditors, and regulators.
Three or more relevant compensation comparables.
Board minutes documenting the decision.
Founder job description and actual duties.
Total compensation including benefits and bonuses.
The safest founder income is a market-supported salary the nonprofit can pay from durable cash flow while still meeting mission and reserve obligations.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Nonprofit Organization Bundle
Choosing a selection results in a full page refresh.