How Much Profit Can the Owner Keep from a Cigar Lounge?
Cigar Lounge Bundle
An owner-operated U.S. cigar lounge can realistically model about $102,168 a year in owner cash in a stabilized base case, with a wider planning range of roughly $30,240 to $210,444 across low and high scenarios. The base case here assumes $95,000 in average monthly revenue, a 52% gross margin after cigar inventory, accessories, payment processing, and other non-labor direct costs, $17,000 of employee payroll before owner pay, $12,500 of fixed overhead, $2,500 of marketing, and $4,500 of debt service. The $102,168 figure is after a modeled 24% tax reserve and 10% reinvestment reserve. It is not guaranteed salary, GAAP net income, EBITDA, or a promised distribution. This article models a premium-cigar retail lounge with a walk-in humidor, memberships, accessories, and roughly 30 to 40 lounge seats; the base case excludes alcohol sales and assumes the owner personally covers the general-manager, buying, and community-host role.
Owner income$102KNet margin9%Revenue for target pay$1.12MBusiness difficultyHard
What does a realistic cigar lounge owner-income model assume?
The base case is built from operating units, not a national revenue average: 70 retail transactions per day across 26 days at a $42 basket produce about $76,440, plus $8,000 of recurring memberships and $10,560 from accessories, boxes, events, and other non-alcohol sales. That totals $95,000 per month. The basket and membership mix are planning assumptions for a premium tobacconist, not published national averages.
A current cigar wholesaler's pricing guidance places blended cigar retail around 45% to 55% gross margin. The model uses 52% after merchandise, card processing, and other non-labor direct costs, helped by memberships and accessories; payroll stays separate. 2025 BLS retail wage data show medians near $17.01 per hour for salespersons and $23.18 for first-line supervisors. The $17,000 labor input covers roughly 160 to 170 staff hours per week plus payroll burden while the owner performs the general-manager role.
Operating break-even is lower than owner-pay break-even. With $36,500 of monthly labor, overhead, marketing, and debt service, a 52% gross margin needs about $70,192 of monthly revenue just to reach zero profit before reserves. To support an $8,000 monthly owner-pay target after a 24% tax reserve and 10% reinvestment reserve, the calculator needs $93,502 per month, or $1,122,024 annualized. That distinction matters: a lounge can be technically profitable and still not generate enough safe cash for the owner.
Owner income calculator
Estimate monthly and annual owner cash from cigar-lounge sales, margin, staffing, overhead, debt, reserves, and your pay target.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Traffic × basket
+$10.9K sales/mo
Ten more daily $42 transactions across 26 days add about $10,920 of monthly sales before added labor or inventory needs.
2
Gross margin
1 point = $950/mo
At $95,000 of sales, one gross-margin point changes monthly gross profit by $950 before overhead and reserves.
3
Membership base
$8K recurring/mo
The base plan uses 80 members at an average $100 monthly equivalent, reducing reliance on walk-in traffic.
4
Owner labor
≈$36K annual swing
Adding about $4,600 monthly for manager coverage can reduce after-reserve owner cash by roughly $36,000 a year if sales do not rise.
5
Location load
$70.2K break-even
Base fixed cash costs and payroll require about $70,192 of monthly revenue before owner reserves or owner take-home begin.
6
Inventory + debt
$4.5K debt/mo
Inventory tied up for weeks or months plus loan payments can make accounting profit unavailable for distribution.
Want to test cigar traffic, inventory, and owner cash in a full forecast?
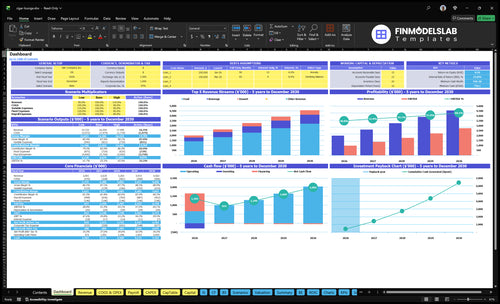
The Cigar Lounge Five-Year Financial Model Template includes a dashboard that can help you pressure-test the same relationships used here: revenue streams, cigar and accessory cost of goods, payroll, operating expenses, cash runway, debt, and scenario changes. The screenshot is most useful when you replace headline sales guesses with your own transactions per day, membership count, gross margin, inventory purchases, staffing hours, and financing terms.
Compare low, base, and high sales cases.
See how inventory and payroll affect cash flow.
Test break-even, debt service, and runway before owner distributions.
How much revenue does a cigar lounge need to pay the owner $96,000 a year?
Roughly $1.12 million of annualized revenue supports the $8,000 monthly owner-pay target; the $1.14 million base plan produces $102,168 after reserves. A 2025 survey of 65 U.S. cigar retailers representing 126 shops found 46.2% reported higher sales, 92.2% had raised prices, and 81.3% operated a lounge, according to the Cigar Insider retailer survey. That shows an active but price-sensitive market, not a national revenue average.
The base revenue equation is 70 daily transactions × $42 × 26 days = $76,440, plus $8,000 of memberships and $10,560 of other sales. A National Academies review found premium-cigar users often buy in cigar bars or specialty shops and that online purchases show seasonality. That is an adjacent demand proxy, not a lounge traffic benchmark, so local foot traffic and retention still decide the plan.
Build revenue from daily units
Track transactions per open day, not monthly sales alone.
Separate walk-in cigar sales from recurring memberships.
Measure cigar, box, accessory, and event basket sizes separately.
Use 26 operating days only if your actual schedule supports it.
What the target hides
$70,192 monthly sales covers modeled operating costs before reserves.
$93,502 monthly sales is needed for the $8,000 owner target after reserves.
At $95,000 monthly sales, the owner-pay cushion is only $514.
A few weak weeks can remove the distribution even if the year still shows a profit.
Can a cigar lounge be profitable without the owner working the floor?
Yes, but a manager must be paid from added gross profit. The base case is owner-operated: $17,000 monthly labor covers non-owner staff while the owner manages, buys, and sells. Using 2025 BLS retail wage benchmarks, full-time supervisor coverage plus payroll burden can add about $4,600 per month. At unchanged base sales, that would reduce after-reserve owner cash by about $36,432 per year.
If the business is an S corporation and the owner works in it, the IRS requires reasonable compensation before non-wage distributions. The calculator does not choose the W-2 salary/distribution split; it keeps owner pay out of labor so those dollars are not counted twice. Entity structure and payroll treatment still require tax advice.
Owner-operated economics
The owner absorbs the manager and buyer role.
Employee labor stays at $17,000 in the base month.
Owner cash is the residual after operating costs and reserves.
Time worked should still be compared with a market-rate management wage.
Manager-run economics
Add manager payroll before calling the owner income passive.
At base sales, a $4,600 monthly manager layer materially compresses distributions.
A hired manager should create capacity, retention, or hours that recover the cost.
Do not call free owner labor profit.
How do tobacco taxes and smoking rules change cigar lounge income?
They can change margin and whether indoor lounge seating is legal. The CDC's 2024 data show cigar tax structures vary sharply: Florida and Pennsylvania had no state cigar tax in that table, while many states used per-unit or percentage taxes. The CDC excise-tax fact sheet is why the 52% margin must be rebuilt for the exact state and city.
Indoor smoking rules vary too. The CDC reported 28 states with 100% smokefree laws covering bars, restaurants, and worksites as of June 30, 2024, while exemptions and local ordinances can differ; see the CDC smokefree guidance. FDA rules also limit tobacco sales to customers 21 or older, call for ID checks under 30, and prohibit free cigar samples; see the FDA retailer page.
Underwrite the address, not the concept
Rebuild cigar cost after state and local tobacco taxes.
Confirm indoor-smoking eligibility before committing to lounge rent.
Price ventilation, HVAC runtime, and cleaning into fixed overhead.
Make the landlord approve humidor and smoking use in writing.
Compliance has revenue consequences
Age verification and staff training protect the license to sell.
No-free-sample rules affect event and promotion design.
Local restrictions can reduce usable lounge capacity.
Higher tobacco tax can force a price increase or compress margin.
Key Takeaways
The base case generates $102,168 of annual owner cash after modeled reserves on $1.14 million of annual sales.
Operating break-even is about $70,192 per month, but an $8,000 owner-pay target requires about $93,502 per month.
The model is owner-operated; adding a manager without added sales can cut owner cash by roughly $36,000 a year after reserves.
Gross margin, state tobacco tax, legal smoking eligibility, inventory turns, and debt service must be rebuilt for the exact location before any distribution is treated as safe.
How should salary, distributions, and safe owner cash be separated?
Revenue is not income. At $95,000 of monthly sales, the 52% gross margin leaves $49,400. After $17,000 labor, $12,500 fixed overhead, $2,500 marketing, and $4,500 debt service, profit before reserves is $12,900. The model then holds $3,096 for tax and $1,290 for reinvestment, leaving $8,514 of owner cash. That residual is not automatically a tax-free draw.
If the owner is a working S-corporation shareholder, IRS reasonable-compensation rules mean a wage cannot simply be skipped in favor of distributions. A sole proprietor or partnership uses different mechanics. The model therefore avoids claiming that $102,168 is a "salary." It is after-reserve owner cash under the operating assumptions, and the legal split among wages, guaranteed payments, draws, or distributions depends on entity type and tax advice.
TTB states that federal excise tax on large cigars is 52.75% of the manufacturer/importer sale price, capped at $0.4026 per cigar; see the TTB tax table. At retail, landed wholesale cost, applicable state/local tobacco tax, freight, shrink, and processing belong in direct cost. Fund the next inventory buy, payroll, taxes, repairs, and debt before distributing the remainder.
Do not mix profit definitions
Revenue is customer sales before costs.
Gross profit is revenue after direct merchandise and transaction costs.
Accounting profit can include depreciation; EBITDA excludes interest, taxes, depreciation, and amortization. Neither equals safe cash.
Owner cash is what remains after operating costs and protected reserves.
Pay these before a draw
Next payroll and payroll taxes.
Vendor invoices and replenishment orders.
Rent, utilities, insurance, and debt service.
Tax reserve, repair reserve, and working-capital buffer.
What do low, base, and high cigar lounge income cases look like?
The scenarios change revenue and costs together. Low keeps sticky fixed costs; High adds labor, marketing, and overhead. The PCA startup guide identifies real estate, inventory, a humidor, furnishings, branding, and legal expenses as major opening uses of cash and notes online price competition. A lounge therefore needs both retail margin and enough capital to carry the customer experience.
Low produces $30,240 of annual owner income after reserves at $70,000 monthly sales. Base reaches $102,168. High reaches $210,444 only after payroll rises to $23,000, fixed overhead to $14,000, and marketing to $4,000. These are planning cases, not guaranteed earnings.
Low, base, and high cases
Three coherent owner-operated cigar-lounge presets using the same calculator formulas and reserve logic.
Cigar Lounge planning scenarios and owner income after modeled reserves.
Planning area
Low CaseConservative
Base CasePlanning
High CaseUpside
Launch modelMonthly operating preset
$70,000 monthly revenue
49% gross margin
Owner-operated
$95,000 monthly revenue
52% gross margin
Owner-operated
$135,000 monthly revenue
55% gross margin
Owner-operated with added staff
Typical setupTraffic and recurring revenue
48 daily transactions at about $38
Smaller membership base
Lean event calendar
70 daily transactions at $42
80 members at $100 monthly equivalent
Balanced accessories and events
90 daily transactions at $48
Deeper membership base
Stronger boxes, accessories, and events
Cost driversMonthly cash stack
$13,000 labor
$11,500 fixed overhead
$1,800 marketing
$4,500 debt service
$17,000 labor
$12,500 fixed overhead
$2,500 marketing
$4,500 debt service
$23,000 labor
$14,000 fixed overhead
$4,000 marketing
$4,500 debt service
Owner income rangeAfter modeled tax and reinvestment reserves
$30,240
$102,168
$210,444
Best fitHow to use the case
Stress-test a slow ramp, smaller membership base, or weak local traffic while fixed costs remain sticky.
Use as the stabilized owner-operated planning case when local traffic, lounge legality, and inventory turns are proven.
Test upside only when higher volume can support extra payroll, inventory, marketing, and overhead without eroding service.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six biggest cigar lounge income drivers?
The strongest lever is productive traffic: more transactions and a healthier basket spread fixed costs without requiring a second lease. But the gain only survives if cigar margin, membership retention, labor coverage, local tax and occupancy economics, and inventory financing stay under control. The 2025 retailer survey is a useful reminder that demand remains active while pricing pressure is real: 95.2% of respondents had seen MSRP increases and 75% said inflation changed customer buying habits.
1. Daily transactions and average basket
Fill the lounge and the register at the same time
The base needs 70 daily transactions at a $42 basket for 26 days, or $76,440 of core retail sales. Ten extra $42 transactions each day add $10,920 monthly sales and about $5,678 of gross profit at a 52% margin before added payroll. If discounting cuts the basket to $36, the same ten transactions add only $9,360, so traffic can rise while owner cash weakens.
The National Academies evidence cited above also shows meaningful specialty-store and online competition. The lounge therefore has to sell curation, convenience, events, and membership—not only price.
Track productive traffic
Separate customer count from basket quality so promotions do not hide weak economics.
Transactions per open day and by daypart.
Average cigar-only basket versus box and accessory basket.
New versus repeat buyers.
Gross profit per transaction, not only sales per transaction.
Owner-income connection: sales matter only when they add gross profit after direct cost.
2. Cigar, accessory, and membership gross margin
Protect margin before chasing premium price points
At 52% gross margin, $95,000 of revenue creates $49,400 of gross profit. Supplier guidance places blended cigar retail around 45% to 55%; actual margin also reflects tax, freight, discounting, shrink, card fees, accessories, and memberships.
One margin point on $95,000 is $950 monthly profit before reserves. After the base 34% combined reserve, that is about $627 less owner cash each month, or $7,524 a year. A two-point leak is roughly a $15,000 annual owner-income hit.
Watch margin by category
A single storewide percentage can hide a profitable membership program and a weak humidor.
Gross margin by cigar, box, accessory, and membership.
Discount dollars as a percent of cigar sales.
Shrink and damaged inventory at cost.
Card fees and state tobacco tax inside the same direct-cost definition.
Owner-income connection: margin leakage reaches owner cash quickly because rent and debt stay fixed.
3. Membership count and lounge utilization
Turn seats into recurring revenue without overselling capacity
The base assumes 80 members at a $100 monthly equivalent, or $8,000 of recurring revenue. That is a planning assumption. Membership can carry high contribution, but overselling access creates crowding or added staffing.
Ten net new members at $100 add $1,000 monthly revenue. At an assumed 85% contribution before payroll, $850 remains; after the base reserves, about $561 could reach owner cash if capacity and labor stay unchanged. Track recurring gross profit per usable seat, not member count alone.
Track recurring economics
Membership should make monthly cash more predictable without displacing profitable walk-in customers.
Active members and net adds each month.
Membership revenue per seat.
Member visit frequency and peak-hour occupancy.
Member cigar and accessory spend beyond dues.
Owner-income connection: recurring dues can reduce the volatility that forces skipped distributions.
4. Employee coverage and the owner's operating role
Price the owner's labor before calling the profit passive
The $17,000 base labor budget assumes the owner is general manager and buyer. Adding about $4,600 monthly manager payroll cuts profit before reserves from $12,900 to about $8,300 at unchanged sales, reducing modeled owner cash by about $36,432 a year.
The hire works financially only if it creates capacity or control. At a 52% margin, roughly $8,850 of extra monthly sales replaces a $4,600 payroll layer before reserve effects.
Measure labor productivity
Schedule to transaction and lounge demand, not to a fixed habit.
Labor cost as a percent of revenue.
Gross profit per paid labor hour.
Owner hours worked by manager, buyer, and sales function.
Revenue and retention lift from added manager coverage.
Owner-income connection: unpriced owner labor is a job plus business return, not passive income.
5. State tobacco tax, rent, and legal lounge capacity
Choose a location where the margin can legally exist
State cigar tax, smoking eligibility, HVAC, and lease restrictions can change both capacity and margin, so the $12,500 fixed-overhead base cannot be copied city to city.
At $36,500 of monthly operating costs and 52% gross margin, break-even is about $70,192. Add $3,000 of overhead and break-even rises to about $75,962; if margin also falls to 49%, it rises to about $80,612. A premium address must add more gross profit than fixed cost.
Underwrite the lease with tax included
The financial model should use the exact legal and tax environment of the proposed address.
Landed cigar cost after applicable tobacco tax.
Rent, CAM, utilities, ventilation, and insurance per month.
Permitted indoor smoking capacity and operating hours.
Break-even revenue at the signed lease economics.
Owner-income connection: the lease must support recurring gross profit without permanently suppressing owner pay.
6. Inventory turns, debt service, and reserve discipline
Protect cash that accounting profit has already spent
Cigar inventory ties up cash before the owner can distribute it. The supplier guide above shows premium inventory can turn over in roughly 45 to 90 days, with slower boutique tiers. Against $45,600 of modeled monthly direct cost, one to two months of stock can consume substantial working capital.
The base also carries $4,500 monthly debt service. Each extra $1,000 of debt cuts modeled owner cash by about $660 per month, or $7,920 a year, after base reserves. SBA 7(a) terms can extend to 10 years for many non-real-estate uses, but lender and business eligibility still apply.
Track cash before distributions
Inventory, debt, and reserves should be managed as a single owner-cash system.
Inventory at cost and days on hand by brand.
Open-to-buy dollars versus next-month cash needs.
Debt-service coverage before owner distributions.
Tax reserve, repair reserve, and minimum operating cash.
Owner-income connection: safe distribution is cash left after inventory, payroll, debt, taxes, and cushion are funded.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.