A U.S. owner-operated dance school can realistically produce about $64,000 a year of owner income in the base planning case here, with about $456,000 in annual revenue. Across a slower low case and a fuller high case, modeled owner income runs from roughly $6,000 to $112,000 after debt service plus modeled tax and reinvestment reserves. This is a one-location suburban studio with a working owner, hired instructors, recurring tuition, and some camps, workshops, and performance-related fees. The biggest constraints are class fill, realized tuition per student, payroll, fixed overhead, marketing, and seasonal cash swings. The figure is not revenue, EBITDA, a guaranteed salary, or automatically distributable cash; it excludes the owner’s actual personal tax return and assumes no separate owner wage is buried in payroll.
Owner income$64KNet margin14%Revenue for target pay$498KBusiness difficultyModerate
What can a dance school owner take home each month?
The base case produces $5,343 per month after modeled reserves from $38,000 of monthly revenue. That level is consistent with a school whose average student value lands between one-class and multi-class tuition tiers published by current U.S. studios: for example, ROOTS Academy’s 2026–27 tuition lists $110 for one monthly class and $180 for two, while Natomas Dance & Fitness lists $90 for one class and $165 for two. Those are local examples, not national averages, so the calculator uses them only to keep the planning range grounded.
Owner income calculator
Estimate owner take-home and the revenue needed to support a target pay level.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives dance school owner income the most?
The strongest owner-income lever is not adding more class names to the schedule; it is filling the classes already committed. This model ranks six levers that change cash available to the owner after the studio pays direct costs, hired labor, occupancy, marketing, debt, and reserves. Published 2026–27 tuition examples range from $50–$110 for many single weekly classes and climb into the $155–$330 range for multiple classes at Legacy Performing Arts, which is why both seat fill and realized tuition per student matter.
1
Class fill
63%–83%
Filling scheduled seats spreads the same room and instructor commitment across more tuition accounts.
2
Realized tuition
$112–$145
Monthly revenue per active student rises with class mix, premium programs, and disciplined discounting.
3
Retention and acquisition
$125 CAC target
A base planning target of about $125 paid acquisition per new student works only when families stay for multiple billing cycles.
4
Instructor labor
$14K/mo
Base hired payroll must rise with schedule volume, but owner-taught hours keep early payroll from outrunning enrollment.
5
Studio overhead
$9.5K/mo
Lease, utilities, insurance, software, cleaning, licensing, and repairs create a fixed floor before owner cash exists.
6
Add-on contribution
$2K–$6K/mo
Camps, privates, workshops, and performance fees can lift cash, but only their margin after event costs counts.
Want to test tuition, staffing, and class-fill assumptions in a full forecast?
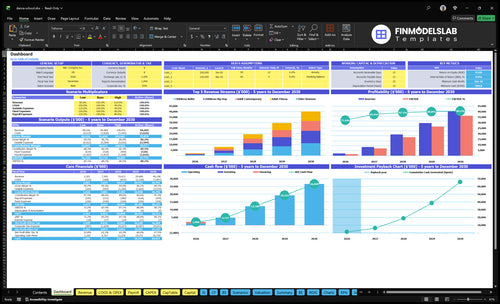
The Dance School Startup Financial Model Template shows a business-specific dashboard with revenue, profitability, cash flow, break-even, and scenario outputs. Use the screenshot to pressure-test enrollment, tuition, payroll, fixed studio costs, financing, and cash reserves rather than treating one owner-income number as a promise.
Can one dance school support a full-time owner?
Yes, but a one-location school usually has to support the owner as a working operator, not as a passive investor. In the base case, $456,000 of annual revenue yields $98,640 of annual profit before the modeled tax and reinvestment reserves, then $64,116 of owner cash after those reserves. That is economically different from a salary. If the business is taxed as an S corporation and the owner works in it, the IRS reasonable-compensation guidance says shareholder-employees must receive reasonable compensation for services before non-wage distributions.
Owner-operated base
Owner teaches selected classes and acts as director.
Hired payroll is $14,000 per month before owner pay.
Owner cash is the residual after operating costs and reserves.
Annual modeled owner income is $64,116, not $456,000 of sales.
Manager-run warning
Replacing owner teaching and management with hired coverage adds payroll.
The 2024 national median for self-enrichment teachers was $21.92 per hour.
Choreographers had a $26.73 median hourly wage in May 2024.
Passive owner distributions can shrink sharply unless revenue also rises.
For labor context, the U.S. Department of Labor-sponsored CareerOneStop wage table shows a 2024 national median of $21.92 per hour for self-enrichment teachers, with a wide $13.93 to $43.64 low-to-high range. The BLS dancers and choreographers profile reports a May 2024 median of $26.73 per hour for choreographers and notes that choreographers work in dance schools. A commercial studio often pays above a simple clock-hour rate to reflect prep, choreography, experience, and coverage, so the base labor budget intentionally sits above a bare median-wage calculation.
What monthly revenue supports a $90,000 owner-pay target?
In this model, about $41,530 of monthly revenue, or $498,360 annualized, supports a $7,500 monthly owner-pay target after the 25% tax reserve and 10% reinvestment reserve. The simpler operating break-even is lower: $27,500 of monthly operating costs divided by a 94% gross margin equals about $29,255 of monthly revenue before any owner take-home or reserves. That difference is why a studio can look profitable and still fail to fund the owner’s desired pay.
Base revenue build
About 275 active students.
About $125 realized monthly revenue per active student.
Roughly $3,600 per month normalized from camps, workshops, fees, and privates.
Total monthly revenue: about $38,000.
Target-pay bridge
Monthly revenue needed: $41,530.
Base case shortfall to target pay: $2,157 per month.
At the same cost structure, roughly $3,530 more monthly sales closes the gap.
Price increases help only if retention and class fill hold.
Current tuition pages show why a $125 realized monthly student value is plausible but location-sensitive. The Studio of Dance Arts lists $80 per month for one hour per week and $120 for two hours in its 2026–27 schedule, while ROOTS lists $110 for one class and $180 for two. The model therefore does not assume every student pays $125 for one class; it assumes a mix of one-class, multi-class, registration, and add-on revenue averaged across active accounts.
Key Takeaways
$456,000 of annual revenue is not owner income; the base modeled owner cash is $64,116 after reserves.
Operating break-even is about $29,255 per month, but a $90,000 owner-pay target needs about $41,530 per month.
Owner labor must be priced explicitly; hiring replacement teaching and management can absorb much of the residual profit.
Safe distributions come only after payroll, studio overhead, marketing, debt service, tax cash, and reinvestment reserves are funded.
How do seasonality, debt, and reserves change safe owner distributions?
They can make accounting profit materially larger than cash that is safe to take home. Dance tuition is commonly billed as equal monthly installments over a school-year season; for example, 620 Dance Centre’s tuition policy says annual tuition is divided into nine equal monthly payments. That makes September-through-spring collections more predictable, but summer enrollment, recital spending, costume timing, and new-season marketing can still create cash peaks and valleys.
What gets paid first
Direct processing and class-delivery costs.
Instructor and admin payroll.
Lease, utilities, insurance, software, cleaning, and licensing.
Marketing, debt service, tax cash, and reinvestment reserve.
What profit can hide
Credit-card fees can consume several percentage points of tuition.
Recital cash may be offset by venue, costume, staff, and production costs.
Loan principal reduces cash even though it is not an operating expense.
Owner draws can starve summer working capital if reserves are ignored.
For payment-cost context, Square’s U.S. pricing shows card-present rates around 2.6% plus $0.15 and online rates around 3.3% plus $0.30 on one plan, which supports using a several-point direct-cost allowance rather than pretending tuition has a 100% gross margin. Music is another real operating line: SESAC’s dance-school licensing page explains that its blanket license covers public performance of the songs it represents in a dance school.
The base debt-service assumption is $1,500 per month and should be replaced with actual lender terms. SBA 7(a) loans can have fixed or variable rates, and the SBA 7(a) terms page shows maximum variable-rate spreads that change with loan size. The tax reserve is also a cash-planning assumption, not a tax-rate claim. The IRS estimated-tax guidance notes that sole proprietors, partners, and S corporation shareholders generally use Form 1040-ES to estimate payments. An owner should set the actual reserve with a tax professional and entity-specific forecast.
How do low, base, and high dance school income cases compare?
The three cases below change revenue and costs together. The low case keeps a smaller schedule but still carries minimum rent, payroll, and debt; the high case adds instructors, marketing, and overhead rather than assuming $60,000 of monthly revenue appears with the base cost structure. Owner-income values are exactly the calculator outputs after each case’s modeled tax and reinvestment reserves.
Owner income scenarios
Compare a slower enrollment case, a working-owner base case, and a fuller schedule with higher supporting costs.
Low, base, and high dance school owner-income planning cases.
Scenario
Low CaseSlower fill
Base CaseWorking owner
High CaseFuller schedule
Launch modelDemand and owner-role posture
Smaller one-location schedule with slower enrollment and owner covering more teaching and administration.
One suburban location, active owner-director, several hired instructors, recurring group tuition and normalized add-ons.
Same one-location concept at stronger fill, more sections, more hired coverage, and higher acquisition and overhead spend.
Typical setupEnrollment and pricing mix
About 180 active students, roughly $112 realized monthly revenue per student, 63% scheduled-seat fill, plus small add-ons.
About 275 active students, roughly $125 realized monthly revenue per student, 70% scheduled-seat fill, plus about $3,600 monthly normalized add-ons.
About 375 active students, roughly $145 realized monthly revenue per student, 83% scheduled-seat fill, with more camps, privates, and workshops.
Cost driversMatching calculator inputs
$22,000 monthly revenue
93% gross margin
$9,000 labor; $8,000 overhead
$1,500 marketing; $1,200 debt
22% tax + 12% reinvestment reserve
$38,000 monthly revenue
94% gross margin
$14,000 labor; $9,500 overhead
$2,500 marketing; $1,500 debt
25% tax + 10% reinvestment reserve
$60,000 monthly revenue
95% gross margin
$23,000 labor; $12,500 overhead
$4,000 marketing; $2,000 debt
28% tax + 12% reinvestment reserve
Owner income rangeAfter modeled tax and reinvestment reserves
$6,024
Annual owner income after modeled reserves.
$64,116
Annual owner income after modeled reserves.
$111,600
Annual owner income after modeled reserves.
Best fitWhen to use the case
Stress-test a young studio, summer softness, or a schedule carrying too many lightly filled classes.
Use as the normal owner-operated planning case before deciding whether the owner can safely raise fixed pay.
Test a strong re-enrollment year with fuller rooms, higher realized tuition, and enough added payroll to protect service quality.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six income drivers should a dance school owner track every month?
The same six levers become operating KPIs here. They work together: price can hurt retention, overfilling can hurt quality, and payroll cuts can simply transfer too much work to the owner.
1. Class fill
Fill committed class seats before adding sections
Class fill is the clearest conversion of fixed studio capacity into revenue. The low, base, and high cases assume about 63%, 70%, and 83% scheduled-seat fill. In the base case, think of roughly 30 weekly sections with an average 14-seat cap: 420 weekly seat opportunities, with about 294 occupied seat-enrollments. The exact cap depends on room size, age, style, and safety, so 14 seats is a planning assumption rather than an industry rule.
Here’s the quick math: if one underfilled section has only 6 students paying an average $95 for that class, it produces about $570 of monthly tuition. At 12 students it produces about $1,140. If the instructor cost and room time are already committed, most of that $570 difference falls toward overhead coverage and owner profit, less processing and other direct costs. That is why merging thin sections often beats opening another time slot.
Track fill by section, not schoolwide averages
A healthy school can still hide weak economics in a few lightly filled hours. Review each section before every new scheduling cycle.
Filled seats divided by class cap.
Tuition revenue per scheduled studio hour.
Waitlists by age, style, and time slot.
Sections below the minimum viable enrollment.
ROOTS Academy publishes a minimum of 7 students per class in its current policy. That is one studio’s operating rule, not a universal benchmark, but it shows why owners should define their own minimum enrollment before the schedule is built.
2. Realized tuition per active student
Manage the mix, not just the posted price
The base model uses about $125 of realized monthly revenue per active student before normalized add-ons. That is deliberately between common one-class and multi-class price points. A posted price is not the same as realized revenue because siblings, multi-class discounts, scholarships, late joins, pay-in-full discounts, and premium programs all change what the school actually collects.
A $5 increase in realized monthly revenue across 275 active students adds $1,375 per month, or $16,500 per year before direct costs. At a 94% gross margin, about $15,510 of that reaches gross profit before extra labor or marketing. The decision should therefore be based on retention response. If a price increase causes enough families to drop, the studio can lose more filled seats than it gains in rate.
Watch revenue per student after discounts
Use a cohort report so the owner can separate price changes from student-mix changes.
Monthly tuition collected per active student.
Discount dollars as a percentage of list tuition.
Average classes per student.
Price-change churn in the next two billing cycles.
Current U.S. examples illustrate the range: Natomas lists $90 for one class and $165 for two, while Legacy lists $100 and $155 for comparable school-age tiers. Use local competitive checks before raising the model’s $125 base value.
3. Retention and customer acquisition
Make marketing pay back over several billing cycles
The base case budgets $2,500 a month for marketing. A practical planning target is about $125 of paid acquisition cost per new student, which would require roughly 20 net new paid enrollments from that spend. That $125 is a planning assumption, not a published dance-industry benchmark. Its usefulness comes from comparing it with lifetime gross profit, not from treating it as a universal target.
If a newly acquired student produces $125 of monthly realized tuition at a 94% gross margin, monthly gross profit before labor and overhead is about $118. The acquisition spend is therefore recovered in a little over one month at the gross-profit level, but only if the student stays and the school has room in an existing class. If the enrollment requires a new section and another instructor, payback is longer.
Measure re-enrollment before buying more leads
The least expensive lead is often the family that does not churn. Paid marketing should fill profitable seats, not replace preventable losses.
New paid enrollments by source.
Cash acquisition cost per enrolled student.
Three-, six-, and nine-month retention.
Referral share of new enrollments.
Use tuition billing cohorts to see whether September signups stay through spring and whether summer-camp families convert into recurring classes. Owner income improves when the same marketing dollar creates more months of contribution.
4. Instructor labor
Add paid teaching hours only when seat revenue supports them
Base hired labor is $14,000 per month, rising to $23,000 in the high case as class volume and administrative coverage increase. That step-up matters because dance-school payroll is semi-variable: the owner can trim some teaching hours when enrollment is weak, but a functioning schedule still needs qualified instructors, front-desk coverage, substitutions, and administrative time.
National wage data provide a floor for reasonableness, not a studio pay sheet. CareerOneStop reports a 2024 median of $21.92 per hour for self-enrichment teachers, while BLS reports $26.73 for choreographers. If the studio pays a teacher $35 per teaching hour and schedules 18 paid class hours each week, that is roughly $2,730 a month before payroll taxes, prep premiums, substitutions, or benefits. Several instructors plus admin coverage can therefore reach the model’s $14,000 quickly.
Track labor against class revenue
Payroll should be attached to the schedule so the owner can see which sections actually carry their staffing cost.
Instructor payroll as a percentage of tuition revenue.
Paid teaching hours per occupied seat.
Substitute and overtime cost.
Owner teaching hours that would need replacement.
Do not call owner-covered classes “free.” If the owner wants to step away later, the replacement wage is a real future expense. That is the bridge between active owner income and passive distributions.
5. Studio overhead
Underwrite the lease against realistic enrollment
The base case carries $9,500 per month of fixed overhead before hired labor, marketing, debt, or direct costs. A reasonable internal build might include roughly $5,500 of rent and CAM plus utilities, insurance, software, cleaning, music licensing, repairs, and administration. Those amounts are planning assumptions because U.S. commercial occupancy costs vary dramatically by city, property, room count, and lease structure.
At 275 active students, $9,500 of fixed overhead equals about $35 per student per month before payroll. At 180 students, an $8,000 low-case overhead load equals about $44 per student. That is the fixed-cost penalty of weak enrollment: even a smaller studio can become expensive per account when rooms are underused.
Measure occupancy cost per filled seat
Do not add a second room because the current schedule feels busy. Add it when the existing room is financially full during sellable hours.
Rent and CAM as a percentage of revenue.
Fixed overhead per active student.
Revenue per studio hour.
Repair and equipment reserve usage.
Keep music rights and other recurring compliance costs in the overhead map. SESAC specifically markets blanket public-performance licensing to dance schools, so the owner should verify which catalogs and rights the school actually uses rather than treating a consumer music subscription as business permission.
6. Add-on contribution
Count the margin on camps and performances, not the gross receipts
The model normalizes roughly $2,000 to $6,000 per month of non-core revenue across the year from camps, workshops, private lessons, registration, rentals, and performance-related charges. The actual cash is seasonal. A June intensive can create a large collection spike, while costume deposits or venue bills can consume much of recital revenue later.
Suppose a one-day workshop sells 40 spots at $45, generating $1,800. If guest teaching, studio labor, payment fees, and supplies cost $750, the contribution is $1,050. That $1,050 helps cover fixed overhead and owner income; the $1,800 headline does not. The same rule applies to costume handling and tickets: pass-through revenue is not high-margin revenue merely because it crosses the bank account.
Separate recurring tuition from event cash
Forecast add-ons by event date and cash margin so one strong recital month does not justify a permanently higher owner draw.
Gross and contribution margin by event.
Private-lesson revenue per instructor hour.
Camp conversion into recurring enrollment.
Deferred or prepaid tuition obligations.
Use recurring tuition to cover the recurring cost base, then let profitable add-ons improve reserves and owner distributions. That policy makes owner cash less dependent on one recital, camp, or enrollment rush.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.