Does Owner Income in a Dog Daycare Depend More on Volume or Margin?
Dog Daycare Bundle
For a stabilized U.S. standalone Dog Daycare where the owner works as the general manager, a defensible base planning case can support about $128,000 a year of owner income after a 25% tax reserve and a 10% reinvestment reserve, on about $780,000 of annual revenue. The same model produces roughly $38,000 in a weak case and $192,000 in a strong case. Base math uses $65,000 monthly sales, a 93% contribution margin after non-labor direct costs, $27,000 of employee payroll, $11,500 of fixed overhead, $2,500 of marketing, and $3,000 of debt service. The $128,000 is not a guaranteed salary or GAAP net income: it is residual owner cash after modeled reserves, before any final personal-tax true-up, owner-specific benefits, extraordinary repairs, or new capital contributions. If the owner stops covering management, scheduling, client intake, and daily floor leadership, a hired manager must be added to payroll and the safe distribution falls.
Owner income$128K/yrNet margin16%Revenue for target pay$766K/yrBusiness difficultyHard
What does the Dog Daycare owner-income math look like?
A commercial benchmark helps anchor price: Dogtopia's Dallas Park Lane location lists a $39 full-day rate, while recurring weekly plans reduce the effective rate to roughly $25 to $35 per day in that market, according to its published daycare pricing. The Base case therefore uses a roughly $36.50 realized daycare rate after membership discounts and adds a modest layer of baths and other services. Its 93% gross margin is deliberately calculator-compatible: it removes only non-labor direct costs such as merchant fees, cleaning consumables, treats, and small service supplies. Every employee wage is instead captured in the separate labor line.
Use the controls as a cash-planning bridge rather than an accounting statement. Owner pay is not included in labor. A manager-run version should add replacement management payroll before treating the remaining amount as passive owner income.
Owner income calculator
Adjust sales, margins, staffing, overhead, financing, and reserves to estimate owner take-home.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Which six levers move Dog Daycare owner take-home most?
APPA reported 71 million U.S. households owning a dog in 2025, while also noting value-conscious pet spending, in its 2026 State of the Industry release. That makes utilization, realized rate, labor productivity, retention, facility burden, and add-ons more useful owner-income levers than a broad pet-market headline.
1
Paid dog-days and utilization
64/day Base
More paid attendance spreads facility and management costs across more revenue, but only while staffing and safe capacity can absorb it.
2
Realized daycare rate
~$36.50/day
The effective rate after packages and discounts matters more than the posted drop-in price; small changes flow quickly into contribution profit.
3
Labor hours per dog-day
$27K/mo payroll
Staffing is the largest modeled cash operating cost. Overstaffing erodes distributions; understaffing can damage safety, service, and retention.
4
Recurring-plan retention and acquisition
70%+ recurring target
A planning target of 70% or more recurring dog-days reduces the amount of paid acquisition needed to refill the weekly schedule.
5
Facility fixed cost and capital structure
$11.5K/mo fixed
Rent, utilities, insurance, software, maintenance, and administration are due even when attendance is soft; debt service adds another fixed claim.
6
Add-on revenue per daycare visit
$4.3K/mo Base
Baths, nail trims, and related services lift revenue without requiring another full dog-day, provided added labor and supplies are measured.
Want to test the assumptions in a full forecast?
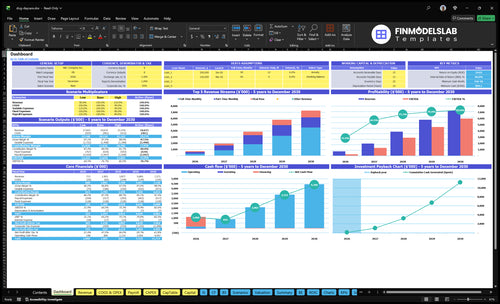
The Dog Daycare Five-Year Financial Model Template provides a business-specific model view for testing sales, operating costs, cash flow, and financing assumptions over time. The dashboard preview is useful for stress-testing the same owner-income questions used here: how much attendance is needed, whether payroll scales with revenue, when financing tightens cash, and how much cash should remain in the business rather than be distributed.
How many paid dog-days does a daycare need to support six-figure owner income?
In this Base case, about 64 paid dog-days per operating day, combined with approximately $4,300 a month of add-on sales, is enough to produce about $65,000 of monthly revenue and roughly $128,304 of annual owner income after modeled reserves. Dogtopia's Overland Park location lists a $41 full day and prepaid packages equivalent to about $36 to $39 per day in its current pricing schedule.
Here's the quick math. Sixty-four paid dog-days across 26 operating days at a $36.50 realized rate produces about $60,736 of monthly daycare sales. Add roughly $4,300 from baths, nail trims, or similar services and revenue is near the $65,000 model. With the Base contribution margin, labor, overhead, marketing, and debt, operating break-even before owner income and reserves is about $47,300 per month. The calculator's higher $63,854 monthly target is what supports a $10,000 owner-pay target after the 25% tax and 10% reinvestment reserves.
Attendance math to watch
Paid dog-days, not enrolled dogs, determine realized volume.
Track utilization by weekday; a full Tuesday cannot subsidize an empty Friday forever.
Separate package discounts from the posted drop-in rate when forecasting sales.
What the revenue target hides
A higher dog count may require another attendant before it increases owner cash.
Discounted recurring plans improve schedule visibility but can lower the realized rate.
Peak-day capacity is useful only if off-peak attendance and staffing are managed too.
How does staffing change what the owner can actually distribute?
Staffing is the most consequential cost line after demand because a daycare sells supervised time in a physical facility. The U.S. Bureau of Labor Statistics reported a May 2024 median annual wage of $33,470 for animal caretakers and projects faster-than-average growth for animal care and service workers in its occupational outlook. Actual daycare payroll will vary with local wages, shift design, benefits, payroll taxes, training, cleaning coverage, and whether front-desk or management roles are separate.
The Base model carries $27,000 of monthly employee payroll, or $324,000 annually, before any owner pay. The owner is assumed to cover general management. That distinction is essential: if an absentee owner hires a manager, the manager's loaded payroll belongs in labor cost before any distribution is calculated. A planning allowance of $55,000 to $70,000 a year for replacement management would reduce distributable cash substantially unless revenue or pricing rises at the same time; that range is an explicit planning assumption, not a national manager-wage benchmark.
Owner-operated case
Owner covers manager duties, intake decisions, staff coordination, and scheduling.
Employee payroll stays at $27,000 per month in the Base case.
The owner-income output mixes pay for labor with residual ownership profit.
Manager-run case
Add the hired manager's full cash payroll burden to labor cost.
Do not call the remaining distribution a salary unless the entity actually pays one.
Compare passive distributions only after replacement management is fully funded.
What must be paid before Dog Daycare cash is actually safe to take?
Revenue is not owner income, and accounting profit is not automatically distributable cash. In the Base month, $65,000 of sales becomes $60,450 after modeled non-labor direct costs. Employee payroll, fixed overhead, marketing, and debt service consume $44,000, leaving $16,450 before owner reserves. A 25% tax reserve and 10% reinvestment reserve remove $5,758, leaving $10,692 of modeled owner income. The IRS emphasizes that U.S. income tax is pay-as-you-go and that many self-employed people need estimated payments; its estimated-tax guidance is why a tax reserve should be treated as cash unavailable for casual draws.
Debt also matters even when an income statement looks healthy. SBA notes that 7(a) loan maturities are generally ten years or less unless longer-lived real estate or equipment supports a longer term, and that rates are negotiated within SBA maximums, in its 7(a) lender guidance. This article therefore models $3,000 monthly principal-and-interest service separately from overhead. Actual financing can be higher, lower, or zero. The owner should also retain cash for flooring, HVAC, gates, laundry, kennels, cleaning equipment, insurance deductibles, and demand dips instead of treating every profitable month as fully distributable.
Pay before the owner
Direct non-labor costs and every employee payroll obligation.
Facility overhead, marketing commitments, and principal-and-interest debt service.
Tax and reinvestment reserves sized for the actual entity, assets, and risk.
Keep the labels straight
Owner salary is compensation through payroll where applicable; a draw or distribution is not the same thing.
EBITDA or operating profit comes before some cash claims and should not be treated as spendable owner cash.
This model's owner income is residual cash after selected reserves, not a tax return definition of net income.
Key Takeaways
The Base owner-operated model reaches about $128,304 of annual owner income on $780,000 of annual sales after modeled tax and reinvestment reserves.
About $47,300 of monthly sales covers Base operating costs before owner income and reserves; about $63,854 supports the modeled $10,000 monthly target owner pay.
Payroll is separate from the 93% contribution margin, and owner management is not duplicated as an employee cost in the Base case.
Safe distributions come only after payroll, facility costs, marketing, debt service, taxes, and an asset-replacement or working-capital reserve are funded.
What do low, base, and high Dog Daycare owner-income cases look like?
The scenario spread is intentionally wide because dog owners can become value-sensitive and local competition can change both rate and attendance. APPA's recent dog-owner research describes spending pressure and greater attention to value in pet-care decisions; see its dog-owner spending update. The Low case assumes fewer paid dog-days and keeps minimum facility costs in place. The High case raises revenue but also adds payroll, overhead, marketing, debt service, and larger reserves. That prevents the unrealistic shortcut of increasing sales while freezing every cost.
Dog Daycare scenario planning
Three internally reconciled operating cases show how volume, staffing, fixed costs, financing, and reserves change owner income.
Low, Base, and High Dog Daycare owner-income planning cases.
Planning dimension
Low CaseConservative
Base CasePlanning case
High CaseStronger demand
Launch modelRevenue scale
$45,000 monthly revenue
$540,000 annual revenue
$65,000 monthly revenue
$780,000 annual revenue
$90,000 monthly revenue
$1,080,000 annual revenue
Typical setupOperating assumptions
92% contribution margin
$22,000 labor
$10,500 fixed overhead
93% contribution margin
$27,000 labor
$11,500 fixed overhead
94% contribution margin
$35,000 labor
$14,000 fixed overhead
Cost driversMarketing, debt, and reserves
$2,000 marketing + $2,500 debt
20% tax + 8% reinvestment reserves
$2,500 marketing + $3,000 debt
25% tax + 10% reinvestment reserves
$4,000 marketing + $4,000 debt
30% tax + 12% reinvestment reserves
Owner income rangeAfter modeled tax and reinvestment reserves
$38,016annual owner income
$128,304annual owner income
$192,096annual owner income
Best fitOperating interpretation
Early ramp or weak utilization
Discount-heavy attendance mix
Stabilized owner-operated facility
Repeat attendance supports schedule
Strong utilization
Added staff and support costs funded
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Six detailed Dog Daycare income drivers to track
The six levers below use the same Base model rather than introducing a second set of assumptions. They are ranked by how directly they change the amount left for the owner. The point is not to maximize any one KPI in isolation: occupancy without staffing discipline can create payroll pressure, high prices without retention can empty the schedule, and add-ons without labor tracking can look profitable while consuming staff time.
1. Paid dog-days and utilization
Protect the weekly attendance base before chasing capacity
The Base case needs about 64 paid dog-days per operating day. That is an operating assumption, not a national capacity benchmark; safe physical capacity depends on the building, room layout, dog grouping, local rules, staffing, and operating procedures. Market depth is large nationally—APPA reported 71 million dog-owning U.S. households in 2025—but a local daycare earns nothing from households it cannot convert into repeat attendance.
Here's the sensitivity: losing 10 paid dog-days per operating day at the modeled $36.50 realized rate removes about $9,490 of monthly sales before any offsetting labor savings. Because rent and much of the schedule remain fixed, the owner usually feels a disproportionate cash hit until shifts can be resized. Conversely, filling unused slots can be highly valuable when the incremental dogs fit inside an already-funded staffing block.
Track capacity by day and room
Manage a capacity calendar, not a single monthly dog count. Measure whether demand lands where the building and staff can safely serve it.
Paid dog-days by weekday and playgroup.
Booked capacity versus safe operational capacity.
Cancellation, no-show, and wait-list conversion rates.
Incremental payroll triggered by each attendance band.
2. Realized daycare rate
Price from the realized ticket, not the menu board
Commercial posted rates can differ sharply from the amount actually collected after memberships and packages. For an adjacent market check, Rover's San Diego in-home doggy-daycare marketplace showed an August 2026 average of $38.85 per day on its local daycare page; that is an in-home sitter proxy, not a commercial-facility benchmark, so it should widen rather than narrow the planning range. The Base facility assumption stays at about $36.50 realized daycare revenue per paid dog-day after recurring discounts.
A $2 increase in realized rate on 64 paid dogs over 26 operating days adds about $3,328 of monthly revenue. At a 93% contribution margin before labor, that is roughly $3,095 of contribution profit if attendance and staffing are unchanged.
Watch discount leakage
Build a realized-rate report from actual receipts divided by paid dog-days and compare it with the public rate card.
Realized revenue per paid dog-day.
Mix of drop-in, weekly, and monthly plans.
Discount dollars as a share of standard-rate billings.
Retention after any rate or package change.
3. Labor hours per dog-day
Scale the roster with attendance, not optimism
The Base model carries $27,000 of monthly employee payroll, and the High case deliberately rises to $35,000 when revenue reaches $90,000 per month. BLS's 2024 animal-caretaker median wage is only a wage anchor; a daycare must budget the full local cash burden around hourly pay, including payroll taxes, benefits if offered, overtime exposure, training, cleaning time, front-desk coverage, and supervisory layers.
If Base payroll rises by $3,000 per month while revenue stays flat, profit before reserves falls by $3,000. With the Base 35% combined reserve rate, modeled owner income falls by about $1,950 per month, or $23,400 a year. the useful KPI is paid dog-days per paid labor hour, monitored alongside incidents, cleaning quality, employee turnover, and customer retention.
Schedule to demand bands
Use historical check-in and checkout patterns to place labor where dog volume and client traffic actually occur.
Paid labor hours per paid dog-day.
Payroll dollars as a share of monthly revenue.
Overtime, call-out, and agency coverage costs.
Owner hours that would require replacement in an absentee model.
4. Recurring-plan retention and customer acquisition
Buy new demand only after measuring repeat use
Recurring plans can stabilize the week but often trade some price for predictability. Dogtopia Plymouth, for example, lists recurring and monthly plan structures alongside its daily options on its pricing page. The Base model uses a planning target of at least 70% of dog-days coming from recurring or reliably repeating customers; that 70% is not an industry statistic. It is a management target intended to reduce dependence on continual paid acquisition.
If $2,500 of monthly marketing produces 25 genuinely retained new clients, modeled acquisition cost is $100 each. If it produces only eight, the cost is $312.50.
Measure cohorts, not just leads
Tag the month each client first converts and then follow attendance, realized rate, and gross contribution over time.
Marketing cost per retained new client.
Thirty-, ninety-, and 180-day active-client retention.
Recurring dog-days as a share of total attendance.
Referral share and repeat visits per active dog.
5. Facility fixed cost and capital structure
Make the building earn its fixed monthly claim
The Base assumption allocates $11,500 a month to fixed overhead and another $3,000 to debt service. Those are planning values, not national benchmarks, because facility costs vary sharply by market and lease structure. What matters is that those claims remain when attendance dips. With Base costs, operating break-even before owner pay and reserves is about $47,312 of monthly revenue.
The target-pay threshold is higher: about $63,854 per month is required to leave a $10,000 monthly owner-pay target after the Base reserves. A new $5,000 fixed monthly obligation therefore should not be justified by vague growth expectations. It needs a clear path to enough incremental dog-days, price, add-ons, or labor efficiency to cover its own cash claim before distributions increase.
Stress-test every fixed commitment
Before signing a lease extension or financing an upgrade, rerun the model at low attendance and include the full cash payment.
Fixed overhead dollars per paid dog-day.
Debt-service coverage from operating cash before owner distributions.
Lease escalations and renewal dates.
Replacement reserve for flooring, HVAC, gates, laundry, and cleaning equipment.
6. Add-on revenue per daycare visit
Increase wallet share without hiding service labor
Dogtopia Overland Park lists spa services such as baths and nail trims, showing how commercial facilities can layer service revenue onto daycare traffic. For a separate adjacent pricing check, Rover's Manhattan in-home marketplace showed an August 2026 median daycare cost of $50 per day on its local page; that illustrates geographic price dispersion, not the price a commercial daycare should copy. The Base model therefore keeps add-ons modest at about $4,300 per month.
If the facility can add $3 of net new add-on revenue per paid dog-day across 64 dogs and 26 days, gross monthly sales rise by about $4,992 before the added service supplies and labor are considered. A bath that forces overtime or displaces a higher-margin service may create less owner cash than the register total suggests.
Track contribution per add-on
Measure each service against the same visit base so the team knows whether higher attachment truly improves cash.
Add-on revenue per paid dog-day.
Attach rate by bath, nail, and other service.
Direct supplies and incremental labor per service.
Contribution dollars generated per employee hour.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.