How Should an Owner Estimate Income from a Drive-In Movie Theater?
Drive-In Movie Theater Bundle
For a single-screen, owner-operated U.S. drive-in with roughly 300-car capacity, a practical stabilized owner-income range is about $70,000 to $90,000 a year, centered on the model's exact base output of $78,660 after modeled tax and reinvestment reserves. The base uses $864,000 of annual revenue, or $72,000 per month averaged across 12 months, from about 120 cars per operating night, 2.3 paid guests per car, an $11.75 blended ticket yield, and $8.25 of concession sales per guest. For context, Evergreen Drive-In lists $11 adult admission, while Cinemark reported $8.70 of U.S. concession revenue per patron in Q2 2026. Film settlement, concession product cost, seasonal payroll, fixed site overhead, marketing, debt, and repair reserves are the main constraints. The figure is residual owner cash, not guaranteed salary, GAAP net income, EBITDA, or a promised distribution, and it excludes site-specific taxes, unusual capital repairs, investor splits, and personal spending.
Owner income$79KNet margin9%Revenue for target pay$905KBusiness difficultyHard
What does a drive-in movie theater owner realistically take home?
Owner take-home is what remains after film rent, concession inputs, payroll, fixed site costs, debt, and reserves, not a percentage of ticket sales. The Georgetown Drive-In says most admission price goes back to the movie theaters and that concession sales are critical to staying open. In this base case, the owner works as general manager and site operator, so hired payroll excludes owner pay. Owner income is therefore the residual after operating costs and modeled reserves. Adding a separate salary on top would double-count owner compensation unless that salary is first reclassified into payroll.
Owner income calculator
Estimate owner cash from annualized monthly revenue, direct margin, operating costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Which six income drivers matter most for a drive-in?
Six connected levers drive owner cash: cars served, concession spending, direct-cost control, ticket yield, labor coverage, and fixed costs plus reserves. The model ranks them by cash impact and keeps film rent and snack supplies inside gross margin while modeling all payroll separately.
1
Car count and operating nights
120 cars/night
At 150 modeled nights, every extra car party spreads screen, land, utilities, and core staffing across more ticket and concession revenue.
2
Concession spend per patron
$8.25/guest
Food and beverage turn attendance into contribution margin; a small increase in spend per guest can add tens of thousands of annual gross profit.
3
Film and concession direct costs
62% gross margin
Film settlement and snack inputs determine how much sales remain before payroll and fixed costs, so contract and menu economics matter together.
4
Ticket price and party mix
$11.75/paid guest
The blended yield must account for adults, children, free young children, promotions, and any per-car fees instead of using only the posted adult price.
5
Labor and owner coverage
$14.5K/mo
Base payroll covers hired seasonal staff while the owner acts as general manager; adding management payroll without more sales sharply reduces residual owner cash.
6
Fixed costs, debt, and reserves
$18K/mo fixed + debt
Base fixed overhead plus debt is $18,000 per month before marketing and labor, while taxes and reinvestment are held back from positive profit.
Want to stress-test attendance, concession spend, and owner cash?
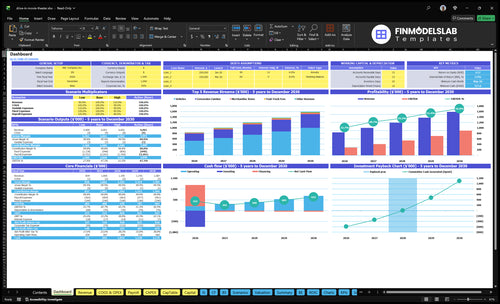
The Drive In Movie Theater Excel Financial Model for Startups includes a dashboard where you can replace this article's assumptions with your own ticket yield, cars per night, concession spend, payroll, debt, and cash-reserve inputs. The dashboard preview is useful for checking whether stronger attendance actually improves cash flow after costs, rather than simply increasing top-line sales.
How much revenue does one screen need to support owner pay?
Operating break-even before owner cash and reserves is about $56,452 per average month, or roughly $677,000 annualized, because $35,000 of monthly operating costs must be covered by a 62% gross margin. An $8,000 monthly owner-cash target after modeled reserves requires about $75,427 per average month, or $905,124 annualized. The 99W Drive-In describes a 275-to-300-car lot and a season from late April or early May through late October, supporting this article's roughly 300-car seasonal scope.
At 41,400 paid guests, a $1 higher blended ticket adds $41,400 of annual admissions revenue.
If the incremental film settlement is modeled at 52%, that $1 increase contributes about $19,900 before extra payment costs, labor, taxes, and reserves.
Adult price alone can overstate yield when children, free admissions, promotions, or community events are material.
Track realized admissions revenue per paid guest, not only the price printed on the sign.
Concession sensitivity
At 41,400 paid guests, each extra $1 of concession spend creates $41,400 of annual sales.
At a 20% modeled product-cost ratio, that can add about $33,100 of gross contribution before extra labor and payment processing.
Menu mix matters: high-waste or labor-heavy items can make revenue rise faster than cash contribution.
Track concession revenue per paid guest, transaction rate, product cost, waste, and outside-food permits together.
Key Takeaways
The base model turns $864,000 of annual revenue into $78,660 of owner income after the modeled tax and reinvestment reserves.
Operating break-even before owner cash is about $677,000 annualized, while a $96,000 annual owner-cash target needs about $905,000 of annualized revenue.
Concession spend is nearly as important as ticket yield: the base case produces about $341,550 of annual concession revenue.
Owner labor is not passive income; adding a $5,000 monthly manager cost can cut modeled annual owner income from $78,660 to about $37,860 if revenue is unchanged.
Can a drive-in run without the owner on-site?
Yes, but paid management can cut distributions sharply. Base hired payroll is $14,500 per average month for box office, concessions, lot, cleanup, and projection support, while the owner covers general management. BLS May 2025 national data reported mean hourly wages of $15.91 for ushers, lobby attendants, and ticket takers and $24.75 for motion picture projectionists. Adding a $5,000 monthly manager-and-burden stress test at unchanged revenue drops modeled annual owner income from $78,660 to about $37,860.
Owner-operated case
The owner covers general management, programming oversight, vendor coordination, closing, and financial control.
Hired payroll averages $14,500 per month across the year and rises in the high case to support more cars and concession volume.
The $78,660 owner-income output is the economic residual after modeled reserves, not a second salary layered on top.
Log owner hours separately so a high cash distribution is not mistaken for passive return on capital.
Manager-run stress test
Add $5,000 monthly payroll and the base profit-before-reserves falls from $9,640 to $4,640.
With the same 22% tax and 10% reinvestment reserves, owner cash becomes about $3,155 per month, or $37,860 annually.
Entity-specific wage and distribution treatment belongs in tax advice; the operating model should simply avoid counting the same owner labor twice.
What must be paid before an owner draw is safe?
Revenue is not owner cash. In the base month, $72,000 of sales becomes $44,640 of gross profit, then $9,640 of profit before reserves after $35,000 of labor, fixed overhead, marketing, and debt service. A $3,085 tax-and-reinvestment holdback leaves $6,555 of monthly owner cash. Loan principal still consumes cash even though it is not an EBITDA expense; SBA 7(a) guidance shows maturities depend on use of proceeds and can extend longer for qualifying real estate. Replace the model's $7,500 monthly debt assumption with actual financing terms.
Separate the profit labels
Revenue: $864,000 annualized sales before any costs.
Gross profit: $535,680 after modeled film, concession, processing, and other non-labor direct costs.
Profit before reserves: $115,680 after labor, fixed overhead, marketing, and debt-service cash in this planning calculator.
Owner cash: $78,660 after modeled tax and reinvestment reserves; GAAP net income and EBITDA can differ because of depreciation, interest classification, taxes, and capital spending.
Build the draw policy around cash
Base debt service is $90,000 per year and is already included once in operating costs.
Base tax plus reinvestment reserves total $37,020 per year before owner cash.
Keep a separate off-season cash forecast for film settlements, payroll, insurance, utilities, repairs, and known debt payments before approving a distribution.
What do low, base, and high owner-income cases look like?
The three cases change volume and costs together. Low revenue averages $58,000 per month with 60% gross margin and $31,000 of operating costs; high revenue averages $100,000 with 64% gross margin while labor, overhead, and marketing also rise. Exact annual owner income after each case's modeled tax and reinvestment reserves is $32,832 low, $78,660 base, and $138,240 high.
Owner income scenarios
Low, base, and high cases show how attendance, yield, staffing, cost structure, and reserve policy change owner cash.
Drive-in movie theater low, base, and high owner-income planning cases.
Scenario factor
Low CaseDownside
Base CasePlanning
High CaseUpside
Launch modelDemand and operating season
145 operating nights
110 cars per night
2.25 paid guests per car
$696,000 annual revenue
150 operating nights
120 cars per night
2.3 paid guests per car
$864,000 annual revenue
165 operating nights
140 cars per night
2.35 paid guests per car
$1,200,000 annual revenue
Typical setupPrice, spend, and margin
$11.25 blended ticket
$7.25 concession spend
60% gross margin
Owner-operated
$11.75 blended ticket
$8.25 concession spend
62% gross margin
Owner-operated
$12.50 blended ticket
$8.75 concession spend
64% gross margin
Added peak staffing
Cost driversAverage monthly cash costs
$11,500 labor
$10,000 fixed overhead
$2,000 marketing
$7,500 debt
$14,500 labor
$10,500 fixed overhead
$2,500 marketing
$7,500 debt
$22,000 labor
$12,500 fixed overhead
$4,000 marketing
$7,500 debt
Owner income rangeAfter modeled tax + reinvestment reserves
$32,832
$78,660
$138,240
Best fitHow to use the case
Stress-test a soft season, weaker per-guest spend, and minimum staffing before committing to owner draws.
Use as the operating plan for a stabilized owner-run single-screen venue with normal staffing and debt service.
Test stronger utilization only with the added payroll, marketing, and fixed support required to serve the volume.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
How do the six drivers change owner cash week to week?
The same six drivers become actionable when each has a measurable operating rule. The sensitivities below show how another car, another concession dollar, one margin point, one ticket dollar, a management hire, or an unplanned fixed cash hit changes the owner's income pool.
1. Car count and operating nights
Use vehicles served as the capacity denominator
The base case uses 150 operating nights and 120 cars per night, below a 300-car planning capacity. Ten more cars per night × 150 nights × 2.3 paid guests × $20 combined ticket-and-concession spend equals about $69,000 of added annual sales. At a 62% blended gross margin, that is roughly $42,780 before extra labor, marketing, and reserves. Weather, film strength, and shoulder-season nights make utilization uneven, so the annual average must be backed by nightly car counts.
Track vehicles before you celebrate ticket revenue
Base marketing is $30,000 a year, or about $1.67 per base car visit across 18,000 visits. That is not true customer-acquisition cost because many guests repeat or arrive organically, so track paid acquisition cost and repeat attendance separately.
Cars admitted per operating night.
Paid guests per car.
Capacity utilization by weekday and film.
Revenue per car party.
If cars rise but revenue per car falls, discounting or weak concessions may be hiding the real economics.
2. Concession spend per patron
Turn attendance into food-and-beverage contribution
The base assumes $8.25 of concession sales per paid guest. As an adjacent multiplex proxy, Cinemark's Q2 2026 U.S. concession revenue per patron was $8.70, useful as a check rather than a drive-in guarantee. At 41,400 guests, another $1 of spend adds $41,400 of annual sales; with 20% product cost, about $33,100 remains before extra labor, card fees, spoilage, and reserves. Menu mix and service speed therefore feed directly into owner cash.
Track spend and attachment rate together
Average spend can rise because fewer people buy expensive items, while total food contribution still disappoints. Pair dollars per guest with the share of car parties that actually purchase.
Concession revenue per paid guest.
Transactions per 100 car parties.
Food and packaging cost percentage.
Waste, comps, and outside-food permits.
The owner-cash goal is not the highest menu price; it is the highest repeatable gross contribution after product and labor friction.
3. Film and concession direct costs
Reconstruct gross margin before using it
Gross margin must keep film settlement and concession supplies separate from payroll. Cinemark's U.S. Q2 2026 segment reported $258.4 million of film rentals and advertising on $434.4 million of admissions revenue, about 59.5%, and $62.6 million of concession supplies on $348.9 million of concession revenue, about 17.9%. The Georgetown Drive-In also says most admission revenue goes back to the movie theaters. This model's 62% blended gross margin is a planning reconstruction, not an industry standard; actual distributor and supplier terms should replace it.
One gross-margin point on $864,000 of annual sales equals $8,640 of annual gross profit. After the base 32% combined reserve rate, that could translate to roughly $5,875 of additional owner cash if every other cost truly stays unchanged.
Reconcile margin by revenue stream
Do not manage gross margin as one unexplained percentage. Tie ticket settlement to admissions revenue and concession product cost to concession revenue, then add processing and other truly variable non-labor costs.
Film settlement as percent of admissions.
Concession supplies as percent of concession sales.
Card and online payment fees.
Blended gross margin before payroll.
A stronger concession mix can lift blended margin even when film terms are unchanged, which is why revenue mix belongs in the owner-income forecast.
4. Ticket price and party mix
Price the blended guest, not only the adult
Evergreen Drive-In lists $11 adult admission, while the earlier Paramount example is $14; both also charge less for children. The model's $11.75 is therefore a blended paid-guest yield. At 41,400 paid guests, another $1 of realized ticket yield adds $41,400 of admissions revenue. With a 52% incremental film-settlement assumption, about $19,900 remains before payment costs and reserves; after the base 32% reserve rate, potential owner cash is closer to $13,500. The marginal ticket dollar is shared, not retained in full.
Track realized yield by customer type
Use actual admissions revenue divided by paid guests and reconcile the result to adult, child, free, promotional, and special-event attendance.
Blended paid-ticket yield.
Adult and child mix.
Free and promotional admission rate.
Peak-night versus off-peak yield.
If posted prices rise but blended yield does not, discounts or mix are absorbing the increase and the owner-income forecast should not assume the full sticker-price gain.
5. Labor and owner coverage
Count owner hours as work even when cash payroll is low
Base hired payroll is $14,500 per average month, or $174,000 annually, before owner pay. The May 2025 BLS wage table reported $15.91 mean hourly pay for ushers, lobby attendants, and ticket takers and $24.75 for projectionists. Owner-covered programming, staffing, vendor, cash-control, and closing work is labor, not passive return. Adding a $5,000 monthly manager-and-burden test cuts annual owner income to about $37,860 after modeled reserves, roughly $40,800 below base because the reserve base shrinks too.
Schedule to cars and concession transactions
Staffing should move with actual show volume and food demand, while safety, gate, and closing coverage remain non-negotiable. Keep the owner's hours on the same weekly report as paid labor.
Labor dollars per car served.
Paid hours per operating night.
Concession labor per transaction.
Owner hours by management task.
If revenue rises only because the owner adds unpaid hours, the business has improved cash flow but not necessarily improved the owner's economic return per hour.
6. Fixed costs, debt, and reserves
Protect owner cash from the off-season and repair cycle
Base fixed overhead is $10,500 per month and modeled debt service is $7,500, or $18,000 before marketing and payroll. Adding $2,500 of marketing makes fixed-plus-debt-plus-marketing cash $246,000 annually before hired labor and direct costs. The base tax and reinvestment holdbacks total $37,020 for the year; they are planning reserves, not tax law. A $20,000 unbudgeted projector, screen, lot, or electrical repair would equal about one quarter of modeled annual owner income, which is why accounting profit can coexist with an unsafe draw.
Run a cash forecast before approving distributions
Use a rolling cash view that bridges the operating season into the closed or reduced-demand months. Owner distributions should be the final line after known obligations and reserve floors.
Thirteen-week cash forecast.
Debt principal and interest due dates.
Insurance, utility, and property cash commitments.
Projector, screen, lot, and concession-equipment reserve.
The practical definition of owner income is cash the business can release without forcing the next slow month, tax payment, or equipment failure back onto a credit card or emergency loan.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.