Why Do Costs Change Owner Earnings in a Duck Farming Business?
A U.S. owner-operated meat-duck farm can realistically produce about $67,200 a year in owner income in the base case after a 20% tax reserve and 10% reinvestment reserve. The model assumes about $480,000 in annual sales, roughly 8,900 saleable Pekin-type meat ducks, a 48% gross margin after direct bird costs, and an owner who handles management, sales, and some flock work. Hired labor, overhead, marketing, and $18,000 of annual debt service are paid first. The $67,200 is not guaranteed salary, EBITDA, or a guaranteed distribution, and it excludes final personal taxes and unmodeled capital projects.
Owner income$67KNet margin14%Revenue for target pay$494KBusiness difficultyHard
How much can a duck farm owner make in this model?
The practical answer is about $67,200 a year in owner cash after modeled reserves for a farm selling meat ducks rather than eggs or breeding stock. The scope matters. This article models a small-to-mid-scale U.S. Pekin-type meat-duck operation selling mostly whole birds and some parts directly to households, farmers-market customers, and restaurants. It does not blend in duck-egg revenue, hatchery revenue, foie gras, hunting preserves, or a contract-growing model.
USDA's 2026 first-quarter National Pasture Raised Poultry Report showed direct-to-consumer whole duck at $6.35 to $16.99 per pound, averaging $10.08. The base case assumes a 5.35-pound saleable bird and about $54 blended revenue per finished duck, near that national direct-market average. Roughly 8,900 finished birds at $54 produces about $480,000 annual revenue.
Production biology sets the other side. University of Kentucky Extension notes that Pekin ducklings are commonly marketed at 6 to 7 pounds live at seven to nine weeks after consuming about 20 to 25 pounds of feed. Its meat-duck feeding guidance makes feed use, mortality, and harvest timing key cost checks.
In the base case, $40,000 monthly revenue at a 48% gross margin leaves $19,200 after direct bird costs. Hired labor, fixed overhead, marketing, and debt service total $11,200, leaving $8,000 before reserves. A $1,600 tax reserve and $800 reinvestment reserve reduce owner income to $5,600 monthly, or $67,200 annually. Operating break-even before owner pay is about $23,333 a month; a $6,000 monthly owner-pay target after reserves requires about $41,190 a month, or $494,280 a year.
Owner income calculator
Adjust revenue, margin, operating costs, reserves, and target pay to estimate owner cash from a meat-duck farm.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What drives duck farm owner income most?
Price starts the income chain, but mortality, feed, processing, labor, and customer acquisition decide how much revenue survives. Processing deserves special attention in ducks: one current processor lists 50-plus ducks at $14.25 per bird. Local written quotes should therefore be secured before treating gross margin as settled. The calculator uses a 48% base gross margin rather than assuming that premium retail pricing automatically becomes premium profit.
1
Realized selling price
$10.08/lb benchmark
USDA's 2026 Q1 direct-market average supports a premium channel, but every $1 per pound on a 5.35-pound bird changes revenue about $5.35 per sale.
2
Saleable birds
8,900/year base
Mortality, condemnations, and missed processing dates shrink the birds available to sell while much of the feed and labor has already been spent.
3
Feed efficiency
20-25 lb feed/bird
Extension guidance shows why feed per finished bird is a major direct-cost lever; small feed waste repeated over thousands of ducks becomes owner-income leakage.
4
Processing economics
$14.25/bird quote
A current 50-plus-bird duck processing quote consumes more than one quarter of a $54 base-case sale before feed, ducklings, and packaging.
5
Labor productivity
$18.88/hr mean wage
BLS May 2025 mean pay for farmworkers handling animals makes task hours per 100 ducks as important as the nominal hourly wage.
6
Channel sell-through
48% base gross margin
Direct sales can support price, but unsold frozen inventory, market fees, delivery time, and restaurant discounts can erase the advantage.
Want to test flock size, pricing, and cash flow in a full forecast?
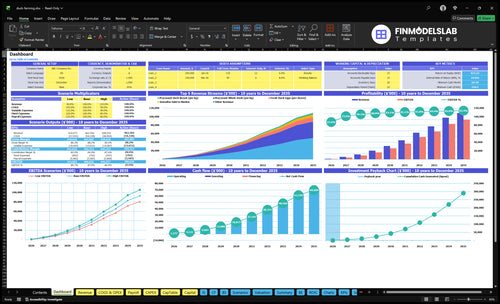
The Duck Farming Five-Year Financial Model Template dashboard can help test revenue, flock volume, price mix, feed, processing, staffing, debt, and cash timing instead of relying on one annual profit number.
How many finished ducks and what selling price support owner pay?
In the base case, the farm needs about 8,900 saleable ducks a year at roughly $54 of blended revenue per bird to approach $480,000 in annual sales. The $54 planning blend uses a 5.35-pound dressed bird near the USDA 2026 Q1 direct-to-consumer whole-duck average of $10.08 per pound. Wholesale discounts, carcass-weight variation, and unsold inventory can pull realized revenue below a posted retail price.
Base revenue math
About 8,900 saleable birds per year.
About 742 saleable birds per average month, though production is batch-based rather than perfectly even.
Roughly $54 blended revenue per bird produces about $480,000 annual sales.
A $5 drop in realized revenue per bird removes roughly $44,500 of annual sales at the same volume.
Capacity checks before scaling
Extension guidance puts Pekin market age around seven to nine weeks, so batch spacing controls housing and brooder turnover.
Do not budget revenue from chicks placed; budget from birds actually processed, packaged, and sold.
Keep restaurants and direct customers on separate realized-price reports so discounts cannot hide inside a blended average.
Track frozen inventory days because a full freezer can become a production constraint even when flock capacity looks available.
USDA's Poultry Slaughter survey explicitly tracks ducks under federal inspection, showing that duck is a real but specialized poultry market. For a small farm, though, national slaughter volume does not guarantee local demand. Pre-orders, chef commitments, farmers-market sell-through, and repeat households are better capacity signals than the number of birds the farm could theoretically raise.
Can a duck farm stay profitable when feed, processing, and labor costs rise?
Yes, but only if price and productivity move with costs. The base 48% gross margin means direct non-labor bird costs consume 52% of sales, or about $28 per $54 bird. A Tennessee processor currently lists duck processing at $14.25 per bird for batches of 50 or more, including a basic bag and label. That alone uses about 26% of the base-case revenue per bird before duckling cost, 20 to 25 pounds of feed, mortality, transport, and payment fees.
What a margin squeeze does
At $40,000 monthly revenue, each one-point gross-margin change moves gross profit by $400 a month.
Dropping from 48% to 43% removes $2,000 a month before reserves, or $24,000 a year.
With the same $11,200 operating-cost base, 43% gross margin raises operating break-even from about $23,333 to about $26,047 monthly.
Processing quotes and feed contracts should be refreshed before every major placement cycle.
Owner labor is not free
The calculator's $4,500 monthly labor input covers hired staff, not the owner.
BLS May 2025 wage data report a $18.88 mean hourly wage and $39,260 mean annual wage for farmworkers caring for farm, ranch, and aquacultural animals.
BLS also reports about $62,730 mean annual pay for first-line supervisors of farming, fishing, and forestry workers.
If the owner steps away and a manager is hired, passive distributions can fall sharply even if flock sales do not change.
Biosecurity can turn a biological event into a cash-flow event. USDA APHIS identifies wild birds as a primary HPAI transmission source in its 2026 avian-influenza biosecurity guidance. Mortality, downtime, disinfecting, and movement restrictions can interrupt inventory and sales, supporting a reinvestment reserve rather than distributing every profitable dollar.
Key Takeaways
The base model generates $67,200 annual owner income after modeled reserves on $480,000 annual revenue.
About $494,280 annual sales are needed to support a $6,000 monthly owner-pay target under the base margin and cost structure.
Processing, feed conversion, mortality, and hired labor can erase premium duck pricing faster than headline retail prices suggest.
Owner income is cash planning output, not automatically salary, EBITDA, accounting profit, or a safe distribution.
How much cash can the owner safely take out?
Safe owner cash is lower than accounting profit whenever debt, taxes, working capital, or replacement equipment still need funding. The base case produces $8,000 per month before reserves after operating costs and debt service, or $96,000 a year. Holding back $28,800 for tax and reinvestment leaves $67,200 of modeled owner income. That reserve policy does not guarantee the remainder is legally or tax-efficiently distributable.
Owner salary and distributions depend on entity type. The IRS paying-yourself guidance explains that compensation procedures vary by structure; for S corporations, its S corporation compensation guidance says shareholder-employees must receive reasonable compensation before non-wage distributions. This model keeps owner pay out of hired labor and reports residual owner income; actual bookkeeping may divide the $67,200 between wages and distributions.
EBITDA is different again. This calculator includes principal and interest debt service because it measures owner cash, so “profit before reserves” is not EBITDA. Accounting net income can also differ because depreciation, interest, taxes, and compensation are classified differently. Before distributing cash, cover suppliers, payroll, debt, tax reserve, flock working capital, freezer inventory, repairs, and required biosecurity spending.
Base owner-cash bridge
$480,000 annual revenue.
$230,400 gross profit after non-labor direct bird costs.
$134,400 annual hired labor, overhead, marketing, and debt cash service.
$96,000 before reserves, then $28,800 reserved, leaving $67,200 owner income.
Debt changes the draw decision
The base case includes $1,500 monthly principal-and-interest debt service.
SBA notes that 7(a) loan rates are negotiated with lenders and subject to program maximums; its 7(a) lender guidance is a useful benchmark when stress-testing financed equipment or real estate.
Do not confuse loan principal with an income-statement expense; it still consumes cash available for owner distributions.
Model a no-debt and higher-rate case before deciding that one profitable year supports a larger draw.
What do low, base, and high income cases look like?
The range is wide because duck farming combines biological yield with a specialty sales channel. The low case assumes $300,000 annual revenue, a 42% gross margin, and minimum fixed costs. The base case is the 8,900-bird, $480,000 sales model. The high case reaches $840,000 only by adding labor, marketing, overhead, and debt service. All three keep owner labor outside hired payroll and treat owner income as the residual after modeled tax and reinvestment reserves.
Processing rules can cap scale. Cornell Small Farms' poultry processing guide explains that ducks are covered by the Poultry Products Inspection Act, describes 1,000- and 20,000-bird federal exemptions, and warns that states can be stricter. The high case's roughly 14,000 saleable birds is not permission to use any exemption; verify state licensing, channel, facility, labeling, and inspection rules.
Owner income scenarios
Low, base, and high cases show how bird volume, realized price, gross margin, staffing, overhead, and reserves change owner cash.
Duck Farming low, base, and high owner-income planning cases.
Scenario
Low CaseConservative
Base CasePlanning
High CaseUpside
Launch modelDemand and scale
Slower sell-through and smaller batches; owner absorbs more labor.
Established local direct market plus selected restaurant accounts.
Strong direct demand, more cuts, larger batches, and added staff.
Typical setupAnnual run rate
$300,000 revenue; about 6,000 birds at $50 blended revenue per bird.
$480,000 revenue; about 8,900 birds at $54 blended revenue per bird.
$840,000 revenue; about 14,000 birds at $60 blended revenue per bird.
Cost driversMargin and operating load
42% gross margin
$3,200 labor/month
$3,800 overhead/month
$700 marketing/month
$1,500 debt/month
48% gross margin
$4,500 labor/month
$4,000 overhead/month
$1,200 marketing/month
$1,500 debt/month
52% gross margin
$9,000 labor/month
$5,200 overhead/month
$2,500 marketing/month
$2,200 debt/month
Owner income rangeAfter modeled tax + reinvestment reserves
$12,012/year
$67,200/year
$138,600/year
Best fitHow to use the case
Stress-test weak demand, owner-heavy labor, and limited pricing power.
Plan a functioning owner-operated farm with repeat direct customers.
Test expansion only when processing slots, labor, freezer space, and demand are committed.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six duck-farm income drivers deserve weekly attention?
These six levers belong on a weekly operating dashboard. Track contribution per finished duck, saleable yield, feed use, processing economics, owner and hired labor, and channel sell-through before higher annual sales are treated as higher owner income.
1. Realized selling price per pound
Price from actual invoices, not the posted board
USDA's 2026 Q1 pasture-raised report put whole duck at $6.35 to $16.99 per pound, averaging $10.08. The base model uses about $54 on a 5.35-pound saleable bird. A $1-per-pound change on 8,900 birds at 5.35 pounds changes annual revenue by about $47,600 before added selling cost. Capture discounts, card fees, and carcass-weight variation in realized price. Use the USDA pasture-raised poultry report series as a market reference, then compare it with your invoices.
Track net dollars per saleable pound
Separate whole birds, parts, restaurant cases, and direct households so a strong premium channel cannot mask a weak one.
Average realized $/lb by channel.
Average dressed pounds per sold bird.
Discounts and payment fees as a percent of sales.
Unsold pounds older than 30 and 60 days.
2. Saleable birds, mortality, and batch completion
Revenue begins with birds that reach the freezer
The base model needs roughly 8,900 saleable birds, not 8,900 ducklings placed. University of Kentucky Extension's meat-duck management guidance emphasizes daily care and ventilation. If saleable yield falls from 95% to 90% while 8,900 sold birds are still required, placements rise from about 9,368 to 9,889. More than 500 extra birds then consume feed, space, and labor merely to hold revenue flat.
Measure loss by stage and cause
A single annual mortality percentage is too late to manage. Split brooder losses, grow-out losses, transport losses, condemnations, and processing rejects.
Placed birds versus saleable birds.
Mortality by week of age.
Condemnations or downgrades per batch.
Finished birds per square foot and per labor hour.
APHIS's Defend the Flock program provides biosecurity resources; prevention protects both flock health and future saleable inventory.
3. Feed cost per finished duck
Control pounds consumed, not just bag price
Extension guidance says Pekin ducks commonly consume about 20 to 25 pounds of feed to reach 6 to 7 pounds live weight at seven to nine weeks. At 8,900 sold birds, every extra pound of feed per saleable bird means 8,900 additional pounds purchased. At a planning $0.35 per pound, one avoidable pound costs about $3,115 a year. Track feeder spillage, storage loss, ration changes, and harvest timing alongside supplier price.
Close every batch with a feed reconciliation
Record feed issued from arrival through processing, then divide by saleable birds and saleable pounds.
Feed pounds per saleable bird.
Feed pounds per saleable pound.
Feed dollars per saleable bird.
Spillage and wet-feed loss observations.
Use the University of Kentucky feeding benchmark as a biological reference, then replace the planning feed price with your contracted delivered cost.
4. Processing cost and processing capacity
A processing slot is both a cost and a capacity asset
At $14.25 per bird, processing 8,900 ducks costs about $126,800 before optional cut-up, hauling, special packaging, or higher local rates. At $20 per bird, it costs $178,000, a $51,200 difference. Processing also controls harvest timing: a booked processor can keep ducks on feed longer and occupy housing that should turn to the next batch. Treat processing as a direct per-bird cost and capacity constraint.
Book the economics before placing the flock
Get written per-bird pricing, minimum batch size, inspection status, labels, cut-up fees, delivery rules, and available dates before ordering ducklings.
Processing $/saleable bird.
Round-trip transport $/bird.
Days over planned market age.
Processor capacity already reserved for the next 90 days.
Use current processor schedules as cost evidence and verify legal sales channels separately; Cornell's processing guide notes that exempt poultry rules and state requirements can limit where and how birds are sold.
5. Hired labor and owner replacement cost
Separate farm profit from unpaid owner work
The base case spends $54,000 a year on hired labor while the owner still manages production, sales, processing coordination, and some chores. BLS reported May 2025 mean pay of $18.88 per hour for farmworkers caring for farm, ranch, and aquacultural animals and $62,730 annually for first-line farming supervisors. Those are national occupation references, not duck-farm quotes. Replacing 20 owner hours a week at a planning $25 per hour is roughly $26,000 a year before payroll burden.
Track owner hours beside payroll
Owner labor should be visible even when the calculator treats owner income as a residual. Otherwise growth can appear profitable only because the owner silently adds more unpaid hours.
Hired labor hours per 100 saleable birds.
Owner hours per week by chores, sales, and management.
Payroll dollars per saleable bird.
Estimated manager replacement cost.
Use national BLS wage data as a floor for comparison, then price local labor and supervisory coverage.
6. Direct-channel sell-through and customer acquisition
Premium price only works when premium inventory sells
The base case budgets $14,400 a year for marketing and market access. Direct sales may support a higher realized price, but market fees, delivery, websites, card fees, and owner selling time buy that premium. Moving 1,000 birds from a $54 direct sale to a $42 discounted or wholesale sale cuts annual revenue by $12,000 before selling-cost savings. Frozen unsold birds are worse for cash because most production cost has already been paid.
Manage demand before adding birds
Use confirmed pre-orders, repeat households, restaurant reorder rates, and freezer aging to decide placements. USDA's slaughter data show ducks are part of the national inspected poultry market, but your local sell-through is the number that funds owner income.
Customer acquisition cost by channel.
90-day repeat-purchase rate.
Percent of each batch pre-sold before processing.
Frozen inventory value and days on hand.
Check the USDA NASS poultry slaughter program for industry context, but make production decisions from your own booked demand and realized margin.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Duck Farming Bundle
Choosing a selection results in a full page refresh.