How Should an Owner Estimate Income from an Exotic Bird Breeding Business?
For a U.S. owner-operated companion-parrot aviary, a realistic planning range is about $23,000 to $137,000 a year in owner income after modeled tax and reinvestment reserves, with a base case of about $78,000 on $540,000 of annual bird sales. This article models a licensed, direct-to-consumer breeder with roughly 100 productive pairs and a mix weighted toward caiques, African greys, Amazons and selected conures rather than poultry or wild-caught birds. The base case assumes about 225 saleable juveniles a year at a $2,400 realized average, a 68% gross margin after non-labor bird-care costs, $108,000 of hired payroll, $84,000 of fixed overhead, $27,000 of marketing, and $24,000 of annual debt service. The $78,000 figure is residual owner cash after a 25% planning tax reserve and 12% reinvestment reserve; it is not guaranteed salary, passive income, or a promise that all accounting profit can safely be distributed.
Owner income$78KNet margin14%Revenue for target pay$567KBusiness difficultyHard
How much can an exotic bird breeding owner actually keep?
The base case produces $45,000 of monthly revenue and $30,600 of gross profit. After $9,000 of hired labor, $7,000 of fixed overhead, $2,250 of marketing, and $2,000 of debt service, profit before reserves is $10,350 a month. The model then sets aside $2,588 for taxes and $1,242 for reinvestment, leaving $6,520 a month, or $78,240 a year, for owner compensation. That distinction matters because revenue is not income, gross profit is not EBITDA, and accounting profit is not automatically cash that can leave the aviary. Demand is real but specialized: the 2025 APPA bird-ownership report says six million U.S. households own birds, yet a breeder still has to earn trust, match buyers to species, and move chicks when they are fully weaned rather than when cash is convenient.
Owner income calculator
Estimate owner take-home from bird sales, margins, staffing, overhead, financing, and reserve choices.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Saleable juvenile yield
225 birds/yr
The base case needs about 2.25 saleable juveniles per productive pair across 100 pairs; infertility, chick loss, delayed weaning, or retained breeders cut revenue before price can help.
2
Species mix and price
$2,400 avg.
A few higher-value greys, Amazons, or caiques can lift the blended ticket, while a conure-heavy mix can push average revenue per bird sharply lower.
3
Direct-cost control
68% GM
The planning margin leaves 32% of sales for feed, testing, direct veterinary inputs, supplies, payment costs, shipping materials, and biological-loss allowance before payroll.
4
Labor productivity
$108K/yr
The base payroll assumes the owner remains full-time in breeding, management, and buyer work; replacing those hours with a hired manager or more handlers reduces owner cash unless volume grows.
5
Overhead and financing
$108K/yr
Fixed overhead plus debt service consumes $9,000 a month before marketing, so climate control, facility size, insurance, and borrowed buildout set a hard break-even floor.
6
Buyer pipeline and cash
5% marketing
Deposits, waitlists, referrals, and prompt placement reduce the time a weaned bird stays on payroll and feed while protecting cash for tax, flock replacement, and health events.
Want to test breeding yield, pricing, and owner cash in a full forecast?
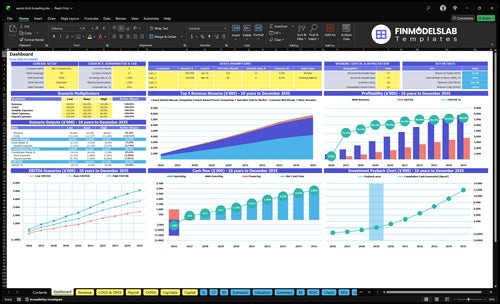
The Exotic Bird Breeding Financial Model Template in Excel provides a spreadsheet view for testing bird-sale revenue, breeding yield, payroll, direct costs, capex, and cash runway. Use the dashboard to compare your flock and species mix with the owner-income assumptions here; it does not make any sales or profit outcome guaranteed.
What sales volume supports a $90,000 owner-income target?
The base cost structure needs about $47,286 a month, or $567,432 a year, to support a $7,500 monthly owner-income target after reserves. At a $2,400 realized price, that is roughly 237 birds a year; at $2,000, about 284. Current asking prices show the spread: a March 2026 black-headed caique listing was $2,400, while an August 2026 green-cheek conure listing was $375. The planning volume must match the actual species mix.
Base revenue bridge
225 saleable birds × $2,400 average = $540,000 annual sales.
The base target is about 237 birds at the same average price.
Break-even before owner reserves is about $29,779 monthly sales.
A waiting list helps only if hatch, survival, and weaning dates support deliveries.
What the volume math hides
A pair may fail to breed, lay infertile eggs, abandon chicks, or need a rest season.
Retaining a high-quality juvenile for future breeding improves future capacity but removes a sale today.
Higher-value species generally tie up more breeder capital and customer-acquisition time.
Shipping, health paperwork, refunds, and rehoming policies can reduce realized revenue.
How much do species mix and sale price change owner income?
Price mix can move owner income faster than bird count. One Florida aviary currently lists African greys at $5,900, white-bellied caiques at $2,400, Senegals at $2,200, and yellow-naped Amazons at $3,500 on its current parrot price page. Another U.S. breeder lists African greys from roughly $1,500 to $2,500 on its aviary pricing page. The spread supports using a blended $2,400 realized planning price, not a universal market average.
Use a weighted ticket
Forecast birds by species, not one blanket selling price.
Apply a separate sell-through and hatch assumption to each species group.
Use realized cash price after discounts, refunds, and any absorbed delivery cost.
Keep breeder-stock purchases out of routine revenue assumptions.
Quick sensitivity
At 225 birds, every $100 of realized price is $22,500 of annual revenue.
At a 68% gross margin, that $22,500 creates about $15,300 of gross profit before labor and overhead.
If buyer demand forces a $400 average discount, annual revenue falls $90,000.
Premium pricing works only when health, documentation, socialization, and breeder reputation support it.
Can an exotic bird breeding business run without the owner?
Not cheaply. The base model assumes a working owner-manager and lead breeder. The May 2025 BLS national wage table reports animal caretakers at a mean $17.94 an hour and $37,300 annually. Two caretaker-equivalent jobs imply about $74,600 of straight wages before employer costs or specialized premiums. The $108,000 base payroll supports those roles plus periodic help while the owner still covers breeding decisions, records, sales, and emergencies.
Owner-operated base case
Owner covers management, breeder selection, sales, and high-skill husbandry.
Hired payroll is $9,000 per month before owner pay.
Owner income therefore includes compensation for labor plus entrepreneurial return.
Track owner hours so the business is not mistaken for passive income.
Manager-run test
Add a real manager or senior aviculturist wage before calling distributions passive.
A $60,000 replacement salary plus payroll burden can absorb most of the base owner income.
Higher scale can justify management, but payroll must rise with bird count and service expectations.
Do not count the same owner labor once as payroll and again as a distribution.
Key Takeaways
The base model is $540,000 revenue and $78,240 of owner income after modeled reserves.
About $567,000 of annual revenue is needed to support a $90,000 target owner take-home under base costs.
Yield and species mix matter more than nominal flock size; unsold or retained birds do not pay overhead.
Owner cash is safe only after direct care costs, hired payroll, overhead, marketing, debt service, tax reserve, and reinvestment reserve are funded.
How should debt, taxes, and reinvestment change the owner draw?
Cover bird care and payroll first, then overhead, marketing, debt service, and reserves before deciding what can leave the business. If the aviary elects S corporation treatment, IRS reasonable-compensation guidance says a shareholder-employee must receive reasonable compensation before non-wage distributions. The calculator's $78,240 base owner income is therefore cash availability; tax structure may split it between W-2 wages and distributions.
Debt changes cash even when accounting profit looks healthy. The base case includes $24,000 a year of principal-and-interest service. The SBA 7(a) loan page notes that rates are negotiated within program maximums, so the model uses a fixed payment rather than a universal rate. Less debt can free cash for owner pay or reserves; more debt should reduce distributions.
Pay the business first
Direct costs and payroll come before owner distributions.
Debt principal is a cash outflow even though it is not an operating expense in the same way as feed or wages.
Hold tax cash separately from working capital.
Reserve for cages, HVAC, quarantine systems, breeder replacement, and veterinary surprises.
Keep the definitions straight
Revenue is customer cash earned from bird sales.
Gross profit is revenue after non-labor direct costs.
EBITDA and operating profit are accounting measures; they are not the calculator’s cash residual because debt principal is a cash outflow and depreciation is not modeled here.
The calculator’s profit-before-reserves figure is cash-planning profit after hired labor, overhead, marketing, and debt service.
Owner salary pays for work; a draw or distribution is equity cash. Safe owner cash is the residual after modeled reserves.
What do low, base, and high owner-income cases look like?
The cases change both volume and cost. Low assumes a smaller flock and lower realized pricing; base is an owner-led commercial aviary; high adds staff, space, marketing, and debt capacity. USDA's Animal Welfare Act bird guidance says Class A licensing thresholds include more than 200 small pet birds or more than eight large pet birds hatched on the premises, so a premium-parrot operation can reach regulated scale quickly.
Owner income scenarios
Compare a smaller breeder, the owner-operated base case, and a scaled premium-mix aviary using the same calculator formulas.
Low, base, and high Exotic Bird Breeding owner-income planning cases.
Scenario
Low CaseSmaller scale
Base CaseOwner-operated
High CaseScaled premium mix
Launch modelRevenue engine
About 150 saleable birds a year at a $2,000 realized average.
About 225 saleable birds a year at a $2,400 realized average.
About 300 saleable birds a year at a $3,000 realized average.
Owner income rangeAfter modeled tax and reinvestment reserves
$22,680
$78,240
$136,800
Best fitPlanning use
Stress-test a smaller flock, weaker hatch results, and a value-priced species mix.
Use for an owner-led commercial aviary with two caretaker-equivalent hires and disciplined reserves.
Test expansion only when premium demand, space, skilled staffing, and breeding yield are already proven.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers matter most for exotic bird breeder income?
Owner income depends on six linked levers: saleable yield, realized price, direct-care margin, labor productivity, fixed cash burn, and buyer conversion. Biosecurity affects all six: the CDC's 2025 psittacosis prevention guidance calls for avoiding overcrowding, isolating infected birds, and careful cage cleaning. Those practices cost labor and space, but disease can delay sales and damage the reputation that supports premium pricing.
1. Saleable juvenile yield per productive pair
Model birds sold, not eggs laid
The base case assumes 100 productive pairs and 225 saleable juveniles a year, or 2.25 saleable birds per pair. That is a mixed-parrot planning assumption, not a species benchmark. If only 190 birds sell at the same $2,400 average, revenue drops from $540,000 to $456,000; at a 68% gross margin, about $57,120 of gross profit disappears before fixed costs adjust.
Scale can also change compliance. USDA's bird standards page distinguishes small and large pet birds and explains breeder licensing thresholds. Premium-parrot operations can reach the large-bird threshold at relatively low unit volume, so yield changes both revenue and compliance workload.
Track biological conversion every clutch
Track the funnel from productive pair to fertile egg, hatchling, weaned juvenile, retained breeder, and bird sold. Owner income is most sensitive to the last stage.
Saleable juveniles per productive pair
Infertile egg rate
Chick loss before weaning
Days from hatch to paid placement
Percent retained for future breeding
If yield falls for two cycles, cut the sales forecast before adding pairs; more breeders can raise cost without fixing a husbandry bottleneck.
2. Species mix and realized selling price
Price the actual mix buyers take home
Current U.S. asking prices range from hundreds to several thousand dollars. The August 2026 green-cheek listing cited above was $375 and the March 2026 caique listing was $2,400. The model's $2,400 realized average therefore assumes a premium mix; it does not fit an aviary dominated by lower-priced species.
Here's the quick math: 225 birds at $2,400 create $540,000 of annual revenue. A $300 drop in realized price cuts revenue by $67,500 and, at a 68% gross margin, cuts gross profit by about $45,900 before payroll or overhead changes.
Track price by species and channel
Use completed sales, not asking prices, and separate pickup from shipped sales when the breeder absorbs certificates, crates, or delivery subsidies.
Realized price by species
Discounts and refunds
Days on waitlist before deposit
Shipping cost absorbed by breeder
Revenue concentration by top species
If one species weakens or deposits slow, reduce its hatch forecast before cutting welfare or socialization time.
3. Direct bird-care cost and gross margin
Protect margin without underfunding care
The base calculator uses a 68% gross margin, leaving 32% of revenue, or $172,800 a year, for non-labor direct costs: feed and formula, nesting and brooder supplies, direct veterinary inputs, testing, paperwork, merchant fees, transport materials, and biological-loss allowance. Employee payroll stays in the separate labor field.
Health spending protects revenue as well as welfare. The current caique listing cited above advertises disease testing and avian-veterinary documentation. Saving $100 per bird by cutting testing or sanitation would add $22,500 to apparent margin at 225 birds, but a preventable health event can delay placements and destroy premium-price trust.
Measure direct cost per saleable bird
Reconcile gross margin monthly and allocate direct costs to saleable birds, not only to chicks that hatch.
Feed and formula per saleable juvenile
Testing and health-certificate cost
Vet spend tied to production
Payment and shipping material cost
Loss allowance per breeding pair
If margin falls from 68% to 63% at $540,000 revenue, annual gross profit falls $27,000 before fixed costs change.
4. Labor productivity and the owner's working role
Separate hired payroll from owner labor
The base case carries $108,000 a year of hired payroll and keeps the owner full-time. BLS reported a May 2025 national mean of $37,300 for animal caretakers, so two straight-wage roles total about $74,600 before employer taxes, benefits, overtime, or specialized aviculture premiums. The remaining payroll buffer supports periodic help, not a full owner replacement.
For a manager-run business, add the replacement role first. A $60,000 manager salary plus payroll burden could absorb most of the $78,240 base owner income unless revenue rises. The calculator therefore excludes owner pay from laborCost and treats owner take-home as the residual; the same labor cannot be paid twice.
Track labor by birds sold and owner hours
Track hours against chick count, hand-feeding intensity, sanitation, buyer communication, and shipping; flock size alone is a weak staffing metric.
Paid labor dollars per bird sold
Owner hours per week
Chicks in hand-feeding at peak
Cleaning hours per enclosure zone
After-hours health events
If owner hours remain unsustainable, treat the next hire as a cost of maintaining output; otherwise profit is subsidized by unpaid founder labor.
5. Fixed overhead and financing burden
Know the cash floor before breeding season starts
The base case spends $7,000 a month on fixed overhead and $2,000 on debt service. That $108,000 annual fixed cash burden is due whether a clutch hatches or not. With $20,250 of total monthly operating cash costs including labor and marketing, a 68% gross margin requires about $29,779 of monthly revenue before owner income or reserves begin.
Borrowing can improve the facility, but debt service is still cash. The SBA says 7(a) rates are negotiated and capped relative to a base rate, so use the actual lender payment. At a 68% gross margin, every extra $1,000 of monthly debt service raises required annual revenue by about $17,647 for the same owner-pay target.
Track fixed burn and debt coverage
Build a 13-week cash forecast around hatch, weaning, and delivery dates because revenue is lumpy while rent and loan payments are not.
Fixed overhead per month
Debt service per month
Revenue-to-fixed-burn ratio
Weeks of cash on hand
Maintenance and HVAC reserve
Do not distribute a strong month if the next weeks carry heavy feed, veterinary, or buildout bills. Owner income should follow the cash cycle.
6. Buyer acquisition, deposits, and cash-reserve discipline
Turn trust into deposits before chicks are ready
The base case assigns $2,250 a month, or 5% of revenue, to buyer acquisition: photography, website upkeep, directory visibility, referrals, and reservation management. APPA's 2025 report says 21% of bird owners obtained their bird at bird stores, showing that specialist breeders compete with trusted retail channels. Health, origin, documentation, socialization, and support must be visible enough to convert suitable buyers.
Deposits improve timing but are not owner income before delivery. Keep enough liquidity for refunds or delays and protect tax and reinvestment reserves. In the base case, the 37% combined reserve turns $10,350 of monthly pre-reserve profit into $6,520 of owner income.
Track the sales pipeline as a cash-flow KPI
Measure demand against birds expected to be saleable, not eggs or unweaned chicks; the pipeline should reduce idle inventory without pressuring husbandry timelines.
Qualified inquiries per month
Deposit conversion rate
Average days from weaning to placement
Refund and cancellation rate
Cash reserve after deposits and tax set-asides
If marketing rises from 5% to 7% at $540,000 revenue with no extra sales, pre-reserve profit falls $10,800. With the base 37% combined reserve and positive profit, annual owner income falls about $6,804. Scale channels that create committed buyers, not vanity traffic.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Exotic Bird Breeding Bundle
Choosing a selection results in a full page refresh.