How Much Profit Can the Owner Keep from a Fish and Seafood Market?
A stabilized, owner-operated U.S. fish and seafood market can realistically produce about $100,500 a year of owner cash in the base planning case here, with stress-tested outcomes from $35,700 to $180,300. The base case assumes $125,000 of monthly sales, a 39% gross margin after seafood purchasing, inbound freight, packaging, card fees, and shrink, plus $22,000 of employee labor, $10,000 of fixed overhead, $2,000 of marketing, and $2,250 of debt service each month. The owner works as the buyer-manager and is not included in employee payroll; the modeled owner cash is the residual after a 23% tax reserve and 10% reinvestment reserve. It is not a guaranteed salary or distribution, and it excludes any tax true-up, extraordinary equipment replacement beyond the reserve, recovery of the owner's original equity, and future sale value.
Owner income$100.5KNet margin7%Revenue for target pay$1.48MBusiness difficultyHard
What does a realistic owner-income model look like?
The base case uses $1.5 million of annual sales because it is close to current industry scale. A July 2026 U.S. fish and seafood markets report lists about $1.4 million of 2024 sales per location, while the Census Bureau's 2023 Annual Integrated Economic Survey reports $2.861 billion of industry sales and $408.5 million of annual payroll for NAICS 445220 employer firms. These are category benchmarks, not a promise for one store.
The model is cash-focused. Gross margin is what remains after seafood purchases, inbound freight, packaging, card fees, and normal shrink; employee payroll is separate. The owner works as buyer-manager, so the $100,500 annual output covers both the value of that labor and residual ownership return. Hiring a manager must increase payroll before the remaining cash can be treated as passive income.
Owner income calculator
Adjust sales, margin, staffing, overhead, financing, reserves, and target pay to estimate monthly owner cash.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Which six numbers move fish-market owner income most?
The strongest levers are gross margin, transaction volume and ticket, shrink, staffing productivity, cold-chain overhead, and financing plus reserve policy. Demand is real but not unlimited: NOAA reports 19.7 pounds of U.S. seafood consumption per person in 2022. A specialty market still has to earn its local share through freshness, trusted sourcing, preparation help, repeat visits, and a product mix that turns quickly enough to protect margin.
1
Gross margin and buying
1 point = $15K
At $1.5 million of annual sales, one gross-margin point adds about $15,000 before reserves if labor and overhead do not rise.
2
Transactions and ticket
91 × $53
About 91 tickets a day at a $53 average ticket over 26 selling days produces roughly the $125,000 base month.
3
Shrink and inventory turns
8% historic loss
USDA's historical fish-and-seafood retail-loss estimate shows why overbuying and weak rotation can erase an otherwise healthy markup.
4
Labor and owner coverage
$22K/mo
The base payroll assumes the owner is the working buyer-manager; replacing that role with hired management reduces residual owner cash.
5
Cold-chain overhead
$10K/mo
Rent, electricity, refrigeration upkeep, insurance, cleaning, software, repairs, and permits create a fixed cash floor before owner pay.
6
Debt and reserves
33% reserve
The base case pays $2,250 of monthly debt service, then retains 33% of positive pre-reserve profit for taxes and reinvestment.
Want to test the assumptions in a full seafood-market forecast?
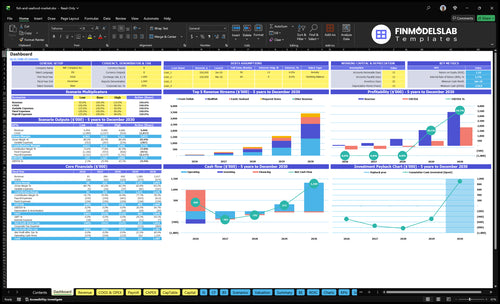
The dashboard preview shows how sales, gross margin, payroll, cash flow, scenario ranges, and financing interact over several years. That is useful when the owner-income question depends on more than one steady-state month, especially with holiday demand, seasonal species pricing, working-capital swings, and equipment spending.
The Fish And Seafood Market Excel Financial Model for Startups can be used to test whether a proposed ticket, customer count, product mix, payroll plan, and reserve policy still leave enough cash for the owner after the store pays its operating obligations.
How much revenue does a fish and seafood market need to pay the owner $8,000 a month?
In the base case, the market needs about $123,565 of monthly revenue, or $1.483 million annualized, to support an $8,000 monthly owner-pay target after the 23% tax reserve and 10% reinvestment reserve. That sales level is close to the reported $1.4 million average 2024 sales per fish-and-seafood-market location, but the planning result only works if the store actually achieves the modeled 39% gross margin and $36,250 monthly operating-cost base.
Before owner pay or reserves, the simpler operating break-even is about $92,949 per month: $36,250 of monthly operating costs divided by a 39% gross margin. Crossing that line does not mean the owner can safely take $8,000. The model first needs another $11,940 of pre-reserve profit to leave $8,000 after the 33% combined reserve. That distinction is why a shop can look "profitable" while still feeling cash-tight.
Base revenue math
$125,000 monthly sales
39% gross margin = $48,750 gross profit
$36,250 operating costs including debt service
$12,500 profit before modeled reserves
What supports the ticket
Planning assumption: about 91 daily tickets
Planning assumption: about $53 average ticket
26 selling days per month
Mix fresh seafood with frozen and prepared add-ons
How do spoilage and gross margin change what the owner keeps?
Shrink can turn a good markup into a weak owner draw. USDA's loss-adjusted food documentation reports an 8% retail loss estimate for fish and seafood in its 2010 table and notes that over-ordering and cold-storage failures cause retail loss. Because the estimate is old and supermarket-heavy, use it as an adjacent warning benchmark, not a current target for an independent shop.
Shrink is already embedded in the base 39% gross margin. At $1.5 million of annual revenue, one margin point is $15,000 before reserves and about $10,050 of owner cash after the base 33% reserve if other costs stay flat. Protect that margin with forecasting, receiving standards, fast rotation, and timely markdowns. The FDA Food Code is the national model for retail food safety, so local storage, monitoring, sanitation, and specialized-processing requirements also belong in the cost plan.
Protect realized margin
Track landed cost by species and supplier
Measure trim yield and unsold shrink separately
Markdown aging product before it becomes a total loss
Use frozen and prepared products to smooth mix
Do not confuse markup with margin
A 50% markup on cost is only a 33% gross margin
Freight and card fees reduce realized margin
Shrink belongs inside direct product economics
Employee payroll stays outside gross margin here
Can a fish and seafood market run without the owner at the counter?
Yes, but owner income usually falls before it becomes passive. The base model assumes the owner performs the buyer-manager role and excludes owner pay from the $22,000 monthly employee payroll. The May 2025 BLS national wage table reports median hourly pay of $18.41 for meat, poultry, and fish cutters and trimmers and $19.30 for butchers and meat cutters; experienced seafood staff or high-cost metros may require more.
If a manager-buyer adds $65,000-$80,000 of annual loaded cost, rerun payroll before treating the remaining cash as passive return. The IRS explains that S corporations must pay reasonable compensation to shareholder-employees for services before non-wage distributions. Do not count owner salary inside payroll and then add the same dollars again as a distribution.
Owner-operated economics
Owner handles buying and key vendor relationships
Owner covers schedule gaps and quality control
Employee payroll stays at $22,000 in the base case
Residual cash includes pay for the owner's labor
Manager-run economics
Add a market-rate manager or buyer cost
Keep owner distributions separate from wages
Require enough margin to cover replacement labor
Judge passive return only after management payroll
What do low, base, and high owner-income cases look like?
The scenarios below are intentionally asymmetric: lower sales keep a minimum fixed-cost base, while higher sales require more labor, overhead, marketing, financing capacity, and reinvestment. The base annual sales of $1.5 million is also meant to stay near observed industry scale rather than assume an outlier; the Census Bureau's 2023 fish and seafood market data provides a national anchor for the category. The exact owner-income figures reconcile to the calculator after each scenario's tax and reinvestment reserves.
Owner income scenarios
Compare a conservative owner-operated month, the base run rate, and a stronger-volume store with added staffing and financing capacity.
Low, base, and high planning cases for a U.S. owner-operated fish and seafood market.
Scenario factor
Low CaseConservative
Base CasePlanning
High CaseUpside
Launch modelOperating posture
Lean owner-operated store with slower traffic, a narrower fresh assortment, and tight staffing.
Stabilized owner-operated neighborhood market with a balanced fresh, frozen, and prepared mix.
High-volume market with a broader assortment, more staff, and larger financing and reserve needs.
Typical setupSales and margin
$85,000 monthly revenue
35% gross margin
$15,000 employee labor
$125,000 monthly revenue
39% gross margin
$22,000 employee labor
$185,000 monthly revenue
41% gross margin
$31,000 employee labor
Cost driversCash commitments
$8,000 fixed overhead
$1,000 marketing
$1,500 debt service
30% combined reserves
$10,000 fixed overhead
$2,000 marketing
$2,250 debt service
33% combined reserves
$13,000 fixed overhead
$3,000 marketing
$5,000 debt service
37% combined reserves
Owner income rangeAfter modeled reserves
$35,700Annual owner income
$100,500Annual owner income
$180,300Annual owner income
Best fitHow to use it
Stress-test a slower ramp, weaker mix, or smaller neighborhood catchment.
Plan a stabilized owner-operated store near observed industry sales scale.
Test stronger traffic and pricing only with the extra staff and capital required to support it.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What must be paid before owner cash is safe to distribute?
Safe owner cash remains only after vendors, employee payroll, rent, utilities, refrigeration and repairs, insurance, software, marketing, debt service, taxes, and reinvestment reserves are funded. The calculator subtracts full debt service because principal consumes cash even though it is not an income-statement expense. Its output is therefore different from EBITDA and accounting net income.
SBA says 7(a) loans can finance working capital, inventory, equipment, leasehold improvements, and acquisitions, with rates negotiated subject to program limits; see current SBA 7(a) loan terms. The base $2,250 monthly debt service is a planning assumption, not a quoted rate.
Keep the definitions separate: revenue is sales; gross profit is sales after direct seafood and transaction costs; owner salary pays for work; distributions pay for ownership. The calculator's owner-income output is a cash residual after modeled reserves. Because owner pay is not inside employee labor, do not add a separate owner salary on top of that output.
Key Takeaways
The base case produces $100,500 of annual owner cash from $1.5 million of sales after modeled tax and reinvestment reserves.
Operating break-even is about $92,949 per month, but supporting an $8,000 monthly owner target requires about $123,565 per month.
Shrink and species-level gross margin matter more than headline markup; each margin point is about $15,000 of annual gross profit at base sales.
The $100,500 output includes the economic value of the owner's buyer-manager labor; a manager-run store needs extra payroll before owner income becomes passive.
Which six fish and seafood market income drivers deserve weekly attention?
These six drivers explain most of the movement between the $35,700 low case and the $180,300 high case. They are linked: stronger traffic can improve buying leverage and labor productivity, but it can also create more waste, overtime, refrigeration load, and working-capital demand if the owner grows faster than the systems can handle.
1. Supplier buying, species mix, and realized gross margin
Buy to a landed-margin target
The base model assumes a 39% gross margin, meaning direct seafood, freight, packaging, card fees, and normal shrink consume 61% of sales. On a $125,000 month, that is $76,250 of direct cost and $48,750 of gross profit before payroll. NOAA notes that the United States relies heavily on foreign aquaculture imports and is one of the world's largest seafood importers, so species availability, freight, and global sourcing can change landed cost quickly.
Here's the quick math: if the owner improves realized gross margin from 39% to 40% without changing sales or operating costs, pre-reserve profit rises by $1,250 per month. After the base 33% reserve, that is about $838 more owner cash per month, or roughly $10,050 a year. The decision is not simply to raise prices; it is to protect margin by species while keeping enough value on the counter to sustain repeat demand.
Track landed margin by SKU
Use actual received weight and all landed charges, not the supplier's quoted case price alone.
Gross margin by species and preparation form
Supplier price variance week to week
Freight and packaging as a percent of sales
Markdowns and shrink inside realized margin
2. Daily transactions, average ticket, and repeat demand
Translate traffic into a daily sales requirement
NOAA reports 19.7 pounds of fish and shellfish consumption per person in 2022, but a specialty seafood market competes with supermarkets, clubs, restaurants, online sellers, and direct dock sales for that spending. The base model therefore uses a store-level transaction assumption rather than treating national consumption as automatic demand.
At 26 selling days, $125,000 monthly revenue is about $4,808 per day. A planning combination of roughly 91 tickets at a $53 average ticket produces about $125,398 per month. The low case is close to 70 tickets at $47, while the high case is close to 120 tickets at $59. Ticket growth is especially valuable when it comes from profitable add-ons, prepared seafood, sauces, frozen backup products, and larger family orders rather than discounting premium fresh fish.
Watch both halves of the sales equation
A rising average ticket can hide falling customer count, and rising traffic can be unprofitable if discounts destroy margin.
Daily tickets and sales by weekday
Average ticket by new versus repeat customer
Units per basket and prepared-item attachment
Repeat purchase rate over 30 and 90 days
3. Shrink, trim yield, and inventory speed
Treat unsold fish as a margin problem
The USDA's loss-adjusted food series includes an 8% historical retail loss estimate for fish and seafood. Because that estimate is based on older national data and large retailers, an independent shop should use it as a warning benchmark, not a target. A well-managed specialty market should measure its own receiving rejects, trim loss, markdowns, staff samples, donations, and disposals by species.
Shrink is already included in gross margin in this model. If the store buys $76,250 of direct product and transaction inputs in a base month, even a few thousand dollars of avoidable spoilage can wipe out the entire $375 monthly cushion above the $8,000 target owner pay. Fast rotation is therefore a cash policy: buy to a forecast, convert aging product into safe value-added formats where rules allow, and stop carrying slow species merely to make the display look broad.
Separate shrink from trim
Trim can become a sellable portion or prepared item; spoilage is usually a total economic loss.
Shrink dollars as a percent of seafood sales
Days of inventory by species
Yield from whole fish to sellable portions
Markdown recovery before discard
4. Skilled labor, schedule design, and the owner's role
Measure labor after assigning the owner's job
The May 2025 BLS wage release shows median hourly wages of $18.41 for meat, poultry, and fish cutters and trimmers and $19.30 for butchers and meat cutters. A seafood counter may pay above those national figures for experienced filleting, shellfish handling, early receiving, and customer-facing product knowledge, especially in expensive labor markets.
The base $22,000 monthly labor budget is a planning amount for employees before owner pay. It assumes the owner covers management, buying, quality decisions, and some floor time. If the store adds $5,000 per month of management coverage without raising sales or margin, base pre-reserve profit falls from $12,500 to $7,500. After the same 33% reserve, monthly owner cash falls to about $5,025. That is why "the business runs without me" is a financial milestone, not just a staffing preference.
Track labor dollars per sales dollar
Schedule against receiving peaks, Friday-Saturday demand, holiday orders, and prep volume rather than using the same staffing pattern every day.
Employee labor as a percent of sales
Sales per paid labor hour
Overtime and call-out coverage
Owner hours that would require paid replacement
5. Rent, refrigeration, and fixed cold-chain overhead
Keep the fixed cash floor visible
The base model carries $10,000 per month of fixed overhead for rent, utilities, refrigeration maintenance, insurance, cleaning, software, permits, repairs, and administration. That assumption excludes labor, marketing, and debt service, so it is intentionally narrower than a generic "all operating expenses" line. The refrigeration burden deserves special attention because a failure can create both a repair bill and an inventory loss.
Energy efficiency helps, but it does not remove the need for maintenance and backup planning. An EPA ENERGY STAR fact sheet says certified commercial refrigerators and freezers can be about 40% more energy efficient than standard models under the cited program criteria. For owner income, the bigger decision is total lifecycle cost: energy, service calls, gaskets, compressor risk, monitoring, and the value of stock exposed during downtime.
Budget the cold chain as a system
Low rent is not cheap if the site needs unreliable equipment, major electrical work, or frequent emergency repair.
Fixed overhead as a percent of sales
Electricity and refrigeration service by month
Emergency repair reserve and response time
Inventory value exposed to one equipment failure
6. Debt service, tax reserves, and reinvestment discipline
Do not distribute cash that the business still owes
The base case subtracts $2,250 of monthly debt service before computing owner income, then reserves 23% of positive pre-reserve profit for taxes and 10% for reinvestment. That leaves $8,375 a month for the owner from $12,500 of pre-reserve profit. The low case uses lighter debt and a 30% combined reserve; the high case uses $5,000 of debt service and a 37% reserve because a larger operation has more capital and working-capital exposure.
These reserve percentages are planning policies, not tax rates or legal requirements. A real owner may need a different tax reserve based on entity type, state, household income, and payroll treatment. Reinvestment should cover normal case replacement, refrigeration service, working-capital swings, and growth before the owner calls the remaining cash distributable. If the store repeatedly drains the reserve to make the owner's draw, the apparent income is partly liquidation of business liquidity rather than sustainable earnings.
Set a distribution gate
Pay distributions only after the next payroll, vendor cycle, debt payment, tax set-aside, and planned maintenance can still be funded.
Debt service coverage from operating cash
Tax reserve versus expected liability
Weeks of payroll and vendor cash on hand
Refrigeration and display-case replacement reserve
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Fish and Seafood Market Bundle
Choosing a selection results in a full page refresh.