How Much Grease Trap Cleaning Owners Make: $85K Pay To $169M Revenue
Grease Trap Cleaning Service Bundle
A grease trap cleaning business owner can model $85,000 in annual founder salary, but the business does not show positive EBITDA until the mature year This five-year view covers revenue, margins, operating costs, reserves, route economics, and owner take-home assumptions before personal tax choices
Owner income-$222k to $103kNet margin85.5% to 89.5%Revenue for target pay$1.69MBusiness difficultyHard
Want the six drivers behind owner take-home?
1
Recurring Base
$275-$1.2K
More signed accounts at the $275, $450, and $1,200 plan levels stabilize monthly cash and lift lifetime revenue.
2
Service Price
$450
Moving work into premium and enterprise plans raises revenue per stop and owner take-home.
3
Visit Rate
High
More cleanings per account lift annual revenue per customer without adding as many new leads.
4
Route Density
High
Tighter routes cut drive time and fuel, so each truck can finish more paid stops.
5
Disposal Cost
65%-45%
Grease waste fees fall from 6.5% to 4.5% of sales, which helps gross margin.
6
Truck Use
80%-60%
Higher truck and crew use spreads the $85K founder salary and fixed fleet load across more jobs.
Want to test your own owner pay case?
Owner income calculator
Estimate owner take-home and the target-pay gap for a grease trap cleaning service from monthly revenue, gross margin, labor, overhead, reserves, and pay goal.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice. The source model shows breakeven at Month 55, so use this to test pay capacity, not promise a draw.
Want to see the full Grease Trap Cleaning Service financial model?
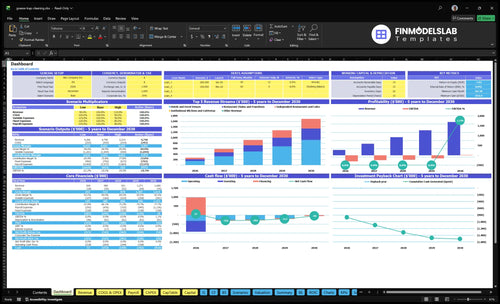
The Grease Trap Cleaning Service Financial Model Template shows the dashboard, revenue build, cost assumptions, payroll, capex, cash flow, owner pay, and break-even tabs; charts tie Year 1 revenue of $269k to Year 5 revenue of $1,690M, EBITDA from -$307k to $18k, and minimum cash of -$832k, with price plans, CAC, marketing budget, customer segments, FOG disposal, fuel and maintenance, fixed overhead, staffing, and capex built for scenario planning, not promised take-home pay. Open the model.
Owner-income model highlights
Owner pay is scenario-based
Revenue and EBITDA ramp
Scenario inputs drive break-even
Is grease trap cleaning profitable?
Yes, a Grease Trap Cleaning Service can be profitable, but only with dense recurring routes, tight pricing, and controlled disposal costs; see How Much To Start A Grease Trap Cleaning Service? before modeling startup cash. In the researched case, revenue grows from $269k to $1.690M, but EBITDA stays negative until Year 5, with breakeven around Month 55.
Profit Drivers
Build recurring restaurant accounts
Cluster stops by zip code
Protect price per service
Keep trucks fully used
Margin Risks
Long drive times erase margin
Payroll absorbs early cash
Marketing delays payback
Capex keeps EBITDA negative
How does an owner-operator model compare with hiring technicians?
For a Grease Trap Cleaning Service, the owner-operator model can boost short-term cash because the owner covers route labor, but it also caps how many routes and sales calls you can run. In Year 1, staffed-route economics already assume 2 service technician FTEs at $52,000 each, and by Year 5 that grows to 10 FTEs, or about $520,000 in annual salary. Hiring technicians usually lowers near-term take-home unless route utilization stays high, and scale only helps when trucks, techs, and route density can cover management, scheduling, insurance, repairs, and reserves.
Owner-operator fit
Owner absorbs route labor.
Short-term cash improves.
Sales time gets capped.
Capacity grows slower.
Hiring techs fit
Year 1 starts with 2 FTEs.
Year 5 reaches 10 FTEs.
Salary load hits $52k each.
Scale works only at high utilization.
What grease trap cleaning operating costs reduce owner income most?
The costs that cut owner income most in a What Are Operating Costs For Grease Trap Cleaning Service? setup are the direct job costs, not the office spend. FOG waste disposal and processing runs at 65% of revenue in Year 1 and still 45% in Year 5, while fuel and maintenance sit at 80% in Year 1 and 60% in Year 5. Fixed overhead is also heavy at $132k per month, and payroll rises from $254k to $874k by Year 5.
Direct job costs
FOG disposal: 65% Year 1
FOG disposal: 45% Year 5
Fuel and maintenance: 80% Year 1
Fuel and maintenance: 60% Year 5
Overhead and capex
Fixed overhead: $132k per month
Payroll: $254k to $874k
Vacuum truck fleet: $280k
Jetting equipment: $65k
Key Takeaways
Recurring accounts reduce churn and stabilize route revenue.
Price by service level, access, and after-hours work.
Frequency only helps if labor and trucks keep pace.
Dense routes cut costs and lift owner income.
Compare low, base, and high owner income scenarios
Owner income scenarios
Owner income depends on route density, staffing, and fixed overhead. Early ramp-up burns cash, while mature utilization can support founder pay and a small profit cushion.
Low, base, and high cases show how revenue and operating costs change owner take-home.
Scenario
Low CaseCash risk
Base CaseFunding gap
High CaseProfit cushion
Launch model
This is the lower-income path where early ramp-up keeps earnings tight.
This is the modeled mid-scale path with better volume but still weak owner take-home.
This is the stronger earnings path where mature utilization starts to cover the founder well.
Typical setup
Year 1 revenue is about $269k, gross margin is about 85.5% after FOG disposal and fuel, and EBITDA is about -$307k, so owner pay depends on outside funding.
Year 3 revenue is about $921k, gross margin is about 87.5% after disposal and vehicle costs, and EBITDA is about -$228k, so distribution capacity is still limited.
Year 5 revenue is about $1.69M, gross margin is about 89.5% after disposal and fuel, and EBITDA is about $18k, leaving only a limited cushion beyond the $85k founder salary.
Cost drivers
FOG disposal fees
vehicle fuel and maintenance
fixed overhead
slow route build
founder salary funding
FOG disposal fees
fuel and maintenance
technician payroll
dispatch overhead
limited capacity
Higher route density
lower disposal rate
lower fuel ratio
larger technician base
thin cash cushion
Owner income rangeBefore owner reserves
Up to $85,000Funding needed
Up to $85,000Salary only
$85,000+Small cushion
Best fit
Use this to stress-test the launch period and cash burn before volume scales.
Use this as the working plan for route growth without assuming strong cash returns.
Use this to test the upside case where the business finally funds owner pay and a small profit buffer.
!
Planning note: Scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Grease Trap Cleaning Service Core Six Income Drivers
Recurring Account Base
Recurring Account Base
A bigger recurring account base turns grease trap work into monthly recurring revenue instead of one-off jobs, which makes cash flow steadier and the owner’s pay easier to plan. In Year 1, the mix starts at 35% independent restaurants and cafes, 25% chains and franchises, 20% hotels and event venues, 15% institutional kitchens, and 5% food processing and industrial facilities.
The key metric is retention, because churn forces replacement sales and hurts route planning. Customer acquisition cost is $850 in Year 1 and falls to $550 by Year 5, so losing accounts means spending more just to stand still. Here’s the quick math: more retained contracts mean less CAC drag, fuller routes, and better margin available for owner draw.
Track Retention and Mix
Measure active contracts, monthly churn, new adds, and CAC by segment. The best estimate uses:
Active accounts by customer type
Monthly churn and reactivation rate
CAC: $850 to $550
Route fill and stop density
If churn rises, you replace revenue and lose route efficiency at the same time. That shows up fast in labor waste, empty truck miles, and less cash left after fixed costs.
Service Frequency
Service Frequency
Service frequency is how often each customer gets pumped and cleaned. It drives annual revenue per account and route workload. At $275 monthly, one account is worth $3,300 a year; at $450, it is $5,400; at $1,200, it is $14,400. More cleanings can mean more revenue, but only if labor, disposal, and truck time stay covered.
Keep the cadence editable
Track plan level, service interval, and billed stops by route. The main inputs are restaurant volume, kitchen type, grease output, and any local rule that changes the schedule. Here’s the quick math: revenue = price per plan × billed visits. If a site needs tighter cleaning, reprice it before adding visits, or margin and owner pay will get squeezed.
Watch billed visits by account
Track labor and disposal per stop
Reprice higher-frequency sites
Labor And Truck Utilization
Labor and Truck Use
Labor and truck utilization decide how much service revenue turns into owner pay. In Year 1, 2 FTEs at $52k each means $104k in payroll before repairs, insurance, and downtime. By Year 5, 10 FTEs and a $280k vacuum truck fleet plus $65k jetting gear can scale fast, but empty routes, idle labor, and weak dispatch pull cash away from the owner.
Track Billable Time First
Measure billable hours ÷ paid hours for labor and route days used ÷ route days available for trucks. That tells you if the business is buying growth or just buying idle capacity. Owner-operator savings help early, but once routes are staffed, full calendars matter more than adding gear.
Track downtime by truck.
Watch overtime before hiring.
Fill routes before adding fleet.
Disposal And Compliance Costs
Disposal Costs
FOG waste disposal and processing fees sit inside gross margin, so they cut the cash left after each service. Here’s the quick math: if disposal runs at 65% of revenue in Year 1 and improves to 45% by Year 5, every $10,000 of revenue keeps only $3,500 in Year 1 before fixed overhead. The driver depends on gallons hauled, facility fees, and haul distance.
Compliance also hits the P&L through $1,500 per month for professional services and compliance plus $3,200 per month for insurance and licensing. Approved facilities, manifests, recordkeeping, and local rules can change cash timing fast, so the owner’s take-home pay is only as strong as the gap between service pricing and these mandatory costs.
Track Local Rules
Use a local model, not a national average. Track disposal fee per load, compliance fee per stop, permit and insurance costs per month, and any extra time spent on manifests or documentation. If the route or city changes, rerun the margin math right away. A small fee change matters when disposal is already modeled at 65% of revenue early on.
Price contracts so compliant disposal is covered in every monthly fee, then test whether higher-volume routes lower the cost share toward 45%. If approved-facility access adds miles or delays, cash flow tightens before profit does. One missed assumption can wipe out owner draw, so keep the model adjustable by city, customer type, and route density.
Average Revenue Per Service
Average Revenue per Stop
Average revenue per service is the price you bill for each grease trap stop, and it’s a direct driver of route-day revenue and owner pay. In Year 1, the model uses $275 for basic compliance, $450 for premium service with drain jetting, and $1,200 for enterprise multi-location service. That means premium is $175 more than basic, so mix matters fast.
Price should move with trap size, access, after-hours work, emergency needs, and bundled drain work, not one flat “market rate.” By Year 5, those prices rise to $330, $550, and $1,500. If you underprice hard stops, revenue per route day drops while labor, disposal, and truck time stay high, which squeezes cash available for owner draw.
Price the Stop by Job Type
Track each stop by service type, time on site, and add-on work. Here’s the quick math: a premium stop at $450 should earn clearly more than a basic stop at $275, or the extra work isn’t paying for itself. If enterprise accounts are in the mix, make sure the price reflects multi-location admin and dispatch time.
Use a simple pricing sheet with these fields:
Trap size
Access difficulty
After-hours premium
Emergency fee
Drain jetting add-on
What this estimate hides: if pricing rules are loose, the team will discount hard stops and raise route cost without a matching revenue gain. Keep price overrides documented, then compare billed amount per stop against labor and disposal on every route.
Route Density
Route Density
Route density is how many billable stops fit into each technician day. For a grease trap cleaning business, tighter routes raise owner pay by cutting fuel, windshield time, overtime risk, and empty truck miles, so more of the day turns into paid service time.
Here’s the quick math: if vehicle fuel and maintenance are modeled at 80% of revenue in Year 1 and 60% in Year 5, weak density can eat most of the gross margin. Track stops per route, miles per stop, billable hours per technician day, and missed stops, because those inputs drive cash flow and the owner’s draw.
Pack Routes Tighter
Build routes by zip code and kitchen type, then measure truck utilization each week. The goal is simple: fewer dead miles, more serviced accounts, and less overtime. If one route is spread out, the hidden cost shows up in fuel, maintenance, and a day that looks busy but bills poorly.
Track miles per stop, service time per account, fuel cost per route, and missed-stop rate. Test whether adding nearby accounts lifts billable time faster than it adds drive time. If a route needs overtime or leaves unused truck capacity, density is too thin and take-home drops fast.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.