What Can an Owner Expect to Take Home from a Gymnastics Center?
Gymnastics Center Bundle
A U.S. owner-operated gymnastics center can realistically produce anywhere from $0 to about $256,000 a year of owner income across a weak-to-strong operating range. This article's base case produces $116,220 a year on $1.02 million of annual revenue after a modeled 25% tax reserve and 10% reinvestment reserve. The model assumes the owner serves as general manager, so owner pay is not included in payroll; the owner-income output therefore represents the combined cash capacity for compensation and distributions, not passive profit. The biggest constraints are coaching payroll, facility occupancy costs, debt service, class-seat utilization, and the cost of keeping equipment and programs current. The estimate is not a guaranteed salary and does not predict the owner's final personal tax bill.
Owner income$116KNet margin11%Revenue for target pay$1.03MBusiness difficultyHard
How much can a gymnastics center owner make in a stabilized year?
The modeled base case supports $116,220 of annual owner income after reserves, but that number needs the right definition. The operating scope here is a single, privately operated youth gymnastics instruction center in a suburban Central Ohio-style market, with recreational and preschool classes as the recurring core plus team programs, private lessons, camps, and events. That scope aligns with the U.S. Census classification for NAICS 611620 Sports and Recreation Instruction, which specifically includes gymnastics instruction, camps, or schools.
In the base case, $85,000 of monthly revenue becomes $79,900 of gross profit after a 6% planning allowance for non-labor direct costs. All payroll is separate. After $34,000 of employee payroll, $22,500 of fixed overhead, $3,500 of marketing, and $5,000 of debt service, the model has $14,900 per month left before owner reserves. A 25% tax reserve and 10% reinvestment reserve reduce that to $9,685 per month, or $116,220 per year, that is potentially available to the working owner.
Revenue, accounting profit, operating profit, salary, and distributable cash are not interchangeable. Revenue is top-line sales. Accounting profit follows the books and can include noncash depreciation; EBITDA excludes interest, taxes, depreciation, and amortization. Owner salary pays for work, while a draw or distribution moves equity cash to the owner. Safe distributable cash must also survive debt principal, taxes, capital needs, and reserves. Before debt service, the base case produces $19,900 per month of operating cash contribution after payroll, overhead, and marketing; this is a planning operating-profit proxy, not a claim of audited EBITDA. After $5,000 of monthly debt service, $14,900 remains before reserves. Only after reserves does the model arrive at owner cash. If the business is taxed as an S corporation, the IRS reasonable-compensation guidance matters because a shareholder-employee generally must receive reasonable compensation for services before non-wage distributions. In practice, part of the modeled owner cash may need to be wages and part may be distributions, depending on entity structure and tax advice.
What revenue supports a six-figure owner income?
With the base assumptions below, the center needs about $85,516 per month, or $1.026 million per year, to support a $10,000 monthly owner-income target after the modeled reserves. Simple operating break-even is lower: $65,000 of monthly operating costs divided by a 94% gross margin is about $69,149 per month. That break-even point covers the modeled business costs but leaves essentially no safe owner cash; target-pay revenue is the more useful threshold for an owner deciding whether the center can support a household.
Owner income calculator
Adjust revenue, margin, payroll, overhead, reserves, and debt to estimate residual owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Class-seat utilization
78% base
Filling recurring class capacity raises revenue faster than facility cost until another coach or time block is required.
2
Tuition & program mix
$110 blended
The model pairs recurring class tuition with higher-value team, private, camp, and event revenue.
3
Coaching labor efficiency
$34K/mo
Coach coverage must rise with filled classes, but overscheduling labor ahead of enrollment compresses owner cash quickly.
4
Facility revenue density
$22.5K/mo fixed
A large gym floor creates revenue capacity and a fixed monthly burden that does not disappear when attendance softens.
5
Direct-cost control
94% margin
The planning margin excludes payroll and leaves a 6% allowance for non-labor direct costs tied to sales and programs.
6
Retention & acquisition
$3.5K/mo
Keeping recurring enrollments reduces how much marketing must spend simply to replace normal student attrition.
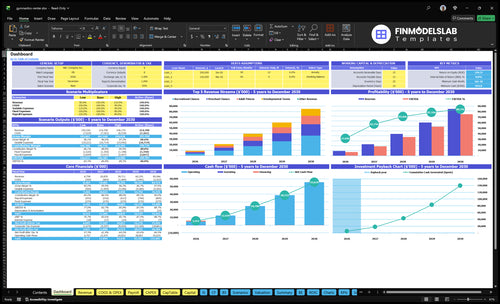
Want to test class fill, payroll, and owner pay in a full forecast?
The Gymnastics Center Five-Year Financial Model Template provides a business-specific dashboard for testing revenue streams, payroll, cash flow, and scenario changes. Use the preview to compare your own enrollment ramp, facility burden, debt, and reinvestment plan rather than treating any pre-filled result as an earnings promise.
How full do classes need to be before owner pay becomes safe?
A useful base target is roughly 620 recurring weekly seat-enrollments out of 800 planned places, or about 78% fill, before counting premium program revenue. This is a capacity assumption, not an industry rule. The schedule assumes about 100 one-hour class sections per week with eight places each; an actual U.S. operator publishes an 8:1 student-to-coach ratio for 60-minute recreational classes. At a $110 blended monthly tuition, 620 recurring seat-enrollments generate about $68,200 per month, with another $16,800 in the base case coming from team upgrades, multiple-class participation, private lessons, camps, events, and related programs.
Base class math
800 planned weekly places across about 100 class sections.
Can the center support a manager without cutting distributions?
Not automatically. The base model is owner-operated: the owner covers general-management work and is paid only through the residual owner-income output, while the $34,000 monthly labor line covers employee payroll. Hiring a full general manager without replacing owner labor economically means adding that manager's compensation to payroll; unless enrollment, tuition, or program mix also rises, owner distributions fall dollar for dollar before the reserve adjustment. National BLS data for coaches and scouts reports a 2024 median annual wage of $45,920 and notes that part-time work and irregular schedules are common, illustrating why a gymnastics center's staffing model often combines different schedules rather than a single uniform full-time template.
Owner-operated case
Owner handles general management, schedule decisions, vendor oversight, and financial review.
Employee payroll is $34,000 per month in the base case.
The resulting $116,220 annual owner income compensates both owner labor and ownership risk.
Manager-run case
Add the locally quoted manager wage, payroll taxes, and benefits to labor before calling any residual amount passive owner income.
Require added revenue or labor savings to fund that role instead of assuming distributions stay unchanged.
Keep owner salary, manager payroll, and owner distributions in separate accounting lines.
The broad Census sports-and-recreation-instruction category is a useful but imperfect labor cross-check because it includes activities beyond gymnastics. 2023 County Business Patterns data for the category reports substantial employment and payroll across U.S. establishments; the gymnastics base case deliberately runs employee payroll at 40% of revenue, a cautious level for a hands-on coached program. Staffing is also an operating-control issue: USA Gymnastics Safe Sport resources describe education and prevention-policy obligations that should be reflected in hiring, supervision, and administrative time rather than treated as zero-cost paperwork.
How should debt, taxes, and reserves change the owner's draw?
The base center should not distribute the entire $178,800 annual cash amount that remains after operating costs and debt. It first holds back $44,700 for the modeled tax reserve and $17,880 for reinvestment, leaving $116,220 for owner income. The $60,000 of annual debt service has already been paid before those reserves. This sequencing matters because equipment, repairs, working capital, and tax obligations can consume cash even when the income statement appears profitable.
Base annual cash bridge
$1.02 million revenue becomes $958,800 gross profit under the 94% planning gross margin.
Employee payroll, fixed overhead, marketing, and debt service leave $178,800 before owner reserves.
$62,580 of modeled tax and reinvestment reserves leave $116,220 of owner cash.
Before a distribution
Confirm payroll, rent, debt, tax deposits, and near-term equipment needs are funded.
Keep a working-capital cushion for seasonal enrollment swings and refunds.
Separate entity-level cash availability from the owner's personal tax obligation.
Financing can help with buildout, equipment, and working capital, but it also creates a fixed claim on cash. The SBA 7(a) program overview identifies uses including leasehold improvements, equipment, and working capital, with loan terms varying by use. The article therefore models debt service explicitly instead of hiding it in overhead. The 25% tax reserve is only a planning holdback, not tax advice, and it should be replaced with an estimate from the owner's tax professional.
Key Takeaways
The base owner-operated center generates $116,220 of annual owner income after modeled reserves on $1.02 million of revenue.
Operating break-even near $69,149 per month is not the same as revenue sufficient for a $10,000 monthly owner-income target.
Class fill, tuition mix, and coach scheduling matter more than headline enrollment alone.
Debt, taxes, equipment reinvestment, and owner-role replacement cost must be funded before treating residual cash as a safe distribution.
What do low, base, and high owner-income cases look like?
The three cases below use the same formulas and change costs along with revenue. The low case keeps minimum facility and staffing burdens even as sales fall; the high case adds coaching payroll, overhead, and marketing to support higher utilization. These are planning cases, not a forecast. Broad U.S. demand context can be checked against the Census Annual Integrated Economic Survey for Sports and Recreation Instruction, but local enrollment, tuition, and facility economics should drive an actual gym forecast.
Owner income scenarios
Three internally consistent operating cases using the calculator presets.
Low, base, and high planning cases for a single owner-operated gymnastics center.
Scenario dimension
Low CaseRamp stress
Base CaseStabilized
High CaseStrong fill
Launch modelRevenue and owner role
$55,000 monthly revenue; owner-GM; ramp case stays below break-even.
Owner income rangeAfter modeled tax and reinvestment reserves
$0
$116,220
$255,600
Best fitPlanning use
Stress test for weak enrollment or a slow first-year ramp.
Owner-operated center reaching stable recurring enrollment.
High-utilization case that funds the staff and marketing needed for more volume.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six income drivers matter most for a gymnastics center?
The six drivers below connect operating decisions to cash that can safely reach the owner. They use the same base model as the calculator, with Central Ohio pricing and rent observations where available and national sources only as broader cross-checks. Replace each planning assumption with the center's actual schedule, payroll register, lease, processor statement, and retention data before making a distribution decision.
1. Class-seat utilization
Fill existing coached hours before adding more
A gymnastics center monetizes coached floor time, not just square footage. The base schedule assumes 100 weekly class sections with eight places each, consistent with the published 8:1 recreational class ratio at Texas Twisters. Filling 620 of 800 weekly places produces 77.5% utilization. At $110 of blended monthly tuition, those recurring enrollments generate about $68,200 each month before premium programs. If fill rises by 10 percentage points, 80 additional seat-enrollments are worth roughly $8,800 a month before extra coach payroll and direct costs.
The key is contribution from an added student, not a vanity occupancy rate. If a class already has a coach and safe capacity, the next enrollment can have strong incremental economics. If that student forces a new class section, the wage cost arrives in a step. Owner income improves most when the schedule shifts demand into underfilled existing sections.
Track utilization by class block
Use a weekly schedule report rather than one center-wide fill rate.
Filled places divided by sellable places.
Waitlist count by day and level.
Revenue per coached hour.
Contribution after coach cost for each added section.
Here's the sensitivity: a $5 increase in blended monthly tuition across 620 recurring seat-enrollments adds about $3,100 of monthly revenue if retention holds. In the base model, the center also needs about $16,800 per month from team upgrades, multi-class enrollments, privates, camps, events, and related programs to reach $85,000. Premium programs should fill unused facility windows or earn enough contribution to justify dedicated labor.
Track realized price, not the rate sheet
Discounts, siblings, makeup policies, and multi-class packages can pull collected tuition below list price.
Collected recurring revenue per active seat-enrollment.
Premium-program revenue as a share of sales.
Discount dollars and refund dollars.
Retention after each price change.
3. Coaching labor efficiency
Schedule coaches against paid capacity
The base case spends $34,000 per month on employee payroll, equal to 40% of $85,000 revenue, with the owner acting as general manager outside that payroll line. The national BLS coach-and-scout occupation profile cited above reports a 2024 median annual wage of $45,920 and notes part-time and irregular schedules are common. That national figure is not a gymnastics wage quote; it is a labor-market cross-check for a business that must cover afternoons, evenings, weekends, team practices, and peak enrollment windows.
If payroll rises $2,000 per month with no revenue change, profit before reserves falls by the same $2,000. With the base 35% combined reserve rate and positive profit, owner cash falls by about $1,300 per month, or $15,600 per year. That is why adding coaches ahead of enrollment can erase distributions even when the center looks busy.
Measure labor against coached revenue
Separate necessary coverage from idle paid time.
Payroll as a percentage of revenue.
Revenue per paid coaching hour.
Students per coach by program and risk level.
Overtime, substitute, and unfilled-shift costs.
4. Facility revenue density
Make the large fixed box earn throughout the week
A gymnastics facility needs height, clear spans, equipment zones, viewing areas, and parking, so rent is often a major fixed commitment. As an adjacent Central Ohio proxy rather than a gymnastics-specific quote, the Colliers Q1 2026 Columbus industrial flex report shows average asking rent of $10.21 per square foot NNN. Applied to the model's 18,000-square-foot planning footprint, that is about $15,315 per month of base rent before NNN pass-throughs, utilities, insurance, cleaning, repairs, software, and administration. The full fixed-overhead assumption is $22,500 per month.
At $1.02 million annual revenue, the base center produces about $56.70 of annual revenue per square foot. At the low case's $660,000 annual revenue, that drops to about $36.70 while most space cost remains. Camps, preschool daytime sessions, adult programs, privates, and events can improve revenue density when they use hours the lease is already paying for.
Track what the building earns
Space should be measured as productive capacity, not simply as a lease expense.
Revenue per square foot per year.
Prime-time versus off-peak floor utilization.
Occupancy cost as a percentage of revenue.
Revenue added before taking more square footage.
5. Direct-cost control
Keep gross margin compatible with the payroll model
The 94% base gross margin is a planning assumption, not a published gymnastics-center industry margin. It means 6% of revenue, or $5,100 per month at $85,000 of sales, is reserved for non-labor direct costs such as payment processing, program consumables, small merchandise cost, and refunds. All coach and staff payroll is intentionally excluded from gross margin and shown in the separate labor line, preventing the same labor from being deducted twice.
Margin sensitivity is meaningful even when the percentage looks small. One percentage point of gross margin on $85,000 monthly revenue equals $850 of monthly profit before reserves. With the base 35% combined tax and reinvestment reserve, that is about $553 of monthly owner cash, or roughly $6,630 per year, while profit remains positive. Operators should replace the 6% assumption with processor statements, merchandise cost, refund history, and program-specific supplies.
Reconcile direct costs monthly
Use a consistent definition so gross margin never absorbs costs already modeled elsewhere.
Card and payment fees as a percentage of collected sales.
Refunds and credits by program.
Merchandise cost versus merchandise revenue.
Gross margin before every payroll dollar.
6. Retention and acquisition
Protect recurring tuition before buying replacement leads
The base case reserves $3,500 per month for marketing, about 4.1% of revenue. That is a planning budget rather than an industry benchmark, and it should be judged by retained enrollments, not clicks. For example, if a center with 620 recurring seat-enrollments experiences 3% monthly attrition as a planning stress assumption, it must replace about 19 enrollments simply to stand still. Spending $3,500 to replace 19 would equal about $184 of marketing spend per replacement before accounting for referrals and organic leads.
The downside math is just as useful. Losing 20 recurring enrollments at $110 each removes $2,200 of monthly revenue. Because lease and much of the near-term schedule remain fixed, that revenue loss can flow quickly into owner cash until management is able to consolidate classes or cut labor. Retention therefore links customer experience, coach consistency, schedule availability, and financial distributions more tightly than a one-time enrollment campaign does.
Track the enrollment replacement burden
A growing center should know whether marketing creates new capacity use or merely replaces churn.
Monthly starts, stops, and net enrollment change.
Trial-to-paid conversion rate.
30-day and 90-day retention.
Acquisition cost per retained enrollment.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.