How Much High Mast Lighting Owners Make on $11M–$52M Revenue
High Mast Lighting Installation Bundle
A high mast lighting installation business owner can plan around $145k of role-based pay if they fill the general manager seat, but first-year distributions are not supported in this model because EBITDA is -$267k on $1083M revenue Revenue grows to $3128M in Year 3 and $5154M in Year 5, but owner take-home depends on direct cost control, payroll, overhead, debt service, and cash reserves Here’s the quick math: contracted revenue minus job costs, wages, marketing, fixed overhead, reserves, and reinvestment equals cash available to the owner These are researched planning assumptions, not guaranteed income
Owner income$145kNet margin-25% to 34%Revenue for target pay$432kBusiness difficultyHard
What drives owner income most?
1
Contract Volume
$1.1M-$5.2M
More awarded projects move revenue from Year 1 to Year 5 and create the biggest lift in owner take-home.
2
Rate Mix
$150-$325/hr
Shifting more work into higher-rate installs and emergency calls lifts revenue per billable hour.
3
Job Costs
24%-30%
Keeping materials, subcontracting, fuel, and insurance tight protects EBITDA as volume grows.
4
Utilization
140-200 hrs
Higher billable hours spread crane, truck, and crew costs across more revenue.
5
Overhead Load
$300K/yr
The fixed base and rising payroll set the break-even floor and cap owner pay.
6
Cash Timing
-$174K
The month 16 cash dip means billing speed and reserves decide how much profit is actually usable.
Want to test your owner take-home?
Owner income calculator
Estimate owner take-home and the target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: This is a researched planning estimate, not guaranteed salary, tax advice, or owner distribution advice. Actual owner income depends on project mix, labor, taxes, financing, and reserve policy.
Need to check owner income in the full model?
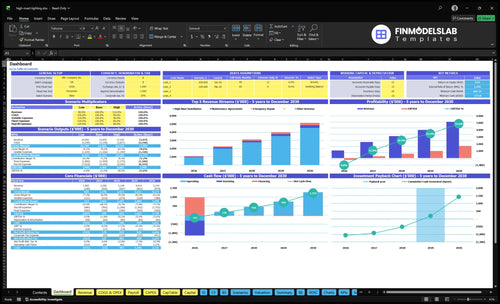
Yes — the High Mast Lighting Installation Financial Model Template shows the full dashboard: revenue, EBITDA, minimum cash, owner pay, payroll, direct costs, capex, reserves, and scenario charts. It also ties the assumptions to Year 1 revenue of $1.083M, Year 5 revenue of $5.154M, -$267k Year 1 EBITDA, -$174k minimum cash, $825k launch capex, and $145k GM compensation, so open the model and review the planning path.
Owner-income model highlights
Tracks owner take-home
Shows EBITDA and cash
Tests pricing and wages
Can a high mast lighting contractor owner make more by scaling crews?
Yes—High Mast Lighting Installation can make more by scaling crews, but only with qualified crews, equipment access, bonding capacity, safety systems, and working capital. An owner-in-field model protects margin but caps project volume; a project-manager owner can handle more work but adds office and supervision load. Multi-crew growth can reach $5,154M in Year 5 revenue, but payroll also rises to $1,348M and cash timing still matters.
When scaling works
Qualified crews keep jobs moving
Equipment access cuts idle time
Bonding capacity opens public work
Safety systems protect margin
What slows scale
Owner-in-field caps project volume
Public-sector payment cycles delay cash
Retainage ties up profit
Reinvestment keeps crews working
How much revenue does a high mast lighting business need to pay the owner?
For High Mast Lighting Installation, the owner can’t pay themselves from revenue alone. To hit a $145k owner draw, gross profit has to first cover field payroll, marketing, $300k in fixed overhead, reserves, and debt service; in this model, $1.083M in Year 1 is not enough, and even $3.128M in Year 3 still gets squeezed by $1.033M of payroll. Revenue helps, but cash flow is the real test.
Owner pay math
$145k is the target owner pay
Gross profit must fund that first
$300k fixed overhead comes next
Year 1 $1.083M falls short
Cash traps
Retainage delays cash collection
Crane costs hit margin fast
Labor hours drive direct cost
Bonding can trap working capital
How much can a high mast lighting installation owner make?
A High Mast Lighting Installation owner can make $145k if they fill the general manager role, but Year 1 owner distributions are not supported because EBITDA is -$267k; for startup cost context, see How Much To Open High Mast Lighting Installation Business?. Income rises only when completed profitable projects, billing, utilization, and collections outpace payroll and overhead.
Owner Pay Math
$145k role-based general manager pay
-$267k Year 1 EBITDA
No Year 1 distributions supported
Profit depends on completed projects
What Drives Income
Revenue grows $1.083M to $5.154M
Payroll grows $589k to $1.348M
Improve gross margin before overhead rises
Bids submitted don’t create owner income
Key Takeaways
More jobs help only when gross profit beats overhead.
Bigger scopes raise revenue, but cash risk climbs.
Track direct costs by job to protect margin.
Keep reserves first; distributions come after working capital.
Scenario objective: Compare lean, base, and high-output owner income cases without promising a salary
Owner income scenarios
Owner income swings because this work is labor-heavy, equipment-heavy, and cash can run negative before scale kicks in. Profit improves fast once revenue clears the fixed crew and fleet load.
Low, base, and high cases show how pay changes as project volume and margin scale.
Scenario
Low CaseCash risk
Base CaseLabor intensity
High CaseEquipment intensity
Launch model
Year 1 ramp keeps owner income tight, with no planned distribution and salary only if outside funding covers it.
Year 3 scale gives the owner a steadier income path as EBITDA turns positive.
Year 5 scale gives the owner the strongest income path, with more room for draw and reserves.
Typical setup
At $1.083 million revenue, 30.0% direct costs, $589k payroll, $45k marketing, and $300k fixed overhead, EBITDA lands at -$267k.
At $3.128 million revenue, 27.2% direct costs, $1.033 million payroll, $80k marketing, and $300k fixed overhead, EBITDA reaches $631k.
At $5.154 million revenue, 24.4% direct costs, $1.348 million payroll, $110k marketing, and $300k fixed overhead, EBITDA reaches $1.734 million.
Cost drivers
Payroll load
startup overhead
negative EBITDA
no distribution
Crew size
project mix
marketing spend
fixed overhead
Fleet utilization
crane demand
labor scaling
cash retention
Owner income rangeBefore owner reserves
-$267,000Reserve need
$631,000Margin build
$1,734,000Cash buffer
Best fit
Best for founders stress-testing launch cash and reserve needs.
Best for operators modeling a working, funded growth year.
Best for teams testing full-scale execution and capital needs.
!
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
High Mast Lighting Installation Core Six Income Drivers
Annual Contracted Project Volume
Annual Project Volume
More completed projects can lift revenue from $1.083M in Year 1 to $5.154M in Year 5, but only if the work is profitable. This driver is not bid count; it is finished jobs that clear crews, bonding, crane access, materials, safety coverage, and payroll timing.
Here’s the quick math: marketing rises from $45k to $110k, while CAC falls from $7,500 to $6,200. That helps owner income only when added gross profit beats the extra payroll and overhead. What this hides is cash timing: payroll and equipment costs can hit before collections do.
Track Finished Work Profit
Measure awarded jobs, completed jobs, gross profit per job, and days to collect. A clean rule: do not chase more volume unless each finished project still covers field labor, crane time, safety coverage, and admin load.
Track completions, not bids.
Price crane and safety separately.
Hold payroll cash first.
Test CAC by channel.
Overhead And Compliance Burden
Overhead And Compliance Burden
This business can win work and still leave little owner cash if fixed overhead stays at $25k/month or $300k/year. That base includes the yard and office lease, general liability and workers comp, certifications and FAA fees, utilities, software, GPS tracking, and admin supplies.
Here’s the quick math: payroll adds $589k in Year 1 and grows to $1,348M by Year 5. So even “profitable” jobs can still leave thin owner income if estimating, compliance, insurance, bonding, vehicles, and office costs are too heavy.
Build Overhead Into Bids
Price overhead recovery into every bid, not after the fact. Track billable hours, overhead per month, and job margin by project so you can see if each contract is funding the fixed load plus owner pay.
Track overhead as a monthly percent of revenue.
Separate job costs from fixed costs.
Test bids against overhead recovery per hour.
Watch compliance, insurance, and vehicle costs.
Cash Flow, Retainage, And Reserves
Cash Flow and Retainage
Accounting profit can look fine while cash goes negative. In this model, minimum cash hits -$174k in Month 16, so a project-heavy contractor can still run short when public jobs pay slow and hold retainage.
That risk comes from retainage (money withheld until closeout), upfront materials, payroll before customer payment, insurance, bonding, and equipment debt. If cash timing slips, owner draws have to wait; pay the company first when working capital is tight.
Track Cash Before Owner Pay
Watch days sales outstanding (days to collect cash), retainage %, weekly payroll, material deposits, and debt service. Build a 13-week cash forecast from billed work, expected collections, and required outflows so you can see gaps before they hit.
Keep a reserve sized for slow pay and closeout delays. Use that reserve before any owner distribution, then set a rule for draws only after payroll, materials, insurance, and bonding are covered. Cash pays the bills, so profit alone is not spendable income.
Track collections by project.
Separate retainage from cash.
Fund payroll first.
Delay owner draws if short.
Direct Job Cost Control
Direct Job Cost Control
Direct job cost control is the gap between what each high-mast project should cost and what it actually costs. The model shows direct cost load at 300% of revenue in Year 1, easing to 244% in Year 5. That means raw materials, components, subcontracted heavy lifting, fuel, maintenance, and project insurance can wipe out margin fast, so owner pay depends on tight job-level control.
Here’s the risk: a missed crane window, wrong pole delivery, overtime, rework, or a traffic-control change hits gross margin before fixed overhead is even covered. One bad job can erase several good ones. If you only watch monthly totals, you miss which crew, site, or change order caused the leak.
Track Every Job Cost
Track costs by job, not just by month, and compare budget to actual after each lift, delivery, and shift. Build each estimate from the main inputs: raw materials, components, subcontracted lifting, fuel, maintenance, insurance, and change orders. The owner’s take-home rises only when actual cost stays below the bid allowance.
Keep separate codes for crane time, traffic control, rework, and overtime so you can price future bids better. Clean job costing improves cash and protects profit draw. A project that looks busy can still pay poorly if direct costs keep running above plan.
Average Contract Value And Scope Mix
Average Contract Value and Scope Mix
When your average package grows, revenue can rise fast, but so can cash strain. The model uses 320 hours per high-mast job at $185/hour in Year 1, or $592k before scope changes, then $210/hour and $672k in Year 5. Bigger scopes can add poles, foundations, controls, traffic work, airport rules, and more heavy lifting.
The trap is pricing every job the same. Larger contracts usually bring more materials, retainage, and working capital risk, so owner pay depends on how well the bid matches specs, procurement terms, and actual field conditions. One bad scope assumption can wipe out the margin on an otherwise strong contract.
Price by Scope, Not by Habit
Track each bid by scope bucket, not just total contract value. Separate hours, materials, traffic control, airport work, and foundation work, then compare bid margin to actual job cost. Here’s the quick check: if the scope adds complexity but not price, the owner is funding the gap.
Log retainage terms on every bid.
Test pricing by scope line.
Flag change orders early.
Match price to procurement terms.
Watch cash, not just profit. A larger contract can grow top-line revenue, but slow pay and retainage can delay owner draws if materials and payroll land before collection. If a job needs more heavy equipment or longer billing cycles, build that into the price before you sign.
Crew And Equipment Utilization
Crew And Equipment Utilization
Utilization is paid productive time versus idle time. In high mast work, that means electricians, crane operators, bucket trucks, mobile crane access, foundation drilling, testing gear, and service vehicles staying on billable work instead of waiting on the next lift. The asset base here is about $825k across the bucket truck, mobile crane, service fleet, drill rig, testing equipment, tools, and IT gear, so every idle day pushes cost per job up and cuts owner take-home.
Here’s the quick math: if a crane window is missed or a pole is late, the job can add rental waste, overtime, and delay costs before any new revenue shows up. Better scheduling lifts contribution by turning fixed equipment and crew time into billable hours. One clean rule: raise utilization before you buy more gear.
Track Crew And Equipment Use By Job
Track billable hours, idle hours, rental days, overtime, and equipment downtime by project, not by month. That shows which jobs are burning margin. If a lift needs a crane, bucket truck, and drill rig, line up the window first, then crew it. Poor sequencing can turn a profitable scope into thin contribution fast.
Use schedule controls that reduce waiting: confirm access dates, stage materials early, and match the right crew to the right equipment. The goal is simple: more paid productive time with the same assets. More utilization means more profit without new sales, and that is what funds owner pay.
Measure paid hours vs idle hours
Flag rental and overtime overruns
Match crane, truck, and crew timing
Review job-level equipment downtime
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.