What Revenue Supports Owner Pay in an In-Home Daycare?
In-Home Daycare Bundle
A licensed, owner-operated in-home daycare in the United States can realistically produce about $35,000 to $63,000 a year of owner income after modeled tax and reinvestment reserves in the low-to-high cases used here, with a base case of about $49,000 on $124,200 of annual revenue. The base model assumes roughly 8.5 full-time-equivalent enrollments, a blended tuition rate near $1,150 per child per month, modest food-program reimbursements, an 89% gross margin before payroll, part-time paid help, and home-based overhead. That tuition level sits within the broad range implied by Child Care Aware of America’s 2025 family child care price data. The owner-income figure is not revenue, EBITDA, or guaranteed salary: it is residual cash after direct costs, paid staff, fixed overhead, marketing, debt service, and a 20% tax reserve plus an 8% reinvestment reserve. It excludes the owner’s personal health insurance, retirement contributions, household spending, and any tax liability above the modeled reserve.
Owner income$49KNet margin39%Revenue for target pay$123KBusiness difficultyModerate
What does a realistic in-home daycare owner-income model look like?
The useful starting point is a cash model, not a headline “profit margin.” This article models a sole-proprietor-style, licensed family child care home in which the owner provides care and administration, so the owner is not included in payroll. That treatment matches the basic tax distinction in IRS Publication 334: a sole proprietor cannot deduct their own salary or personal withdrawals as a business expense. Paid assistants are labor cost; owner take-home is the residual after the business pays its other obligations and reserves cash. If the business is taxed as an S corporation or has a hired manager, the compensation structure must be rebuilt rather than copied from this model.
Use the calculator to stress-test the same low, base, and high cases. Gross margin is the share left after food, learning supplies, merchant fees, and other non-labor direct costs; payroll is separate. “Profit before reserves” is a cash-planning residual after debt service, not EBITDA or GAAP profit. Debt principal consumes cash even though it is not an accounting expense, so accounting profit and cash safe to distribute can differ.
Owner income calculator
Estimate owner take-home and target-pay revenue from enrollment-driven sales, costs, staffing, debt, and reserves.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What moves in-home daycare owner income fastest?
Capacity is the hard ceiling, but utilization, tuition, and staffing determine whether that ceiling produces owner cash. State rules can change the economics sharply: California, for example, distinguishes small homes of up to six children, or eight when criteria are met, and large homes of up to 12, or 14 when criteria are met, according to California child care guidance. Texas likewise caps licensed child care homes at 12 children under its current child care permit guidance. The model therefore treats 12 as a high-case ceiling only where the local license, age mix, home configuration, and required assistant coverage allow it.
1
Enrollment & licensed capacity
8.5 / 12 slots
The base case averages 8.5 full-time-equivalent children. Every filled permitted slot spreads home overhead across more tuition, but age limits and ratios can make the nominal license capacity unusable without help.
2
Tuition & age mix
$1,150/mo
The blended base tuition is a planning rate near national family-child-care price benchmarks. Infant-heavy enrollment may support a higher rate but can also constrain capacity and staffing.
3
Staffing & owner coverage
$1.6K/mo
Part-time assistant payroll protects ratios, breaks, and continuity. Adding staff before enrollment supports it can erase the owner’s distribution; under-staffing can make legal capacity unusable.
4
Direct costs & CACFP
89% GM
The base keeps food, supplies, processing, and other non-labor direct costs near 11% of revenue. Eligible meal reimbursements help offset food cost but should not be treated as free margin.
5
Home overhead & compliance
$1.5K/mo
Insurance, licensing, training, cleaning, utilities, repairs, software, and the business share of home occupancy create a real fixed floor even when a child leaves mid-month.
6
Collections, debt & reserves
28% reserve
The base holds back 20% for taxes and 8% for reinvestment after debt service. A daycare can show profit and still lack safe distribution cash if tuition arrives late or reserves are skipped.
Want to test enrollment, tuition, and staffing in a full forecast?
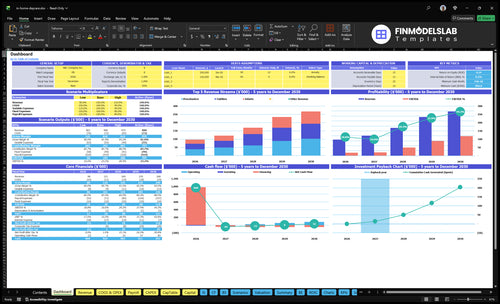
The Editable In Home Daycare Financial Model in Excel includes a business-specific dashboard and scenario views. The screenshot is useful for testing how enrollment, tuition by age, payroll, direct costs, cash balance, and owner-income assumptions interact over several years rather than one steady-state month.
Use the dashboard as a planning workspace, not as an earnings promise. Replace the built-in assumptions with your state license capacity, local tuition, actual insurance quotes, assistant hours, debt terms, and reserve policy before making a hiring or draw decision.
How many enrolled children does it take to pay the owner?
In the base case, about 8.5 full-time-equivalent enrollments at a blended $1,150 monthly tuition, plus about $575 of monthly food-program and ancillary revenue, are enough to produce roughly $4,077 of monthly owner income after reserves. The tuition assumption is deliberately anchored to the 2025 market: Child Care Aware of America reports family child care annual prices ranging from roughly $10,572 to $14,045 across its national averaging methods for infants and four-year-olds, visible in its 2025 price methodology. Local rates can be far outside that national range, so substitute your own market rate before relying on the output.
Infant and toddler limits can reduce usable capacity
Your own young children may count toward capacity in some states
Part-time children create scheduling gaps unless days align
One vacancy can cut revenue faster than costs fall
The operating cash break-even is much lower than the owner-pay break-even. With $3,550 of monthly labor, overhead, marketing, and debt service and an 89% gross margin, the business covers those cash obligations at about $3,989 of monthly revenue. But that point pays the owner nothing. To support the base target of $4,000 monthly owner take-home after the 28% combined reserve, the calculator requires $10,231 of monthly revenue, or about $122,772 annually. That is the more useful threshold for deciding whether a daycare is economically worthwhile for an owner who works in it full time.
What margin supports a safe owner draw?
A home daycare can show a strong gross margin and still produce mediocre owner income because payroll and fixed home costs sit below gross profit. The base model uses an 89% gross margin, meaning 11% of revenue is consumed by non-labor direct costs. Food reimbursement can offset part of that burden: for July 2025 through June 2026, the USDA’s published day-care-home rates for the contiguous states run from Tier II to Tier I amounts of $0.61 to $1.70 for breakfast, $1.94 to $3.22 for lunch or supper, and $0.26 to $0.96 for a snack, according to the 2025-26 CACFP Federal Register notice.
Base monthly cash bridge
$10,350 revenue
$9,212 gross profit at 89%
$3,550 paid labor, overhead, marketing, and debt
$5,662 cash profit before reserves
Safe distribution filter
$1,585 held for tax and reinvestment reserves
$4,077 modeled monthly owner income
39% owner-income margin, not GAAP net margin
Delay extra draws when repairs or enrollment losses are known
At base revenue, one gross-margin point is about $104 per month of gross profit, or roughly $75 of owner cash after the 28% modeled reserve if nothing else changes. A $500 monthly increase in paid staffing cuts owner income by roughly $360 after the base reserve. Assistant hours therefore need enough enrollment or tuition behind them to pay for themselves.
Key Takeaways
The base case produces about $49,000 of annual owner income after reserves on $124,200 of revenue.
Cash operating break-even is only about $4,000 per month, but owner-pay break-even is about $10,231 per month.
Licensed capacity and age mix set the revenue ceiling; assistant coverage determines how much of that capacity is actually usable.
Owner draws are safe only after payroll, home overhead, marketing, debt service, taxes, and a replacement reserve are funded.
Can an in-home daycare run without the owner?
Not at the economics modeled here. The base case is an owner-operator model: the owner is the primary caregiver, enrollment manager, parent-contact point, and administrator, while $1,600 a month covers part-time paid help and payroll burden. May 2025 BLS data put the national median hourly wage for childcare workers at $16.82, with a mean annual wage of $35,030, in the BLS Occupational Employment and Wage Statistics release. A full-time replacement caregiver or manager can therefore consume most or all of the base owner income before benefits, payroll taxes, and additional management pay are considered.
Owner-operated case
Owner performs the primary caregiving role
Assistant payroll is $1,600 per month in base
Owner income is residual cash, not a payroll expense
Owner hours should still be tracked as an economic cost
Manager-run reality
Add a lead caregiver or manager before distributions
Expect payroll burden beyond hourly wage
Higher capacity may require additional adults anyway
Passive ownership needs materially more revenue or scale
This does not mean owner labor is “free.” The calculator combines the reward for the owner’s labor and ownership because owner pay is residual. To estimate passive ownership income, add a market-rate lead caregiver or manager to labor cost first; any remaining owner income is closer to a distribution. In the base case, that residual may be small.
How should a daycare owner separate salary, profit, and cash?
Start by separating the words. Revenue is tuition and other business income. Gross profit is revenue after direct food, supplies, and processing costs. Operating or accounting profit follows accounting rules and may include depreciation and interest in ways that differ from cash flow. EBITDA excludes interest, taxes, depreciation, and amortization, so it is not the same as this calculator’s cash residual. For a sole proprietor, owner draw is not deductible salary: the IRS states in Publication 334 that a sole proprietor cannot deduct their own salary or personal withdrawals. The model therefore keeps owner pay out of labor cost and calculates take-home only after other cash demands.
What the P&L can tell you
Whether tuition covers direct costs and paid staff
Whether recurring overhead is sustainable
Whether price and enrollment produce operating profit
Whether a hired manager would still leave profit
What safe cash must still cover
Loan principal and interest
Estimated tax payments
Safety repairs and equipment replacement
Enrollment gaps and delayed collections
The 20% tax reserve in the base case is only a planning holdback. Self-employed owners can owe federal income tax and self-employment tax and may need estimated payments; the mechanics are described in IRS Publication 505 for 2026. Your actual reserve depends on filing status, other household income, entity choice, state taxes, credits, and deductions. The right draw policy is therefore not “take the profit.” It is: pay direct costs and employees, pay fixed bills and debt, set aside taxes, retain a repair and working-capital reserve, then distribute only the cash left above that floor.
Compare low, base, and high owner-income scenarios for planning
The three cases are built from the same revenue logic but change capacity use, tuition, staffing, and overhead together. The low case models about 6.5 enrollment equivalents and lighter help; the base case uses 8.5; the high case assumes roughly 11 enrollment equivalents and materially more payroll. The tuition assumptions stay within a broad planning band around the 2025 national family child care price evidence reported by Child Care Aware of America, but they are not a substitute for local competitor and subsidy-rate research.
Owner income scenarios
Low, base, and high cases show how enrollment, tuition, staffing, direct costs, and reserves change owner cash.
In-Home Daycare low, base, and high owner-income planning cases.
Scenario factor
Low CaseConservative
Base CasePlanning
High CaseStretch
Launch modelDemand and staffing posture
Slower fill; owner covers most care; limited paid relief.
Stable owner-operated home with part-time assistant coverage.
Near-capacity home with more paid assistant coverage and higher overhead.
Typical setupRevenue and capacity
$7,600 monthly revenue; about 6.5 enrollment equivalents; $1,100 blended tuition.
$10,350 monthly revenue; about 8.5 enrollment equivalents; $1,150 blended tuition.
$14,800 monthly revenue; about 11 enrollment equivalents; $1,275 blended tuition.
Cost driversMonthly cash assumptions
88% gross margin
$850 labor
$1,400 fixed overhead
$300 marketing + $150 debt
26% combined reserves
89% gross margin
$1,600 labor
$1,500 fixed overhead
$250 marketing + $200 debt
28% combined reserves
90% gross margin
$3,300 labor
$1,800 fixed overhead
$300 marketing + $250 debt
32% combined reserves
Owner income rangeAfter modeled tax and reinvestment reserves
$35,412
$48,918
$62,592
Best fitHow to use the case
Stress-test a slower opening, vacancy, or smaller licensed home.
Use for an established owner-operated home with steady enrollment and part-time help.
Test near-capacity operation only where licensing, age mix, staffing, and local tuition support it.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six detailed income drivers for an in-home daycare?
The six drivers below expand the same levers summarized above. Capacity and paid enrollment set the revenue ceiling; tuition and staffing shape contribution; direct costs, home overhead, and cash policy determine what is safe to distribute.
1. Enrollment and licensed capacity
Fill usable slots, not theoretical slots
The strongest owner-income lever is the number of permitted slots that are occupied and billable. The base uses 8.5 full-time-equivalent children and the high case about 11. Age mix, resident children, space, safety rules, and assistant requirements can lower usable capacity. California’s family child care capacity definitions show how higher caps depend on program type and specified criteria.
One extra full-time child at $1,150 monthly tuition adds $13,800 of annual tuition. At an 89% gross margin, that is about $12,282 of gross profit before added staffing, overhead, or reserves. If the child triggers materially more assistant coverage, the distribution gain shrinks.
Track enrollment in slot-days
Count paid slot-days by age group, not just children on the roster. Part-time schedules matter only when unused days can be resold.
Licensed capacity by age
Paid FTE enrollment
Vacant slot-days
Waitlist by age group
Marketing cost per filled slot
2. Tuition and age mix
Price the slot that is hardest to replace
The base uses $1,150 per enrolled child per month, with low and high cases near $1,100 and $1,275. These are planning inputs, not national tariffs. Child Care Aware of America’s 2025 family child care price tables show annual prices for infants and four-year-olds ranging roughly from $10,572 to $14,045 across its weighting methods.
A $50 monthly increase across 8.5 full-time-equivalent enrollments adds about $425 a month, or $5,100 a year, before direct costs and reserves. At the base margin and reserve assumptions, that can add about $3,270 of annual owner cash if enrollment holds.
Track realized tuition, not the rate sheet
Discounts, sibling pricing, part-time schedules, subsidies, and uncollected balances can pull realized revenue below the posted rate.
Realized tuition per FTE child
Discounts versus posted tuition
Price increase and retention
Age mix
Revenue per licensed slot
3. Staffing and owner coverage
Add paid coverage only when it unlocks revenue or reduces risk
The base carries $1,600 of monthly paid labor and the high case $3,300. May 2025 BLS data show a $16.82 median hourly wage for childcare workers. At that wage, 20 hours a week is roughly $1,458 a month before employer taxes, workers’ compensation, paid leave, or benefits, so the base represents part-time relief rather than a full-time owner replacement.
If another block of coverage costs $1,600 monthly, the business needs about $1,800 of additional monthly revenue at an 89% gross margin just to cover it before reserves. Staffing growth should therefore unlock a specific enrollment or capacity gain.
Track paid hours per enrolled child
Separate owner hours from employee hours so unpaid opening, closing, cleaning, shopping, and administration do not masquerade as labor efficiency.
Labor dollars per revenue dollar
Assistant hours per FTE child
Owner care and admin hours
Substitute coverage
Revenue unlocked by added staffing
4. Direct costs and CACFP reimbursement
Protect gross profit without underfunding care
The model uses an 88% to 90% gross margin after food, learning supplies, payment processing, and other non-labor direct costs. At the 89% base, direct costs are about $1,139 on $10,350 of monthly revenue. Compare that assumption with actual groceries, curriculum purchases, consumables, and merchant fees.
CACFP can offset eligible meal expense. The 2025-26 federal day-care-home rates total about $2.81 per child-day for a Tier II breakfast, lunch, and snack and $5.88 for Tier I in the contiguous states. At 8.5 children and 20 service days, that is roughly $478 to $1,000 before eligibility and attendance differences; the base uses $575.
Track food cost net of reimbursement
Record food cost, eligible reimbursement, and non-food supplies separately so the economics remain visible.
Food cost per child-day
CACFP revenue per eligible child-day
Supplies per enrolled child
Merchant fees
Gross margin before payroll
5. Home overhead and compliance
Separate household cost from business cash burn
The base budgets $1,500 a month for the business share of occupancy, incremental utilities, liability insurance, licensing and training, software, cleaning, repairs, and administration. Include the cash burden caused by the daycare; do not automatically treat the family’s entire housing cost as business overhead.
Tax deductions are separate from cash cost. IRS Publication 587 describes special business-use-of-home rules for daycare providers, including regular nonexclusive use in qualifying cases. A deduction may reduce taxable income, but it does not erase the utility bill, repair, or insurance premium.
Track a monthly home-business cost schedule
Review fixed costs quarterly and reserve for safety upgrades and wear instead of waiting for the invoice.
Incremental utilities and cleaning
Insurance and licensing
Training and checks
Repair and equipment reserve
Software and administration
6. Collections, debt service, and reserve policy
Pay the owner from cleared cash, not paper profit
The base subtracts $200 of monthly debt service, then reserves 20% of positive pre-reserve cash for taxes and 8% for reinvestment. With $5,661.50 of monthly cash profit before reserves, the model holds $1,585 and leaves $4,076.50 for the owner. Those percentages are planning choices, not tax rates.
Collection timing matters too. Losing one $1,150 tuition slot for a month removes more than five times the base debt payment. Clear advance-payment terms, consistent collections, and a waitlist reduce that pressure. Debt-free operators can set debt service to zero, but should retain enough cash for equipment, compliance, and substitute coverage.
Use a distribution gate every month
Before an extra draw, check the next 30 to 90 days of known obligations and confirmed enrollment.
Receivables and overdue days
Next month’s enrollment
Debt service coverage
Tax reserve balance
Repair reserve
Cash after planned owner pay
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.