How Should an Owner Estimate Income from a Juice Bar?
A U.S. owner-operated juice bar can realistically produce about $73,000 a year of owner income in a stabilized base case built on roughly $744,000 of annual sales, or $62,000 per month. The model assumes a counter-service juice and smoothie shop averaging about $11.50 per ticket, 180 daily transactions, a 64% gross margin after direct product costs, and an owner who covers general management. The modeled $72,912 remains after a 20% tax reserve and 10% reinvestment reserve; it is not guaranteed salary or GAAP net income. Personal tax results, major equipment replacements, and an added hired manager are excluded.
Owner income$73KNet margin10%Revenue for target pay$742KBusiness difficultyModerate
What can a juice bar owner realistically make after expenses?
The planning range runs from $0 in the downside case to about $161,000 a year in the high case, with the base at $72,912 after modeled reserves. It is wider than broad restaurant profit statistics because owner-manager compensation stays in the residual owner-income pool. For context, the National Restaurant Association reported 2024 median pre-tax income of 4.0% of sales and 65% prime cost for limited-service respondents; a juice bar is adjacent to, not identical with, that segment. See the National Restaurant Association operating-cost summary.
Revenue is customer spending; gross profit is revenue after direct product costs; operating profit is what remains after payroll and overhead. EBITDA excludes interest, taxes, depreciation, and amortization. Owner salary compensates labor, while distributions return residual cash to ownership. The calculator combines owner labor and ownership return into one owner-income pool, then subtracts modeled tax and reinvestment reserves; actual tax treatment may split that pool differently.
Owner income calculator
Adjust monthly sales, margins, staffing, overhead, financing, and reserves to estimate owner take-home and the sales level needed for target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Transactions and ticket
180/day × $11.50
The base sales engine is about 180 daily tickets at an $11.50 planning average. Small changes compound over every open day.
2
Gross margin
64% base
Produce yield, recipe portions, packaging, card fees, and waste decide how much of each sales dollar survives before payroll.
3
Labor scheduling
$18.5K/mo
Base employee payroll is about 30% of sales before owner pay. Overstaffed slow hours can erase the owner-income pool quickly.
4
Occupancy and overhead
$8.5K/mo
Rent, utilities, insurance, cleaning, software, permits, and repairs create a fixed floor that must be covered every month.
5
Owner-manager role
$65.3K benchmark
A hired manager can turn an owner-operated return into a much smaller passive distribution unless sales rise enough to fund the role.
6
Debt and reserves
$2K + 30%
Base debt service is $2,000 monthly, then 30% of positive profit is held for tax and reinvestment before owner cash is shown.
Want to test the assumptions in a full juice bar forecast?
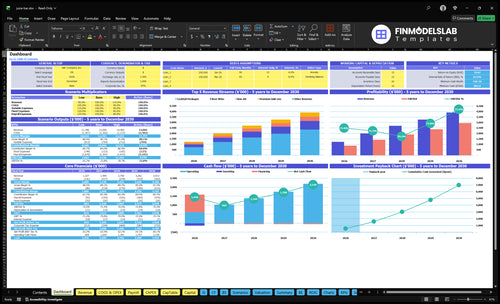
The Juice Bar Financial Model Template in Excel includes a dashboard, revenue inputs, payroll, operating costs, scenarios, and cash-flow views. The preview is useful for pressure-testing the same variables that determine owner income here: customer volume, average ticket, ingredient cost, staffing, fixed overhead, financing, and cash reserves.
How much revenue does a juice bar need to pay the owner?
In the base case, the shop needs about $48,438 of monthly revenue to cover operating costs before owner pay and reserves, because $31,000 of monthly labor, overhead, marketing, and debt service divided by a 64% gross margin equals roughly that break-even level. To support the modeled $6,000 monthly owner target after a combined 30% tax and reinvestment reserve, the calculator raises the requirement to $61,830 per month, or $741,960 a year. This is why revenue alone can be misleading: a juice bar can look busy and still leave little distributable cash if direct costs or payroll drift upward.
The 64% base gross margin is a planning assumption built from an adjacent limited-service benchmark. In the National Restaurant Association's 2025 operations data, food and non-alcohol beverage cost was a median 32.4% of 2024 sales for limited-service respondents. A juice bar still needs room for cups, lids, straws, card fees, and spoilage, so the model uses a slightly higher 36% direct-cost burden rather than simply copying the restaurant benchmark. See the limited-service food-cost data.
Base sales engine
Planning ticket: about $11.50
Transactions: about 180 per day
30-day sales math: about $62,100
Modeled monthly revenue: $62,000
What has to be paid first
Direct product and transaction costs
Employee payroll before owner pay
Rent, utilities, insurance, repairs, and admin
Marketing and debt service
Can a juice bar owner make more by working in the store?
Yes, but much of that extra cash is compensation for the owner's labor, not passive investment return. The base case assumes the owner handles general-manager duties, which is why the $18,500 monthly labor line covers employees but not a separate manager. The U.S. Bureau of Labor Statistics reported a $65,310 median annual wage for food service managers in May 2024. If the shop instead hired a manager at roughly that wage, before payroll burden, base monthly profit before reserves would fall from $8,680 to about $3,238, and the modeled after-reserve owner pool would drop to roughly $27,000 a year. See BLS food service manager pay data.
For an S corporation, the IRS says shareholder-employees must receive reasonable compensation before non-wage distributions. The calculator shows economic owner cash after operating costs and planning reserves, not legal tax treatment; the salary-versus-distribution split depends on entity type and work performed. See the IRS reasonable-compensation guidance.
Owner-operated economics
Owner opens, closes, orders, schedules, and manages quality
Employee payroll stays near $18.5K in the base case
$72.9K owner income includes pay for management work
Key-person risk is higher
Manager-run economics
Add manager salary and payroll burden
Passive distributions fall unless sales rise
Management coverage improves owner flexibility
Compare returns after pricing owner labor fairly
Key Takeaways
The base case supports about $73K of annual owner income on $744K of sales after modeled tax and reinvestment reserves.
About $48.4K of monthly sales covers modeled operating costs, but about $61.8K is needed to support a $6K monthly owner target after reserves.
Owner labor is a major economic input: hiring a manager can reduce distributions by roughly the cost of that role unless volume or pricing rises.
Gross margin, labor scheduling, and fixed overhead matter more than headline revenue because they decide how much cash survives each ticket.
What margin makes juice bar owner take-home sustainable?
A base gross margin around 64% can support owner income if labor and overhead remain close to plan; a 61% margin with weak volume does not. The broad limited-service restaurant comparison is useful because the National Restaurant Association found median labor cost of 31.7% of 2024 sales, and profitable limited-service respondents were at 30.0%. The juice bar base uses employee payroll of $18,500, or about 29.8% of sales, because the owner covers management. That is a deliberate reclassification, not a claim that juice bars universally run below restaurant labor benchmarks. See the limited-service labor-cost analysis.
One gross-margin point is worth about $620 per month at $62,000 of sales. A move from 36% to 38% direct cost cuts gross profit by $1,240 monthly and the modeled after-reserve owner pool by roughly $868. Track recipe yield, spoilage, portions, packaging, and card fees weekly.
Margin guardrails
Low case gross margin: 61%
Base gross margin: 64%
High case gross margin: 67%
Every point at base sales equals about $620 monthly
Price versus cost
Raise price only when customer value still holds
Track recipe cost by item, not total produce spend
Separate waste from normal ingredient usage
Protect attachment sales such as boosts or snacks
How do seasonality, spoilage, rent, and debt change safe owner draws?
They can turn an accounting profit into a cash shortage. Occupancy costs were a median 5.2% of sales for limited-service restaurants in 2024, with a 6.0% median in urban locations and 3.2% in small communities or rural areas. The base model's $8,500 fixed-overhead line is broader than rent: it also carries utilities, insurance, software, cleaning, repairs, permits, and administration. A location that needs $6,000 of rent at only $50,000 of monthly sales starts with a 12% rent burden before utilities or maintenance. See the occupancy-cost benchmark.
Fresh-produce spoilage consumes cash before a sale happens. Retail juice bars selling only to consumers are generally exempt from federal Juice HACCP, while FDA guidance points retail producers to the Food Code and applicable state and local rules. Processing or distributing juice to other businesses changes the federal treatment. Review the FDA Juice HACCP retail guidance before changing channels.
Debt also sits ahead of distributions. SBA explains that most 7(a) term loans are repaid from business cash flow with monthly principal-and-interest payments; the base model therefore separates $2,000 monthly debt service from overhead instead of hiding financing inside rent or equipment expense. See the SBA 7(a) loan guidance. The safest draw policy is to reserve taxes, replacement equipment, and at least several weeks of operating cash before treating the residual as spendable personal income.
Cash pressure points
Produce purchased before the customer arrives
Spoilage and prep loss do not create revenue
Rent and insurance remain due in slow weeks
Debt service is cash out even when sales dip
Distribution discipline
Fund tax reserve before owner spending
Keep repair cash for juicers and refrigeration
Rebuild working capital after seasonal dips
Use draws as flexible, not fixed, cash outflows
What do low, base, and high juice bar income cases look like?
All three cases use the same calculator logic. The downside combines slower traffic, lower pricing power, more waste, and heavier labor intensity; the base is an owner-managed stable run rate; the high case adds labor, marketing, overhead, and debt service as sales grow. Limited-service menu prices were up 3.3% year over year in July 2026, according to the National Restaurant Association menu-price tracker, so forecasts should update both prices and input costs.
Owner income scenarios
Compare a weak-volume case, the owner-operated base case, and a stronger high-volume case with matching changes in costs and reserves.
Low, base, and high Juice Bar owner-income planning assumptions.
Scenario factor
Low CaseStress case
Base CasePlanning case
High CaseUpside case
Launch modelOperating posture
Slow traffic and weak contribution margin; owner works in the shop but draws no modeled cash.
Stabilized owner-managed store with daily traffic near plan and no separate general manager.
Stronger demand with more staff, more marketing, higher overhead, and additional financing capacity.
Typical setupRevenue and margin
$42,000 monthly revenue, 61% gross margin, and a $4,000 target owner pay.
$62,000 monthly revenue, 64% gross margin, and a $6,000 target owner pay.
$90,000 monthly revenue, 67% gross margin, and a $10,000 target owner pay.
Cost driversMonthly operating load
Labor: $15,500
Fixed overhead: $8,200
Marketing: $1,500
Debt: $2,000
Reserves: 25%
Labor: $18,500
Fixed overhead: $8,500
Marketing: $2,000
Debt: $2,000
Reserves: 30%
Labor: $25,000
Fixed overhead: $9,500
Marketing: $3,000
Debt: $2,500
Reserves: 34%
Owner income rangeAfter modeled tax and reinvestment reserves
$0
Annual owner income after modeled reserves.
$72,912
Annual owner income after modeled reserves.
$160,776
Annual owner income after modeled reserves.
Best fitHow to use the case
Stress-test a soft opening, weak site, seasonal slowdown, or margin slippage.
Plan a mature single store where the owner remains the working general manager.
Test a strong site with better ticket, traffic, and purchasing while adding the staff needed to serve volume.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Juice Bar Core Six Income Drivers
1. Transactions per day and average ticket
Build revenue from tickets, not hope
The base case uses about 180 transactions per day at an $11.50 planning ticket. That is roughly $2,070 per day and $62,100 in a 30-day month, rounded to the calculator's $62,000. The low case is closer to 130 daily tickets at about $10.75, while the high case is roughly 235 tickets at about $12.75. These are planning assumptions, not national juice-bar averages. The point is to make the sales engine auditable: traffic × ticket × open days must equal revenue.
A $0.75 improvement in average ticket at 180 transactions per day adds about $4,050 monthly revenue. At a 64% gross margin, that creates roughly $2,592 of additional monthly gross profit before any extra labor or marketing. Pricing is not free money, however. Limited-service menu prices were still rising in 2026, so compare menu increases with customer counts and product mix rather than assuming every price change sticks.
Track traffic by daypart
Separate morning, lunch, afternoon, and weekend tickets so one strong period does not hide weak hours.
Transactions per labor hour
Average ticket by channel
Add-on attachment rate
Repeat-customer share
Owner income rises fastest when ticket growth comes from mix and add-ons without requiring the same percentage increase in staffing.
2. Gross margin, recipe yield, and produce waste
Protect the cents that survive each sale
The model's 64% base gross margin means 36 cents of each sales dollar goes to produce, dairy or alternatives, supplements, other direct ingredients, packaging, payment fees, and waste. The National Restaurant Association reported 32.4% food and non-alcohol beverage cost for the median limited-service respondent in 2024; this article deliberately adds room for juice-bar packaging, card costs, and spoilage rather than treating 32.4% as a complete juice-bar COGS ratio.
At $62,000 monthly sales, every one-point gross-margin change is $620 before reserves. A two-point deterioration from 64% to 62% removes $1,240 of monthly profit before reserves and about $868 of modeled owner income after the base 30% reserve policy. Recipe cards should therefore specify usable yield, not just purchase weight.
Measure waste in dollars and ounces
Record trimming loss, over-portioning, spoilage, comps, and remake waste separately so purchasing inflation is not confused with execution problems.
Recipe cost by SKU
Usable yield by produce item
Waste percentage by week
Gross margin by menu category
If waste rises while sales stay flat, owner cash usually falls before the P&L makes the problem obvious.
3. Labor scheduling and service productivity
Schedule to tickets, not habit
Base employee payroll is $18,500 per month, about 29.8% of sales, before owner pay. The broad limited-service labor median was 31.7% of sales in 2024, while profitable limited-service respondents were at 30.0%. This model sits near that profitable benchmark only because the owner covers management. It is not evidence that every juice bar can operate with the same staffing ratio.
For wage context, the U.S. Bureau of Labor Statistics reported a $16.45 median hourly wage for food preparation workers in May 2024. See the BLS food preparation wage profile. A four-hour unnecessary shift at $16.45 costs about $66 before payroll taxes; repeated five days a week, that is more than $17,000 a year before employer burden.
Use sales per labor hour
Match prep and counter coverage to forecast demand, then review actual tickets by fifteen- or thirty-minute blocks where the POS permits.
Sales per labor hour
Labor percentage by week
Opening and closing labor minutes
Overtime and call-out coverage
A labor cut that slows the line and loses peak-hour orders can reduce owner income, so productivity matters more than simply minimizing headcount.
4. Occupancy and fixed overhead
Underwrite the lease against normal sales
The base fixed-overhead assumption is $8,500 monthly for rent, common-area or property charges, utilities, insurance, software, cleaning, routine repairs, permits, and administration. It excludes payroll, marketing, direct costs, debt, and reserves. National Restaurant Association data showed a 5.2% median occupancy ratio for limited-service restaurants in 2024, but location mattered: 6.0% in urban areas, 5.0% in suburban areas, and 3.2% in small communities or rural areas.
At $62,000 monthly revenue, a 5.2% occupancy benchmark is about $3,224. If actual rent-related occupancy is $5,000, the ratio becomes 8.1% before utilities and maintenance. That does not automatically make the site bad, but it means traffic or ticket must compensate for the higher fixed burden.
Track fixed cost per open day
Translate monthly overhead into daily dollars so managers understand what the store must earn before owner cash exists.
Occupancy as a percent of sales
Utilities per transaction
Repair cost by equipment family
Fixed overhead per open day
Never justify a lease with the high scenario alone. The base case should carry the site without depending on perfect weather, peak tourism, or constant promotions.
5. Owner-manager coverage versus hired management
Separate the job from the investment return
The owner-operated base case produces $72,912 of annual owner income after modeled reserves, but that number pays for two things at once: the owner's management labor and the return on capital at risk. BLS reported a $65,310 median food-service-manager wage in May 2024. Using that as an adjacent proxy shows why a shop can pay an active owner reasonably yet produce only a thin passive return.
If a hired manager adds about $5,443 per month before payroll burden, the base $8,680 monthly profit-before-reserves pool falls to about $3,238. After the model's 20% tax reserve and 10% reinvestment reserve, only about $2,266 per month remains, roughly $27,000 a year. The actual result could be lower once employer payroll costs and benefits are included.
Price the owner's time every quarter
Track hours spent scheduling, buying, hiring, training, quality control, cash management, and customer recovery. Then compare that workload with a market management wage.
Owner hours per week
Manager-equivalent wage
Profit after replacement labor
Distribution after owner salary
This prevents a profitable-looking store from being valued as a passive asset when the economics actually depend on unpaid owner management.
6. Debt service, reserves, and cash timing
Profit is not the same as safe cash
The base case has $8,680 of monthly profit before reserves. It then holds $1,736 for the modeled 20% tax reserve and $868 for the 10% reinvestment reserve, leaving $6,076 of monthly owner income. Those reserves are planning policies, not accounting expenses. They exist because refrigerators fail, juicers need service, produce must be bought before it is sold, and taxes arrive on a different timetable from daily card receipts.
Debt service is modeled separately at $2,000 a month. SBA notes that most 7(a) term loans require monthly principal-and-interest payments from business cash flow. If debt rises without higher operating profit, distributions fall dollar for dollar before reserve effects. A store that reports positive operating profit but distributes cash needed for equipment replacement can still create a liquidity problem.
Set a draw rule before a good month
Use a minimum operating-cash threshold and only distribute cash above it after tax, debt, supplier, payroll, and maintenance needs are funded.
Weeks of cash on hand
Debt-service coverage
Tax reserve balance
Equipment replacement reserve
The right owner draw is therefore a cash-flow decision, not simply the profit shown on the income statement.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Juice Bar Bundle
Choosing a selection results in a full page refresh.