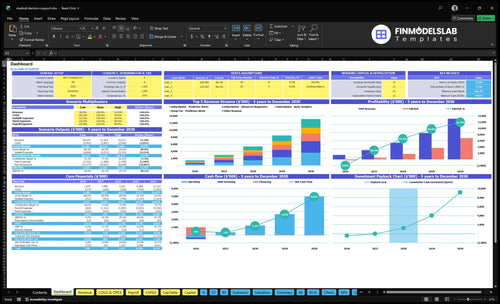
How Much Medical Decision Support Software Owners Make At $249M
Medical Decision Support Software Bundle
You’re estimating owner take-home, not a guaranteed software salary In this US provider-focused model, first-year revenue is $249M, gross margin is 88%, planned CEO pay is $180k, and extra distributions depend on payroll, compliance, sales cost, reserves, and reinvestment needs
Owner income$180kNet margin-21% to 52%Revenue for target pay$344kBusiness difficultyHard
Want the six owner-income drivers?
1
ACV
$324K
Higher contract value raises revenue per sale fast; even a small mix shift lifts owner income, but price cuts hit cash quickly.
2
Gross Margin
88%-92%
With margin in this range, each cost point saved drops straight to EBITDA, especially on cloud, integrations, and billing.
3
Renewals
High
Renewals protect recurring revenue and lower replacement selling, but adoption drops after launch can erode take-home fast.
4
Customer Count
60
More first-year customers spreads fixed overhead and sales cost, but weak pipeline volume shows up fast in cash burn.
5
Sales Efficiency
$2.5K-$2.1K
Lower CAC frees cash and shortens payback, but longer sales cycles can wipe out the gain before revenue lands.
6
Compliance Load
$336K
HIPAA, legal, and security staffing are hard to trim, so a $336K fixed base can delay payback if headcount outruns revenue.
Want to test your owner take-home?
Owner income calculator
Estimate owner take-home and target-pay gap from monthly revenue, gross margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only; it is not guaranteed salary, tax advice, or owner distribution advice.
Want to check owner income in the Medical Decision Support Software model?
Can a medical decision support software business scale profitably?
Medical Decision Support Software can scale profitably, but owner income can lag while provider sales cycles, clinical validation, integrations, and support absorb cash. Here’s the quick math: marketing rises from $150k to $800k, CAC falls from $2,500 to $2,100, and lead-to-paid conversion improves from 10% to 15%, while advanced diagnostics grows from 10% to 30% of the mix. Plan owner pay after delivery capacity.
Profit drivers
Raise marketing from $150k to $800k
Cut CAC from $2,500 to $2,100
Lift conversion from 10% to 15%
Shift mix to 30% advanced diagnostics
Scale pressure
Sales roles rise from 1 to 5 FTEs
Implementation roles rise from 1 to 4 FTEs
Engineering roles rise from 2 to 6 FTEs
Owner pay should wait for delivery capacity
What medical decision support software profit margin affects owner income?
Owner income in Medical Decision Support Software is driven by contribution margin (cash left after direct selling costs), not just top-line sales. Here’s the quick math: direct costs fall from 12% of revenue in year 1 to 8% in a mature year, so gross margin moves from 88% to 92%; year-1 sales commissions and payment processing take another 7%, so every point lost to hosting, integration, support, or billing hits owner pay fast. For the full margin map, see How Increase Medical Decision Support Software Profitability?
Margin drivers
12% direct costs in year 1.
8% direct costs in mature year.
Gross margin rises from 88% to 92%.
Lower direct cost lifts owner take-home.
Cash still leaves
7% sales commissions and payment processing.
Health Insurance Portability and Accountability Act (HIPAA) audits cost money.
Legal counsel and insurance cut distributable cash.
Engineering payroll and clinical staff still drain cash.
How much revenue does medical decision support software need to pay the owner?
Medical Decision Support Software needs about $1.65M in annual revenue to pay the owner $180k, using the first-year cost mix you gave. Here’s the quick math: 81% contribution margin after 12% cloud hosting and EHR integration plus 7% commissions and billing, so ($1.156M + $180k) / 0.81 ≈ $1.65M. If collections lag, churn rises, or compliance work grows, the break-even revenue moves higher.
Revenue math
81% contribution margin
12% cloud and EHR integration
7% commissions and billing
$1.156M fixed cost base
What lifts the target
$180k planned owner salary
$1.65M revenue target
Delayed collections raise cash needs
Compliance work can add cost
Key Takeaways
Higher annual contract value grows ARR faster than volume.
Customer wins help only after contracts close and onboard.
Retention protects ARR before fixed costs can flex.
Margin gains free more cash for payroll and growth.
Compare lean, base, and growth owner-income scenarios
Owner income scenarios
Owner pay changes fast here because revenue grows from $1.439M in Year 1 to $13.122M in Year 5 while margin improves and payroll scales hard. These cases show pre-tax pay capacity, not guaranteed distributions.
Low, base, and high cases help set owner pay without treating cash flow as a promise.
Scenario
Low CaseConservative
Base CaseBalanced
High CaseUpside
Launch model
The low case keeps owner pay near the planned $180k salary because Year 1 EBITDA is negative.
The base case adds some owner draw as Year 3 EBITDA turns strongly positive.
The high case supports a larger owner draw once Year 5 scale and margin mature.
Typical setup
Year 1 runs at $1.439M revenue, 88% gross margin, $150k marketing, $850k payroll, and $336k fixed overhead, so cash is tight.
Year 3 reaches $5.361M revenue, 90% gross margin, $400k marketing, and $1.63M payroll, which supports salary plus a modest draw if collections hold.
Year 5 reaches $13.122M revenue, 92% gross margin, $800k marketing, and $2.505M payroll, so owner pay can rise if support and renewals stay efficient.
Cost drivers
88% gross margin
$150k marketing
$850k payroll
$336k fixed overhead
10.0% lead-to-paid conversion
90% gross margin
$400k marketing
$1.63M payroll
3.0% visitor-to-lead conversion
12.0% lead-to-paid conversion
92% gross margin
$800k marketing
$2.505M payroll
3.5% visitor-to-lead conversion
15.0% lead-to-paid conversion
Owner income rangeBefore owner reserves
$180k salary onlySalary only
$180k plus modest drawModest draw
$180k plus large drawLarge draw
Best fit
Use this if Year 1 cash stays tight or collections lag.
Use this for a steady case with some owner draw room after Year 3.
Use this to test upside if renewal, timing, and support stay strong.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Medical Decision Support Software Core Six Income Drivers
Annual Contract Value And Pricing Model
Annual Contract Value
Higher annual contract value means each close adds more ARR, so owner income can grow faster without chasing lots of small accounts. Here, first-year weighted subscription ACV is $324k, and mature-year weighted subscription ACV reaches $5,868k, with implementation fees rising from $91k to $177k.
That pricing only holds if the software proves clinical value, fits daily workflow, and meets compliance and support needs. Big tiers can lift profit, but they can also add heavier validation, integration, and customer success work, which can eat into cash and delay owner pay if staffing does not scale with revenue. One strong deal can beat many weak ones.
Price to Scope, Not Just Seats
Measure providers, tier mix, implementation fee, and support hours for each account. The pricing model should reflect clinical scope, organization size, and the amount of workflow change the customer expects. If a deal needs more validation or integration, price that work in up front instead of funding it from subscription margin.
Track these inputs in the forecast: subscription ACV, setup fees, renewal risk, and post-sale labor. If higher-tier accounts take more clinical review or customer success time, gross margin can fall even when revenue rises. The goal is simple: raise contract value faster than delivery cost so more of each dollar turns into cash for payroll and owner draw.
Track ACV by tier.
Price implementation by scope.
Log support hours per account.
Watch margin by customer size.
Retention, Renewals, And Churn
Retention, Renewals, And Churn
Renewals are the cleanest way to make owner pay predictable. This software lives or dies on renewal rate and churn because subscription ARR is recurring, but only if hospitals and clinics keep using it after the first contract term.
No renewal-rate value is supplied, so keep it editable in the model. A lower renewal rate cuts subscription revenue before it cuts fixed payroll or compliance cost, so churn can squeeze profit and cash flow fast even when new sales still look healthy.
Track Renewal Risk Before It Hits ARR
Measure renewed ARR ÷ ARR up for renewal. Also track churned ARR, support tickets, uptime, and EHR integration failures. Retention here depends on clinical workflow fit, measurable value, support quality, uptime, and integration reliability, so those are the real levers behind owner income.
Churn is expensive because replacement sales cost more. If renewals weaken, marketing and sales spend rises just to refill lost ARR, and that delays owner draws. Build a renewal forecast by contract month, flag accounts with poor adoption, and fix issues before the next renewal window.
Customer Count And Market Penetration
Active Provider Customers
Customer count drives recurring revenue only after a provider contract closes and onboarding starts. The source math shows $150k in marketing at $2,500 CAC can produce about 60 first-year customers, while $800k at $2,100 CAC can reach about 381 mature-year customers. More live accounts mean more subscription cash for payroll, compliance, and owner pay.
Leads are not revenue. A 10% to 15% conversion lift helps, but provider procurement and implementation timing can push cash later than the sales forecast. So the real income driver is not pipeline size alone; it’s how fast signed deals become active, billing customers.
Track Signed, Live, and Paying
Measure leads, closes, onboarded customers, CAC, and days to go-live. That shows where revenue is stuck. If close rates rise but onboarding drags, cash still lags and owner draw gets tighter.
Separate signed from live accounts.
Track lead-to-paid conversion monthly.
Forecast cash by go-live date.
Watch CAC against payback time.
One clean test: compare booked deals to active customers every month, not just the sales pipeline.
Sales, Implementation, And Onboarding Efficiency
Sales Efficiency
CAC is the cost to win a paying customer. Here, it improves from $2,500 to $2,100, and lead-to-paid conversion rises from 10% to 15%. That means the same sales budget buys more ARR, so more of each new dollar can reach owner pay instead of getting spent on selling.
Sales commissions stay at 5% of revenue, so the margin gain comes mostly from better close rates and lower acquisition cost. The catch: implementation fees are separate from subscription ARR, and weighted fees rise from $91k to $177k, so onboarding work has to stay fast or cash comes in late.
Track the full handoff
Measure marketing spend, CAC, close rate, commission dollars, and days to go-live on each deal. Lead-to-paid conversion is just the share of leads that become paying customers, and it only helps owner income if implementation can keep up.
Watch CAC by segment
Track lead-to-paid weekly
Separate setup cash from ARR
Cap custom onboarding scope
Here’s the quick math: a lower CAC plus a 15% close rate means more revenue per sales dollar, but only if delivery can absorb the work. Custom onboarding can eat clinical implementation capacity, which can delay renewals or cash collection and squeeze owner draw.
Compliance, Clinical Validation, And Product Staffing
Compliance And Product Staffing Load
For a clinical decision support product, compliance and validation are part of the cost of selling, not optional spend. The disclosed fixed load is $45k/month for HIPAA compliance and security audits, $6k/month for legal and regulatory counsel, $3k/month for professional liability insurance, and $25k/month for software tools: $79k/month total, or $948k/year before product payroll.
Product payroll adds more pressure. It starts at $465k in year 1 and scales to the provided mature-year figure of $1395M. So owner take-home only rises after clinical review, security controls, regulatory work, and product updates are funded. If audit scope expands or releases slow down, cash goes to reinvestment first and profit to the owner later.
Track compliance burn tightly
Measure this as a monthly reinvestment rate, not just overhead. Here’s the quick math: track audit spend, legal hours, insurance, tools, and product FTEs separately, then tie each cost to live customers, active providers, and release cycles. That shows whether compliance is scaling with revenue or just shrinking the owner draw.
Tag required work by category.
Forecast payroll by release.
Review audit cost monthly.
Separate client work from core product work.
If onboarding takes longer or validation needs more review, staff and cash needs rise before revenue catches up. Keep those costs in the model as required reinvestment so you can see the real margin left for debt service, growth spend, and owner pay.
Gross Margin After Delivery Costs
Gross Margin After Delivery Costs
Gross margin is the cash left after direct delivery costs, and here that means cloud infrastructure, HIPAA hosting, and EHR API and integration maintenance. In this model, those costs fall from 12% to 8% of revenue, so gross margin rises from 88% to 92%. That extra 4 points is the pool that pays payroll, compliance, sales, and the owner.
Here’s the quick math: every 1 margin point on $249M of revenue is about $249k of annual cash. The catch is support burden and clinical content maintenance can still दब the margin even when hosting looks better, so the owner’s take-home depends on keeping direct service work from creeping above plan.
Track Direct Cost Run Rate
Measure gross margin monthly as revenue minus direct delivery costs, then split those costs into hosting, API maintenance, support, and clinical content upkeep. That tells you whether margin is improving because the product is efficient, or just because one cost bucket slipped. If support tickets rise, margin can fall fast even with stable cloud spend.
Use a simple target: hold direct costs near 8% of revenue, and flag any drift above that before it hits payroll or owner draw. If onboarding or integration work starts to consume more hours, treat it as a margin issue, not just an ops issue, because it cuts the cash available for compliance, sales, and profit.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.