How Much Mobile EV Charging Owners Can Make: $054M Year 1 EBITDA
Mobile EV Charging Bundle
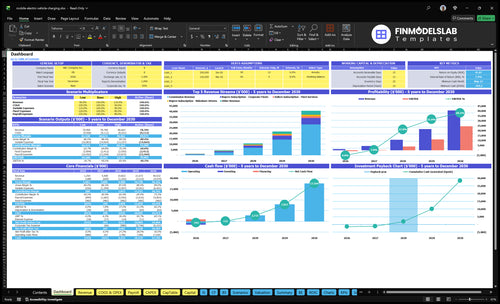
A mobile EV charging business owner can make strong money only if paid sessions, recurring accounts, and route density cover fixed costs fast In the supplied first-year assumptions, 4,444 buyers generate about 20,667 annual orders, about $181M in modeled revenue, and about $054M in EBITDA before taxes, debt, reserves, and owner pay Gross margin after payment processing and cloud costs is 85%, but contribution after support and insurance drops to 685% Treat these as researched planning assumptions, not guaranteed owner income
Owner income($875k)Net margin85%Revenue for target pay≈$1.6MBusiness difficultyHard
Want the six drivers behind mobile EV charging profit?
1
Utilization
20.7K
With 20.7K Year 1 orders and $350K in marketing, utilization has to stay high to make the spend pay back.
2
Avg Revenue
$8.75K
A higher charge per job pushes more cash through each stop, so take-home rises without more trips.
3
Route Efficiency
85%
Cleaner routing protects the 85% gross margin, because less dead time means more paid work per mile.
4
Equipment Uptime
685%
The model's 685% contribution margin figure makes uptime and capacity a huge swing on paper.
5
Labor Model
$29K/mo
The monthly overhead floor is about $29K, so labor has to stay lean or margin gets swallowed.
6
Cash Buffer
-$764K
Minimum cash lands at -$764K in Month 17, so funding terms and reserves decide if growth survives.
Want to test your mobile EV charging income?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, gross margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
How do you check owner income in the Mobile EV Charging model?
How many mobile EV charging jobs per day to pay the owner?
For Mobile EV Charging, owner pay depends on utilization, not a fixed job count: at the stated $5,994 contribution/order, $582k/month overhead needs about 97 jobs/month, or 3.2 jobs/day, before debt, taxes, reserves, vehicle costs, and owner draw; the deeper operating question is What Is The Most Critical Metric For Mobile EV Charging's Success?. Each added $10k/month owner draw needs about 1.7 more jobs/month at that same contribution rate.
Quick math
20,667/year equals 56.6/day
$8,750 modeled revenue/order
$5,994 contribution after variable costs
$582k ÷ $5,994 = 97 orders/month
Owner-pay trigger
Pay owner after fixed burn clears
Add reserves before taking draws
$10k draw adds 1.7 orders/month
566/day would imply 206,590/year
Most profitable mobile EV charging revenue streams
For Mobile EV Charging, corporate fleets are the strongest first-year revenue stream: $85 AOV times 85 repeat orders equals about $7,225 per buyer, versus $875 for personal EV owners and $540 for rideshare drivers. Subscriptions add steady cash too, with first-year monthly fees of $999, $7,999, and $1,999 by segment. Roadside charging can bring urgent demand, but it can also burn travel time, so route density matters more than raw call volume.
Can an owner-operator mobile EV charging business make more?
Mobile EV Charging can pay the owner more early if they run the routes themselves, because you avoid hired driver cost. But that savings is not the same as durable owner pay; once you add drivers, you also add payroll, training, scheduling, insurance exposure, and more management work. The supplied model does not include driver wages or vehicle counts, so you can’t calculate revenue per van yet, and scaling should be judged on contribution per paid session, route density, uptime, and reserve needs.
Owner-run routes
Higher early take-home from no driver wages
Lower cash burn before scaling
More control over route timing
Direct service quality on each stop
Scaling reality
Driver payroll cuts margin fast
Training and scheduling add overhead
Insurance and downtime can hit cash flow
Cash must survive labor, financing, and repairs
Key Takeaways
More paid sessions spread fixed costs and raise take-home.
Revenue per job is editable, not fixed.
Dense routes cut travel waste and improve cash flow.
Compare lean, base, and high mobile EV charging income cases
Owner income scenarios
Owner income here swings with buyer count, seller mix, repeat orders, and variable costs. These cases show the spread from lean launch to scale before taxes, debt, reserves, and owner pay.
Lean, base, and high cases for owner income planning.
Scenario
Low CaseLow case
Base CaseBase case
High CaseHigh case
Launch model
This is the lean case for a slower launch and thinner owner take-home.
This is the modeled middle path with steadier volume and stronger owner earnings.
This is the stronger earnings path if volume and mix scale faster than expected.
Typical setup
Year 1 uses 4,444 buyers, 176 sellers, 20,667 orders, about $181M revenue, 85% gross margin, and about $540k EBITDA before taxes, debt, reserves, and owner pay.
Year 3 uses 18,125 buyers, 646 sellers, 142,281 orders, about $12.24M revenue, 254% total variable cost load, and about $7.78M EBITDA proxy.
Year 5 uses 44,000 buyers, 1,442 sellers, 514,800 orders, about $45.14M revenue, 222% total variable cost load, and about $32.92M EBITDA proxy.
Cost drivers
Buyer CAC
seller CAC
repeat orders
marketing spend
fixed overhead
Buyer CAC
seller CAC
repeat orders
variable cost load
staff buildout
Buyer CAC
seller CAC
repeat orders
fleet mix
operating scale
Owner income rangeBefore owner reserves
$540kLean earnings case
$7.78MBase earnings case
$32.92MUpside earnings case
Best fit
Use this to stress-test a slow launch, thin repeat use, and higher acquisition costs.
Use this as the main planning case for a scaled but still cost-heavy operating path.
Use this to test upside if fleet mix, repeat orders, and volume scale faster than costs.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Mobile EV Charging Core Six Income Drivers
Paid utilization
Paid utilization
Paid sessions per day is the biggest swing factor for owner income here. The model shows 20,667 orders in Year 1, or about 566 per day, so every missed session leaves fixed costs like $29k/month overhead and $350k/year marketing spread over fewer jobs.
Idle time, weak demand density, long travel gaps, and poor dispatch scheduling all cut take-home pay. Track completed paid calls, canceled calls, wait time, miles per job, and jobs per service vehicle; those inputs show whether the business can support owner draw.
Raise paid sessions
Measure paid utilization as completed paid sessions ÷ available service slots. If paid sessions slip, test demand density by area and hour, then tighten dispatch so vehicles spend less time waiting or driving empty. One more completed session matters when overhead is already locked in.
Track completed paid calls daily.
Log cancellations and no-shows.
Watch wait time by zip code.
Measure miles per job.
Count jobs per service vehicle.
The goal is simple: lift completed sessions without adding idle miles, so more revenue turns into cash that can reach the owner.
Labor model
Labor Model
Labor is a take-home lever because it controls how many paid sessions one person can cover and how much margin gets left after payroll. The model does not supply wages, so you cannot judge owner income from revenue alone. An owner-operated setup can improve early cash flow by replacing paid driver labor, but it also caps growth at the owner’s available hours.
Hired technicians can lift capacity and coverage, but they add payroll, training, scheduling, and insurance costs. At the modeled scale of 20,667 orders in Year 1 or about 566 per day, labor efficiency matters fast: more sessions per shift lowers labor cost per job, while overtime, idle dispatch time, and weak coverage cut the owner’s draw.
Track Labor per Session
Measure labor as cost per session, not just payroll. Track sessions per shift, overtime hours, dispatch workload, and unpaid owner hours so you can separate true profit from the owner’s own labor. If owner time is doing the work, cash flow may look better than it really is.
Count completed paid calls.
Log canceled calls and wait time.
Track jobs per service vehicle.
Watch miles per job.
Compare hired labor to owner labor.
One clean rule: if labor hours rise faster than completed sessions, owner income falls. Keep the schedule tight, keep routes dense, and add staff only when extra sessions cover payroll after dispatch and insurance are included.
Financing and fixed-cost reserves
Fixed overhead and reserve load
Fixed costs hit owner pay before cash gets to the owner. The model shows $29k/month of known overhead, while the disclosed line items also name $12k rent, $85k software, $5k legal, and $35k accounting, so the cost map needs reconciliation before anyone uses EBITDA (earnings before interest, taxes, depreciation, and amortization) as distributable income.
Marketing adds $350k in Year 1 and rises to $185M by Year 5 in the model, so cash planning has to follow the spend curve. If reserve logic is missing, the owner can look profitable on paper and still have no safe draw. EBITDA is not spendable cash.
Reserve before you draw
Build the cash plan around the not-yet-sized items: equipment financing, insurance deductibles, maintenance, battery replacement, permits, and reserves. Each one lowers what can be paid out to the owner, even when revenue is up. Reserve first, draw second.
Track fixed overhead monthly.
Separate EBITDA from cash.
Model marketing by year.
Stress test debt service.
Set reserve targets by vehicle.
Use the reserve account before distributions, not after. That keeps owner pay tied to real cash, not accounting profit.
Equipment capacity and uptime
Battery capacity and uptime
This driver sets the ceiling on sessions each service vehicle can sell. It includes battery capacity, charger output, recharge lag, and downtime. If a truck can finish fewer charges before it must recharge, each lost hour cuts revenue and leaves fixed costs in place. The supplied data does not give kWh delivered, charger speed, vehicle count, equipment cost, or maintenance hours, so this must be modeled, not assumed.
The income hit shows up in gross margin and cash flow. More usable fleet hours spread $29k/month of fixed overhead across more orders, but downtime hurts twice because revenue stops and the cost base stays. The key question is how many paid charges one vehicle can complete before it goes offline, because that number sets owner take-home.
Track usable fleet hours
Measure the vehicle, not just the platform. Log kWh delivered per route, completed charges before recharge, and failed sessions so you can see whether the ceiling is battery size, charger speed, or dispatch gaps.
kWh delivered per route
completed charges before recharge
failed sessions
maintenance days
usable fleet hours
If uptime slips, owner pay slips too. A truck down for recharge or maintenance can't earn, and the same overhead gets spread across fewer jobs. Use the log to set a daily uptime target and cut turnaround time between jobs.
Average revenue per job
Average Revenue per Job
Average revenue per job is the fastest way pricing changes owner income. The mix of service fees, per-kWh charges, emergency premiums, contracts, and subscriptions sets cash per stop, so the same job volume can produce very different take-home. In Year 1, the supplied AOVs are $35 for personal EV owners, $85 for corporate fleets, and $45 for rideshare drivers.
Repeat orders matter too: 25, 85, and 120 respectively. The model also shows commission revenue averaging about $998 per order in Year 1, but pricing is market and regulatory dependent, so treat it as editable. Higher revenue per job helps cover fixed costs faster and leaves more cash for owner pay.
Keep Pricing Editable
Track revenue by segment, not just total sales. Here’s the quick math: the same dispatch can be a $35 personal charge, an $85 fleet job, or a $45 rideshare call, plus add-on fees. If your average slips, you need more jobs just to fund the same payroll, software, and marketing.
Use a pricing file with editable fields for service fee, per-kWh charge, emergency premium, contract rate, and subscription. Review it monthly against win rate, repeat orders, and refunds. If regulatory limits tighten or emergency demand rises, adjust fast; don’t lock the price and let margin leak.
Track AOV by customer type.
Test fees and premiums monthly.
Watch repeat orders and refunds.
Route efficiency
Route Efficiency
When routes are dense, more technician hours turn into billable charging time instead of windshield time. That matters here because the model’s first-year break-even math depends on about $5,994 contribution per modeled order, so every extra mile or deadhead stop slows owner pay and stretches the path to cash taken home.
Weak geography raises labor cost, vehicle wear, wait times, and missed bookings. Tight response areas do the opposite: they cut travel minutes, improve arrival speed, and let each service vehicle complete more sessions per shift. One bad route can drag down an otherwise strong day.
Track Route Waste Fast
Measure response radius, travel minutes, jobs per route, and completed sessions per shift. If travel time keeps rising while sessions stay flat, the shift is leaking margin even when gross revenue looks fine.
Use routing rules to cluster jobs by zone, time window, and vehicle type. The goal is simple: fewer empty miles, more billable stops, and less labor spent on unproductive driving. That is what turns service volume into owner profit.
Cap service zones by dispatch time.
Group nearby jobs first.
Reject low-density routes early.
Review canceled calls by area.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.