What Can an Owner Expect to Take Home from a Music School?
Music School Bundle
An owner-operated U.S. neighborhood music school can reasonably model about $92,820 a year in owner income in a stabilized base case, with a stressed low case of $7,824 and a strong-utilization high case of $187,536. The base model assumes $55,000 of monthly collected revenue, or $660,000 annually, from recurring private lessons, small-group instruction, workshops, and related tuition; a 95% pre-payroll gross margin; $28,000 monthly instructor and administrative payroll; $8,500 fixed overhead; $3,500 marketing; and $1,200 debt service. It then holds back 20% of positive pre-reserve profit for taxes and 10% for reinvestment. The resulting $92,820 is residual owner cash after those modeled reserves, not a guaranteed salary or distribution. It excludes any separate owner wage added on top, final personal tax reconciliation, investor distributions, and one-off capital shocks. The operating scope here is a non-degree community music school or lesson studio, not a conservatory, college, or solo home teacher.
How much can a music school owner make in the U.S.?
For this operating model, the realistic planning range is wide: roughly $8,000 to $188,000 of annual owner income across the three scenarios, with about $93,000 in the base case. The scope aligns with the U.S. Census classification for fine arts schools, where NAICS 611610 includes music instruction and music schools outside academic degree programs. That definition matters because a multi-instructor school has different economics from a self-employed teacher: the owner must fill rooms, coordinate instructors, collect recurring tuition, and carry lease and administrative costs even when enrollment softens.
The base case produces $52,250 of monthly gross profit before payroll. After $28,000 employee labor, $8,500 fixed overhead, $3,500 marketing, and $1,200 debt service, profit before reserves is $11,050. The modeled $2,210 tax reserve and $1,105 reinvestment reserve leave $7,735 monthly owner income, or $92,820 annualized. Because debt service is already a cash claim and reserves are management set-asides, this output is neither conventional EBITDA nor GAAP net income.
Keep the labels separate: revenue is sales collected; gross profit is revenue after direct non-labor costs; operating cash profit follows payroll, overhead, marketing, and debt; and safe distributable cash remains only after reserves and near-term obligations. Owner compensation may then be split between salary and distributions.
Owner income$93KNet margin14%Revenue for target pay$656KBusiness difficultyModerate
Owner income calculator
Adjust tuition revenue, staffing, overhead, reserves, and target pay to estimate owner cash.
i
Planning note: These are planning estimates. Owner income is residual cash after modeled reserves, not guaranteed salary, tax advice, or a promised distribution.
What revenue level supports a real owner draw?
The base model needs about $43,400 per month simply to cover its modeled operating cost structure at a 95% pre-payroll gross margin, before creating owner income or reserves. To support the $7,500 monthly target owner pay after the 20% tax and 10% reinvestment reserves, the fixed calculator formula raises required revenue to $54,647 per month, or $655,764 per year. That is why a $660,000 sales plan and a $90,000-plus owner-income plan are economically connected rather than separate goals.
Start with active students by lesson type, not a desired annual sales number.
Multiply by collected tuition after discounts, credits, scholarships, and missed billing.
Add group classes, camps, registration fees, and workshops only when staffing and room capacity can support them.
Stress-test a 10% enrollment miss: at the $55,000 base, that is $5,500 of monthly revenue at risk before cost reductions.
Protect the owner draw threshold
Base operating cash break-even is about $43,400 a month with the modeled cost structure.
The $7,500 target owner pay needs about $54,647 monthly sales after modeled reserves.
A lease or payroll plan that pushes break-even above ordinary enrollment capacity should be redesigned before expansion.
Do not treat prepaid tuition or a temporarily high bank balance as profit available for distribution.
Which six levers move music school owner income fastest?
The six biggest levers in this model are active student capacity, tuition and lesson mix, instructor payroll, retention and acquisition, room and overhead utilization, and debt plus cash reserves. Demand for arts participation is broad but does not guarantee demand for a particular school: the National Endowment for the Arts reported that 52% of U.S. adults did some form of art making in 2022, with musical instrument activity among categories showing growth versus 2017. A local owner still has to convert that interest into recurring enrollment at a price that supports teachers and rooms.
1
Active student capacity
250 students
The base case uses about 250 active student-month equivalents; schedule density determines whether rooms and instructors can support that count without waste.
2
Tuition and lesson mix
$220/mo
A $220 blended collected-revenue assumption per active student combines private lessons, groups, and other programs rather than treating one posted lesson rate as average tuition.
3
Instructor payroll
51% of sales
Base employee payroll is $28,000 on $55,000 revenue. Small schedule gaps or excessive paid admin time can consume owner cash quickly.
4
Retention and acquisition
$3.5K/mo
Base marketing spend is $3,500 monthly. Retaining ten students protects about $2,200 of monthly recurring revenue at the modeled $220 blend.
5
Room and overhead utilization
$8.5K/mo
Rent and recurring facility/admin overhead are modeled at $8,500 monthly, so weak prime-time room use raises the revenue each occupied room must carry.
6
Debt and cash reserves
$4.5K/mo
Base debt service plus modeled tax and reinvestment reserves consume $4,515 monthly before owner cash is considered safe to take.
Want to test the tuition, staffing, and owner-pay assumptions in a full forecast?
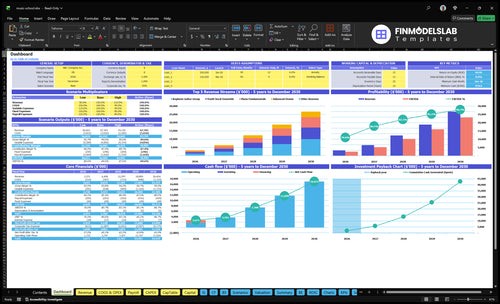
The Music School Financial Projections Template in Excel provides a business-specific model for changing enrollment, lesson rates, staffing, operating costs, debt, and scenarios together. The dashboard preview is useful for checking whether the owner-income story still holds when tuition mix, payroll, cash flow, and financing assumptions change at the same time.
Can pricing and instructor utilization support $90K+ owner income?
At 250 active student equivalents, every $10 change in blended collected monthly revenue changes sales by about $2,500 per month. Holding the base cost structure temporarily constant, the 95% pre-payroll gross margin means roughly $2,375 reaches gross profit before any extra staffing, marketing, or reserves. The danger is assuming all price increases flow through. If a higher price reduces re-enrollment, increases scholarships, or requires more experienced instructors, the real contribution can be much smaller.
Price the whole program
Track collected revenue per active student, not only the posted lesson rate.
Separate 30-, 45-, and 60-minute lessons because teacher capacity per room-hour differs.
Use group programs to lift revenue per room-hour when demand supports enough seats.
Measure discounts and make-up policies because they can weaken realized price without changing the price list.
Schedule for contribution
Fill peak after-school blocks before adding rooms or extending opening hours.
Compare revenue per paid instructor hour by teacher and program.
Avoid scattered schedules that create paid gaps, front-desk coverage, and room cost without tuition.
Add high-case labor as enrollment grows; the model increases payroll from $28,000 to $42,000 instead of pretending scale is free.
How should staffing, rent, and cash reserves be structured?
Staffing should flex with booked teaching hours, while rent and administration should be sized to ordinary enrollment rather than the high case. The best available national labor anchor is adjacent rather than music-specific: BLS May 2023 data for Other Schools and Instruction reported a $21.87 median and $25.15 mean hourly wage for self-enrichment teachers. BLS wage data excludes self-employed workers and covers a broader category than music instruction, so it should guide reasonableness, not dictate a teacher-pay rate in any one city.
Base instructor and administrative payroll is $28,000 a month, about 51% of sales, while fixed overhead is $8,500, about 15%. These are model outputs, not industry benchmarks. The implication is simple: do not sign a facility or permanent staffing plan that only works at high-case enrollment. The owner covers some administration in the base case, so the owner-income pool must compensate both labor and capital.
Tuition may be collected before lessons are delivered, but advance cash still carries future teaching obligations. That is why the model keeps tax and reinvestment reserves visible instead of treating a temporarily strong bank balance as an automatic draw.
Costs that should move with demand
Instructor hours and substitute coverage should follow booked lessons and group enrollment.
Marketing can rise during enrollment periods, but track cost per enrolled student rather than spend alone.
Consumable materials and card fees belong in direct cost, not again in fixed overhead.
High-case staffing must include added coordination and administration when complexity rises.
Costs that need protection
Rent, insurance, software, and basic administration continue during school breaks and soft months.
Debt service is a cash claim even when accounting profit looks healthy.
Tax reserves should not be used to fund routine payroll or distributions.
Reinvestment reserves protect instruments, rooms, technology, and working capital from becoming emergency owner contributions.
Key Takeaways
The base case produces $92,820 of annual owner income on $660,000 sales after modeled tax and reinvestment reserves.
About $43,400 of monthly revenue covers the base operating cash structure, but roughly $54,647 is needed for a $7,500 monthly owner-pay target after reserves.
Instructor payroll and prime-time room utilization are the biggest controllable cost-capacity pair; adding students without schedule density can create activity without owner cash.
Owner salary, distributions, taxes, debt service, and reinvestment are separate claims on cash and should never be blended into one “profit” number.
What do low, base, and high owner-income scenarios look like?
The low case shows how fast owner income can collapse when enrollment is soft but payroll and rent do not fall proportionally. The base case assumes a stabilized local school at $55,000 monthly revenue. The high case reaches $88,000 monthly revenue but also adds instructors, administration, overhead, marketing, debt service, and larger reserves. This follows the SBA break-even principle that revenue targets have to be reconciled with fixed and variable costs; upside is not modeled as extra sales on an unchanged cost base.
These are stress tests, not forecasts. Annual owner income is $7,824 in Low, $92,820 in Base, and $187,536 in High after each case's modeled tax and reinvestment reserves. Reserve rates rise with scale so the larger case retains more cash for tax, equipment, and working-capital exposure.
Owner income scenarios
Three reconciled cases show how enrollment, cost structure, reserves, and operating scale change owner cash.
Music School low, base, and high owner-income planning scenarios
Scenario
Low CaseStress test
Base CasePlanning case
High CaseStretch case
Launch modelDemand and scale posture
$32,000 monthly revenue
Slower enrollment and thin owner cushion
$55,000 monthly revenue
Recurring private and group tuition
$88,000 monthly revenue
More instructors and administration
Typical setupCore monthly inputs
94% pre-payroll gross margin
$18K labor and $7.8K overhead
95% pre-payroll gross margin
$28K labor and $8.5K overhead
96% pre-payroll gross margin
$42K labor and $11.5K overhead
Cost driversCash claims before owner pay
$29.2K operating costs
$228 modeled reserves
$41.2K operating costs
$3,315 modeled reserves
$60.8K operating costs
$8,052 modeled reserves
Owner income rangeAfter modeled tax and reinvestment reserves
$7,824
$92,820
$187,536
Best fitWhen to use the case
Weak-ramp downside test
Tests the fixed-cost floor
Normal planning case
Owner still active in operations
Strong utilization case
Costs rise with scale
i
Planning note: These are planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts. Actual owner cash depends on local pricing, wages, lease terms, taxes, working capital, refunds, and reinvestment.
How should owner salary and distributions be separated?
Do not add an owner salary on top of the $92,820 base owner-income figure. In this calculator, laborCost excludes owner pay by design, so $92,820 is the total modeled owner-income pool after operating costs and reserves. If the owner teaches or manages, part of that pool may represent compensation for services rather than passive return on capital.
The base bridge is $55,000 revenue, $52,250 gross profit, $41,200 operating costs, $11,050 before reserves, $3,315 held back, and $7,735 monthly owner income. Treat that residual as distributable only after payroll, taxes, future lesson obligations, debt, refunds, and required cash are covered.
Six detailed music school income drivers
The six drivers below use the same base case as the calculator. Each one connects an operational decision to owner cash, so the owner can see which metric deserves weekly attention and which apparent improvement is only cosmetic.
1. Active student capacity
Build the revenue ceiling from usable teaching capacity
A music school sells teacher time and room capacity. The Census definition of music schools within NAICS 611610 keeps this model focused on non-degree instruction. The base plan uses about 250 active student-month equivalents at $220 blended collected revenue, producing $55,000 monthly sales. A 10% enrollment miss removes about $5,500 a month before costs respond, so owner income can fall faster than enrollment.
Measure capacity in the hours families actually want. Dense after-school and Saturday schedules make the same rooms and teachers more productive than scattered appointments.
Track filled lesson slots, not room count
Review the capacity funnel every week so an expansion decision is tied to real demand.
Active paying student equivalents
Prime-time lesson-slot fill rate
Group seat fill by program
Trial-to-enrollment conversion
Waitlist by instrument and time block
2. Tuition and lesson mix
Raise collected revenue without pricing past retention
A $10 increase across 250 active students adds $2,500 monthly revenue and about $2,375 gross profit at a 95% pre-payroll margin before added costs. But losing 15 students would remove about $3,300 monthly revenue. Judge pricing by contribution after retention.
Track realized price by program
Posted tuition is less useful than what the school actually collects after credits and discounts.
Base payroll is $28,000 monthly, or 50.9% of $55,000 sales. A rise from 51% to 54% would consume about $19,800 annually before reserve effects. The high case raises payroll to $42,000 because growth needs paid teaching and coordination.
Measure output per paid hour
Schedule efficiency reveals payroll leakage earlier than a monthly income statement.
Revenue per paid instructor hour
Payroll as a percentage of sales
Paid gaps between lessons
Make-up and no-show hours
Administrative hours per 100 students
4. Retention and acquisition
Treat re-enrollment as recurring-revenue protection
Base marketing is $3,500 monthly. Losing ten students at the $220 modeled blend puts $2,200 monthly revenue at risk. Replacing ten at a separate $140 planning CAC adds $1,400 of acquisition cost. Retention therefore protects both tuition and marketing efficiency.
Watch the cohort before adding ad spend
Acquisition only creates owner value when new students stay long enough to recover their onboarding cost.
Term-to-term re-enrollment rate
30-, 60-, and 90-day retention
Cost per enrolled student
Referral share of new enrollment
Cancellation reasons by teacher and time slot
5. Room and overhead utilization
Make fixed overhead earn during peak hours
The SBA connects break-even to fixed costs and contribution margin. Here, $8,500 fixed overhead and the full base operating structure imply about $43,368 monthly operating cash break-even at a 95% pre-payroll gross margin, holding costs constant. With 250 active equivalents, that is roughly $173 of monthly revenue per student equivalent before owner income or reserves.
Time of day matters: empty prime-time rooms strand rent, front-desk coverage, and teacher availability. Expand only when peak slots are constrained or off-peak programs can contribute.
Track revenue density before expanding
A lease decision should be justified by contribution per usable room-hour, not by square footage alone.
Revenue per occupied room-hour
Prime-time room utilization
Fixed overhead as a percentage of sales
Monthly operating break-even revenue
Revenue added per incremental room
6. Debt and cash reserves
Separate accounting profit from cash safe to distribute
Base profit before reserves is $11,050 monthly. The model holds $2,210 for taxes and $1,105 for reinvestment, leaving $7,735 owner income; $1,200 debt service was already paid. Debt plus reserves therefore claim $4,515 a month before the residual is treated as safe take-home.
Approve distributions from forward cash, not yesterday's balance
Use a rolling cash view so prepaid tuition and temporary cash spikes are not mistaken for free cash.
Next payroll and payroll-tax dates
Debt payments due within 60 days
Tax-reserve balance versus target
Reinvestment and repair reserve
Upcoming refunds, credits, and term obligations
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.