Where Does Owner Income Come From in a Nail Salon?
Nail Salon Bundle
A hands-on U.S. nail salon owner can realistically plan around $120,000 to $145,000 a year once a well-run neighborhood salon is stabilized, while weaker demand can push take-home below $30,000 and a high-utilization multi-tech salon can approach $200,000. The reconciled Base case produces $132,216 of annual owner income on $576,000 of annual revenue after a 22% tax reserve and 8% reinvestment reserve. It assumes an owner who still works in and manages the salon, four hired technician-equivalents plus limited support, a roughly $64 blended ticket, and about 29 paid visits per operating day. This is residual owner cash, not revenue, EBITDA, or guaranteed salary: payroll, overhead, marketing, debt service, and reserves are paid first. Additional personal taxes, benefits, retirement contributions, unusual capital replacements, and extra distributions are excluded.
Owner income$132KNet margin23%Revenue for target pay$556KBusiness difficultyModerate
How much could this nail salon model pay the owner?
The Base case uses $48,000 of monthly revenue, an 88% gross margin after supplies and payment processing but before labor, and $26,500 of monthly labor, overhead, marketing, and debt service. That leaves $15,740 before owner reserves and $11,018 after reserves. For payroll, BLS reported $20.87 average hourly earnings for nail-salon employees in April 2026, while the May 2024 occupational median was $16.66 in BLS occupational data. The model uses the higher, newer industry figure as the safer wage anchor.
Owner income calculator
Adjust salon revenue, margins, staffing, overhead, reserves, and target pay to estimate residual owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What actually drives nail salon owner income?
Six variables dominate: paid visits per technician-hour, blended ticket, labor productivity, direct costs, fixed overhead, and repeat booking. BLS projects manicurist and pedicurist employment to grow 7% from 2024 to 2034, but stronger labor demand can also make staffing harder. Owner cash improves when booked hours become repeat, adequately priced visits without payroll or empty stations growing faster than sales.
1
Visits per productive station
29 visits/day base
At about 26 operating days a month, moving from 25 to 29 paid visits a day at the same $64 ticket adds roughly $6,656 of monthly revenue before incremental supplies and labor.
2
Blended client ticket
$64 base ticket
Square cites standard manicure pricing of $15-$40, standard pedicures of $30-$50, and premium services of $35-$80, making service mix and add-ons a major revenue lever.
3
Labor productivity
$20.87/hour anchor
The Base payroll uses the April 2026 BLS nail-salon hourly earnings level as a conservative wage anchor; schedule efficiency matters because owner pay begins only after hired payroll is covered.
4
Direct-cost control
88% gross margin
The model assumes 12% of sales for products, disposables, retail COGS, and payment processing before labor, with card fees alone capable of taking roughly 3% of a typical ticket.
5
Occupancy and overhead
$8.5K/month base
Rent, utilities, insurance, sanitation, booking software, maintenance, and compliance must be paid even when chairs are empty, so excess space can erase owner distributions quickly.
6
Repeat booking and CAC
4% marketing base
A $2,000 monthly marketing budget is only economical if acquired clients rebook. Retention reduces the amount of paid demand needed to keep the same station utilization.
Want to test nail salon pricing, staffing, and cash flow in a full forecast?
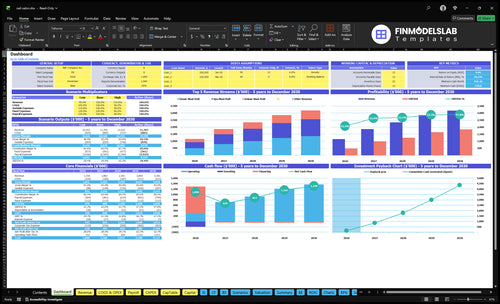
The Nail Salon Five-Year Financial Model Template provides a dashboard for changing service volume, pricing, payroll, costs, funding, and scenario assumptions. The dashboard preview is useful for pressure-testing whether a higher visit target actually produces more owner cash after added technicians, supplies, debt, and working-capital needs rather than simply producing a larger revenue number.
What revenue level supports a six-figure nail salon owner income?
In the Base case, about $556,000 of annualized revenue supports a $120,000 annual owner-pay target after reserves; the $576,000 sales plan leaves a small cushion. Monthly break-even before owner income or reserves is about $30,114: $26,500 of operating costs divided by the 88% gross margin. That follows the SBA break-even framework. Breaking even and paying the owner well are therefore very different thresholds.
Build revenue from client math
Low: about 21 visits a day at a $55 blended ticket produces roughly $30,000 a month.
Base: about 29 visits a day at a $64 blended ticket produces about $48,000 a month.
High: about 43 visits a day at a $72 blended ticket produces about $80,000 a month and requires more technicians and support coverage.
Price the mix, not one service
Square's 2026 U.S. nail-salon guide lists standard manicures at $15-$40 and standard pedicures at $30-$50.
Premium gel or detailed services are listed at $35-$80, so the blended ticket can rise without increasing chair count if clients trade up.
Local market pricing matters: a national model should not assume New York or Miami prices with lower-cost suburban overhead.
At a $64 blended ticket, a $4 increase across 750 monthly visits adds about $3,000 of monthly revenue and roughly $2,640 of gross profit at an 88% gross margin before any extra labor. Adding 100 visits at the old price adds $6,400 of revenue but may require more technician-hours, so track both revenue per visit and revenue per paid labor hour.
How much do staffing and owner labor change take-home?
Staffing is the largest controllable swing factor. Square says labor can approach 50% of total salon expenses, and BLS shows meaningful wage variation. The Base case budgets $14,000 per month for hired labor and treats owner compensation separately. Employer payroll costs add to wages: the IRS 2026 Employer's Tax Guide sets employer Social Security at 6.2% and Medicare at 1.45%, before unemployment insurance, workers' compensation, benefits, and state-specific costs.
Owner-operated salon
The owner fills appointments, manages scheduling, orders supplies, and handles quality control.
Owner labor is not inside the calculator's labor-cost field; the residual owner-income output compensates both management work and ownership risk.
This structure can produce stronger owner cash, but it is not passive income and may depend heavily on the owner's book of clients.
Manager-run salon
A manager or senior lead must replace scheduling, inventory, customer-recovery, opening, and closing work the owner stops doing.
If manager coverage costs $4,500-$6,000 a month fully loaded, owner income falls by that amount before reserves unless volume or pricing rises.
The business becomes more transferable, but the owner's distribution must be supported by employee-generated gross profit rather than unpaid owner labor.
For owner income, track hired payroll against sales generated by hired providers. If payroll rises by $3,000 a month and added capacity creates only $3,500 of gross profit, the extra station increases revenue but barely improves distributable cash.
How should salary, distributions, and safe cash be separated?
Revenue is customer money collected; gross profit is revenue after direct supplies and processing; operating profit remains after hired labor and overhead; owner cash remains only after debt service and prudent reserves. Entity structure then determines how that owner cash is paid. The IRS guidance on paying yourself explains that compensation rules depend on business structure, and for an S corporation the IRS requires reasonable compensation for shareholder-employees before non-wage distributions for services.
What the Base case earns
$48,000 monthly revenue becomes $42,240 after 12% modeled direct costs.
$26,500 of hired labor, fixed overhead, marketing, and debt service leaves $15,740 before owner reserves.
A $4,722 tax and reinvestment reserve leaves $11,018 of modeled owner income for the month.
What must stay in the business
Sales tax collected for a taxing authority is never owner income.
Payroll, payroll taxes, rent, card settlements, debt payments, and product invoices have priority over discretionary draws.
Keep a replacement and working-capital reserve for pedicure chairs, HVAC or ventilation, deposits, slow weeks, repairs, and new-hire ramp time.
Compliance costs are not optional. New York's Department of State licensing page shows separate operator and business applications, illustrating why the budget must follow the salon's actual jurisdiction. Ventilation can also affect build-out and maintenance: OSHA's nail-salon chemical-hazard guidance calls ventilation the best way to reduce airborne chemical levels and cites NIOSH tests showing exhaust systems may reduce exposure by at least 50%.
Key Takeaways
A stabilized owner-operated salon can support about $132,000 of modeled annual owner income on $576,000 of sales in this Base case, but that is residual cash after reserves, not guaranteed salary.
The Base business breaks even near $30,000 of monthly sales before owner pay; supporting a $10,000 monthly owner target requires roughly $46,347 of monthly revenue under the same cost structure.
Price and technician utilization usually move owner income faster than adding space: empty stations create rent and payroll exposure without revenue.
Separate owner labor from hired payroll, and keep tax, reinvestment, compliance, and replacement cash in the business before declaring a distribution safe.
What do low, base, and high owner-income scenarios look like?
The three cases change demand, pricing, labor, overhead, marketing, financing, and reserves together. Fixed costs remain sticky in the Low case, while the High case adds payroll and support costs. Modeled owner income is $29,304, $132,216, and $199,584 a year after reserves; these are planning outputs, not market averages.
Owner income scenarios
Compare demand, staffing, cost pressure, and residual owner cash across three coherent operating cases.
Nail Salon low, base, and high owner-income planning cases
Scenario attribute
Low CaseConservative
Base CasePlanning case
High CaseStretch
Launch modelDemand and service pace
About 21 visits/day
$55 blended ticket
$30K monthly revenue
About 29 visits/day
$64 blended ticket
$48K monthly revenue
About 43 visits/day
$72 blended ticket
$80K monthly revenue
Typical setupOwner and staffing model
Owner on the floor
About 3 hired tech equivalents
Lean support coverage
Owner works and manages
About 4 hired tech equivalents
Limited support coverage
Larger provider team
About 7 productive tech equivalents
Lead/front-desk coverage
Cost driversMonthly operating pressure
86% gross margin
$11K labor
$11.5K other operating costs
88% gross margin
$14K labor
$12.5K other operating costs
89% gross margin
$28K labor
$18K other operating costs
Owner income rangeAfter modeled tax + reinvestment reserves
$29,304
20% tax reserve + 6% reinvestment reserve
$132,216
22% tax reserve + 8% reinvestment reserve
$199,584
24% tax reserve + 10% reinvestment reserve
Best fitHow to use the case
Stress-test a slow ramp, weak repeat booking, or underused chairs while fixed costs remain sticky.
Plan around a stabilized owner-operated neighborhood salon with balanced pricing, staffing, and repeat demand.
Test a high-utilization salon where stronger pricing is supported by enough labor, support, marketing, and overhead.
i
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six nail salon income drivers deserve weekly attention?
These six drivers belong on the weekly operating dashboard because each connects appointment-book decisions to cash. The goal is balanced performance: strong ticket value, productive stations, controlled labor and direct costs, proportionate overhead, and enough repeat demand to reduce paid acquisition.
1. Visits per productive station
Turn booked hours into paid visits
Capacity is the first ceiling because every manicure, pedicure, fill, or enhancement consumes technician time. The Base case needs roughly 750 paid visits a month, or about 29 per operating day. Spread across an owner-technician and four hired technician-equivalents, that is about 5.8 visits per provider-day. The number is plausible only if the mix includes shorter services and schedules are staggered; a salon dominated by long acrylic sets would need more labor hours for the same visit count.
Here's the quick math: four extra paid visits a day at the Base $64 ticket produce about $6,656 of added monthly revenue over 26 days. At an 88% gross margin, that is roughly $5,857 before any extra payroll. If the existing team has open slots, much of that can reach operating profit. If the extra visits require another full technician, the gain must first cover the added wage burden.
Track utilization, not just bookings
Count paid service hours against staffed service hours and separate cancellations, no-shows, and unfilled capacity.
Paid visits per provider-day
Booked hours ÷ staffed hours
No-show and late-cancel rate
Revenue per staffed hour
2. Blended client ticket
Raise value per visit before adding chairs
Price is the cleanest leverage when the calendar is already busy. Square's U.S. nail-salon guide lists standard manicures at $15-$40, standard pedicures at $30-$50, and premium services such as gel or intricate nail art at $35-$80. The Base model's $64 blended ticket therefore assumes a mix of lower-priced core services and higher-value pedicures, gel, enhancements, art, removals, repairs, and modest retail or add-ons.
A $4 ticket lift across 750 monthly visits is $3,000 of extra monthly sales. With 12% direct costs, approximately $2,640 remains before labor and fixed costs. That lift can come from a modest price change, a better service mix, or add-ons, but the owner should not force every client into a premium package. Watch rebooking and cancellation behavior after price changes to make sure the nominal ticket gain is not offset by lost frequency.
Track realized price by service
Menu prices are not enough; discounts, loyalty credits, comps, and service mix determine the actual paid ticket.
Average ticket by technician
Average ticket by service category
Add-on attachment rate
Discounts as a percent of gross service sales
3. Labor productivity and owner role
Pay for productive capacity, not empty shifts
Labor is the most important expense because revenue disappears when a licensed technician is unavailable, but payroll also becomes dangerous when staff hours are scheduled ahead of demand. BLS reports that manicurists and pedicurists must typically complete a state-approved program and pass a state exam for licensure, and its April 2026 nail-salon industry data shows average hourly earnings of $20.87. The Base case uses $14,000 a month for hired labor, employer taxes, and limited support coverage, while owner labor stays outside payroll so it is not counted twice.
The owner-operated assumption matters. If the owner stops taking clients and hires a $5,000-per-month manager or lead to absorb management work, the salon needs about $5,682 of additional monthly revenue at an 88% gross margin just to cover that operating cost before owner reserves. The owner may prefer that trade for a more transferable business, but it changes the economics from active owner income toward true ownership return.
Track sales per paid labor dollar
Measure whether the incremental payroll schedule creates enough gross profit to justify itself.
Hired payroll ÷ revenue
Revenue per paid technician hour
Service hours sold per scheduled hour
Owner service hours versus management hours
4. Direct supplies and payment costs
Protect gross margin before payroll starts
The calculator defines gross margin before labor, so the Base 88% margin means 12% of sales is reserved for polish, gel, acrylic or dip materials, disposables, retail product cost, and payment processing. This is a planning assumption rather than a universal industry benchmark because service mix changes material intensity. A gel manicure, pedicure, full set, and simple polish do not consume the same products or technician time.
Card processing is a visible part of that 12%. Square currently lists an in-person Free-plan rate of 2.6% plus 15 cents per transaction. At a $64 ticket, that is about $1.81, or roughly 2.8%, before any other merchant costs. If direct costs rise from 12% to 15% on $48,000 of monthly sales, gross profit falls by $1,440 a month. After a 30% combined tax and reinvestment reserve in the Base model, that can reduce modeled owner cash by roughly $1,008 monthly.
Track cost per service family
Do not rely only on total supply purchases; connect product usage to the service that generates the sale.
Consumables as percent of service sales
Retail gross margin
Merchant fees as percent of collected revenue
Waste, breakage, and expired inventory
5. Occupancy, compliance, and fixed overhead
Keep the box smaller than the demand risk
The Base case assumes $8,500 per month of fixed overhead for a modest neighborhood salon, including rent, utilities, insurance, software, sanitation, laundry, licenses, maintenance, and administration. That is a planning assumption because U.S. commercial rent varies too widely to use one national number responsibly. The important decision is whether each added square foot supports another productive station, safe circulation, storage, sanitation, or ventilation rather than simply increasing rent.
Compliance can also create real capital and maintenance costs. State licensing rules vary, and workplace health requirements cannot be ignored when evaluating a cheap space. OSHA's chemical-hazard guidance says ventilation is the best way to lower salon chemical levels and notes that poor ventilation can increase accumulated exposure. A salon with inadequate exhaust may need landlord-approved HVAC or local-exhaust work, so build-out contingencies and maintenance reserves belong in owner-income planning rather than being treated as one-time surprises.
Track fixed cost per productive station
Separate unavoidable occupancy costs from optional amenities and test every expansion against conservative station utilization.
Rent and occupancy as percent of sales
Fixed overhead per productive station
Maintenance and ventilation reserve
License, inspection, and insurance renewal calendar
6. Repeat booking and customer acquisition
Make the second visit cheaper than the first
The Base model gives marketing a separate $2,000 monthly budget, about 4.2% of sales. That amount is not a benchmark; it is a planning allowance for a salon that still needs local acquisition while building repeat demand. The crucial question is not whether marketing produces clicks or first-time bookings, but whether a new client returns often enough to repay acquisition cost after direct supplies and technician payroll.
Suppose a first-time client costs $35 to acquire and produces a $64 ticket. At an 88% gross margin, the visit creates about $56 before labor, so acquisition can consume much of the first visit's contribution once technician pay is included. Rebooked second and third visits are more valuable. Square notes that booking tools can use prepayment or cards on file to reduce no-shows, so connect marketing spend to rebooked revenue rather than new-client count alone.
Track retention by acquisition source
Keep channels that create repeat clients and cut channels that create discounted one-time visits with weak contribution.
New-client acquisition cost
Rebooking rate before checkout
Second-visit rate within the normal service cycle
90-day revenue per new client
Owner income becomes durable when repeat demand fills the calendar before paid marketing has to do it. That stability also makes payroll scheduling safer, reduces discounting pressure, and lets the owner reserve more cash for taxes, replacements, and future growth instead of covering empty chairs.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.