How Much Profit Can the Owner Keep from a Quilt Shop?
Quilt Shop Bundle
An owner-operated U.S. quilt shop can reasonably model about $26,520 to $179,400 a year in owner income after planned tax and reinvestment reserves, with a base case of $95,760 on $960,000 of annual revenue. The scope is a specialty retailer selling quilting fabric, notions, kits, patterns, classes and online orders, consistent with the Census category for Sewing, Needlework, and Piece Goods Retailers. The base case uses a 48% gross margin, $14,000 monthly hired payroll, $8,000 fixed overhead, $2,500 marketing and $2,500 debt service. The owner works in the business, so owner labor is not in payroll. The $95,760 is residual owner income after a 22% tax reserve and 8% reinvestment reserve; it is not a guaranteed salary or distribution and excludes final personal tax reconciliation and unusually large unmodeled capital needs.
Owner income$96KNet margin10%Revenue for target pay$973KBusiness difficultyModerate
How much can a quilt shop owner make in the United States?
Owner income can be modest during a slow launch and reach six figures only after traffic, margin and inventory discipline improve. A 2025 industry survey reported a roughly $4.5 billion quilting market, 9 to 11 million active consumers, and 64% of surveyed quilters preferring local shops; it also reported more stash use as costs rose. See the 2025 Quilter's Survey summary.
The calculator treats owner income as the residual after product margin, hired labor, fixed overhead, marketing, debt service and reserves. Gross profit is sales minus direct merchandise costs. Operating profit here is gross profit minus hired payroll and operating costs before reserves. EBITDA is an accounting measure and may differ. Owner salary pays for labor performed; a draw or distribution transfers residual equity cash. A safe distribution is cash left after taxes, restocking, debt and near-term payroll are protected.
Owner income calculator
Estimate owner income from quilt-shop sales, product margin, staffing, overhead, reserves, debt service, and target pay.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Traffic and repeat buying
44 orders/day
The $80K base month needs roughly 1,140 transactions at a $70 blended ticket; repeat local customers and online reorders determine whether that volume is sustainable.
2
Gross margin
48%
Every margin point on $960K of annual sales is $9,600 of gross profit before payroll, overhead and reserves.
3
Average ticket and mix
$70 base
Kits, backing, thread, rulers, classes and project bundles can raise dollars per visit without requiring the same increase in foot traffic.
4
Labor and owner coverage
$14K/mo
The base case assumes the owner manages buying and the floor; adding a hired manager materially reduces residual owner cash unless sales rise.
5
Inventory turns
3.5x target
At base-case COGS, moving from 3.5 to 2.5 inventory turns can tie up roughly $57K more cash at cost.
6
Fixed cash burden
$13K/mo
Fixed overhead, marketing and debt total $13K before payroll; lease choices and financing terms set a hard monthly floor.
Want to test the fabric, payroll, and inventory assumptions in a full forecast?
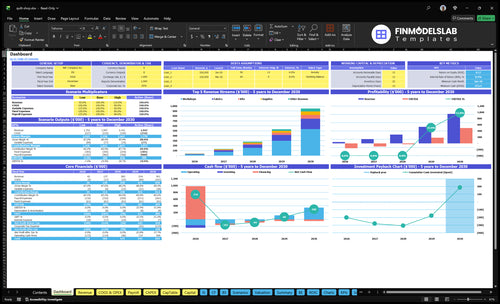
The Quilt Shop Financial Projections Template in Excel shows a business-specific dashboard where revenue, margins, operating costs, cash flow and scenarios can be viewed together. For owner-income planning, the useful test is whether stronger sales also require more inventory, staff and marketing, rather than assuming every extra sales dollar becomes distributable cash.
Stress-test low, base and high revenue paths.
Compare gross margin with payroll and operating-cost growth.
Watch cash runway when inventory purchases lead the sales season.
What sales volume supports a $100K quilt-shop owner income?
In the base case, the shop needs about $81,051 a month, or $972,612 a year, to support an $8,333 monthly owner-income target after the 22% tax and 8% reinvestment reserves. That is only about $1,051 above the modeled $80,000 month, which is why modest changes in transaction count or ticket can flip the target-pay gap. A current retail price check shows common quilting cotton on a major U.S. specialty site around $8.98 to $12.98 per yard, with many designer prints around $12.48 to $12.98, so a $70 blended transaction usually means multiple yards, a kit, notions, backing, thread, or a class rather than one yard of fabric. See the current quilting fabric yardage listings.
At a $70 blended ticket, $80,000 of monthly sales is about 1,143 transactions, or roughly 44 orders a day across 26 open days. At $60, the same revenue needs about 1,333 transactions; at $80, about 1,000. These are planning assumptions, not an industry average. Track transactions, average ticket, repeat customers, class conversion and online reorders instead of revenue alone.
Base sales math
$80,000 average monthly revenue.
About $70 blended transaction value.
Roughly 1,143 monthly transactions.
About 44 transactions per 26-day month.
Break-even before owner pay
$27,000 monthly operating costs.
48% gross margin in the base case.
About $56,250 monthly revenue covers those costs.
Owner cash begins only after that floor and the modeled reserves.
What gross margin can a quilt shop realistically protect?
A defensible planning range is roughly 45% to 52% after merchandise cost and other non-labor direct costs, with 48% used here as the base assumption. That is not presented as a universal quilt-shop benchmark. It is anchored to a fabric-and-crafts retail proxy: JOANN reported a 52.3% gross margin in its third quarter of fiscal 2024, while also noting that shipping, product cost, promotions and inventory decisions affect margin. Because a local quilt shop has less buying scale but may have a richer mix of classes, kits and curated products, the model deliberately uses a wider, more conservative band. See the JOANN fiscal 2024 third-quarter filing.
The calculator keeps payroll out of gross margin so merchandise economics and staffing stay separate. IRS guidance says small merchandisers generally do not charge ordinary retail labor to COGS and that freight-in on resale merchandise belongs in COGS. See IRS Publication 334. Classify purchase cost, inbound freight, card fees and shrink consistently, then keep sales-floor wages in laborCost to avoid double counting.
What one margin point is worth
1% of $960,000 annual sales equals $9,600.
At unchanged overhead, that increase reaches pre-reserve profit.
After 30% combined base reserves, about $6,720 remains for owner cash.
Markdowns, freight and shrink can erase the gain quickly.
Protect margin by category
Track fabric, precuts, kits, notions and classes separately.
Measure realized margin after coupons and loyalty discounts.
Put inbound freight and card processing in one consistent place.
Review aged bolts before markdowns become the only exit.
Can a quilt shop run without the owner on the floor?
Yes, but a manager-run shop needs enough extra gross profit to buy back the owner's labor. The base case assumes the owner acts as general manager, buyer, merchandiser and part of the selling team, so the $14,000 monthly labor line is hired staff only. In 2025, BLS reported median retail wages of $17.01 an hour for retail salespersons and $23.18 for first-line retail supervisors/managers. See the BLS retail wage data. Those national medians are a starting point; actual wages vary sharply by city and labor market.
Adding about $5,000 a month of loaded manager cost, with every other base assumption unchanged, cuts monthly owner income from $7,980 to about $4,480, or from $95,760 to $53,760 a year. The IRS sets the 2026 employer Social Security rate at 6.2% and Medicare at 1.45%, before state unemployment, workers' compensation and benefits; see IRS Publication 15. A manager may still not replace the owner's buying, teaching or e-commerce work.
Owner-operated base
Owner covers management and buying.
$14,000 monthly hired payroll.
$95,760 annual modeled owner income after reserves.
Owner income includes compensation for real labor performed.
Manager-run adjustment
Add roughly $5,000 monthly loaded manager cost as a planning test.
Base owner income falls to about $53,760 annually.
Additional buyer or instructor coverage may reduce it further.
Call the remainder passive income only after replacement labor is funded.
Why can a profitable quilt shop still feel cash-poor?
Because fabric is cash before it becomes revenue. The business may report gross profit while cash is sitting in bolts, precuts, kits and notions that have not sold yet. IRS retail inventory guidance ties purchases and closing inventory directly to cost of goods sold, so inventory accounting and cash movement happen on different timing. In the base case, annual COGS is about $499,200. At a planning target of 3.5 inventory turns, average inventory at cost is about $142,600; at 2.5 turns, it rises to nearly $199,700, tying up roughly $57,000 more cash without increasing annual sales.
Debt adds another cash claim. SBA guidance says most 7(a) term loans use monthly principal-and-interest payments from business cash flow; see the SBA 7(a) loan guidance. This model therefore separates $2,500 of monthly debt service. Retail licensing and permit requirements vary by state and locality, according to the SBA licenses and permits guide, so local compliance costs belong in overhead rather than a generic national allowance.
Cash gets committed first
Seasonal collections often arrive before peak selling weeks.
Slow bolts may need markdowns to convert back to cash.
Online growth can require deeper inventory and fulfillment labor.
Classes can create deposits now but future delivery obligations later.
What gets paid before a safe draw
Merchandise suppliers and freight.
Payroll, rent and recurring overhead.
Marketing and monthly debt service.
Tax reserve, restocking reserve and near-term capital needs.
Key Takeaways
The base model produces $95,760 of annual owner income from $960,000 of sales after a 30% combined tax and reinvestment reserve.
Base operating break-even before owner income is about $56,250 a month; supporting a $100K annual owner-income target requires about $81,051 a month.
The owner-operated assumption matters: adding manager replacement cost can cut distributable cash materially even when sales are unchanged.
Inventory velocity is as important as accounting margin because slow fabric can trap tens of thousands of dollars that cannot safely be distributed.
What do low, base, and high quilt-shop owner-income cases look like?
These scenarios change revenue, margin, payroll, overhead, marketing, debt and reserves together. The low case assumes weaker traffic and more markdown pressure. The high case assumes stronger local, class and online sales while paying for materially more labor, marketing and overhead. They are planning cases, not earnings promises.
Owner income scenarios
Low, base and high cases reconcile to the calculator presets and show owner income after each scenario's modeled tax and reinvestment reserves.
Quilt Shop low, base and high owner-income planning cases
Scenario
Low CaseLower income
Base CasePlanning case
High CaseHigher scale
Launch modelTraffic and channel maturity
Owner-heavy neighborhood shop with slower traffic and discount pressure.
Owner-operated specialty shop with established local traffic, classes and a modest online channel.
Established destination shop with stronger e-commerce, class calendar and regional customer reach.
Owner income rangeAfter modeled tax and reinvestment reserves
$26,520
Annual owner income after modeled reserves.
$95,760
Annual owner income after modeled reserves.
$179,400
Annual owner income after modeled reserves.
Best fitHow to use the case
Stress-test a launch, weak season, or store with excess inventory and thin traffic.
Use for a stable owner-operated shop that has repeat local demand and disciplined buying.
Use only when added traffic, classes and e-commerce support the extra labor and marketing required.
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six quilt-shop income drivers that matter most?
A quilt shop creates owner income by turning specialized assortment and community demand into repeat, profitable transactions without letting payroll or inventory outrun sales. The six drivers below use the same model assumptions.
1. Traffic and repeat buying
Build the month from transactions, not hope
The base case needs $80,000 monthly revenue. At a $70 blended transaction, that is about 1,143 orders, or 44 per day over 26 open days. The 2025 Quilter's Survey favors a local-store strategy, but its softer-market and stash-use findings mean demand still has to be earned.
Adding five $70 transactions per day for 26 days adds $9,100 of monthly revenue and $4,368 of gross profit at a 48% margin. If staffing does not increase, about $3,058 could remain after the base reserves. New labor must be subtracted first.
Track demand quality weekly
Traffic is valuable only when it produces repeatable gross profit.
Transactions by day and channel.
Repeat-customer purchase frequency.
Class attendance that converts to merchandise.
Revenue per email or local-event campaign.
Use a four-week rolling average so one shop hop or holiday weekend does not distort the run rate.
2. Gross margin and markdown discipline
Protect the dollars left after product cost
The plan uses a 48% gross margin, with 45% low and 52% high. The JOANN filing's 52.3% quarter is only an adjacent large-chain proxy; a local shop should use its own realized margin by category because buying scale, freight, discounts and mix differ.
At $960,000 annual revenue, one margin point equals $9,600 of gross profit and about $6,720 after the base reserves if other costs stay fixed. A drop from 48% to 45% cuts annual gross profit by $28,800 before reserves, so promotions must create enough volume to replace that contribution.
Watch realized margin, not tag margin
List price is not the number that funds payroll.
Gross margin by fabric, kit, notion and class.
Discount dollars as a percent of sales.
Inbound freight per merchandise dollar.
Shrink and damaged inventory write-offs.
Review margin after coupons, loyalty rewards and clearance so buying decisions use the cash result customers actually created.
3. Average ticket and product mix
Sell the whole project, not a single cut
Many current designer quilting cotton listings sit around $12.48 to $12.98 per yard, with basics below $9. Three yards at $12.48 is $37.44 before thread, backing, batting or a pattern, so project bundles can lift the ticket toward the $70 base assumption without another customer.
With 1,143 monthly transactions, lifting the blended ticket from $70 to $75 adds about $5,715 of revenue and $2,743 of gross profit. After base reserves and before extra labor, roughly $1,920 could reach owner income. Useful attachment selling is safer than blanket price increases.
Measure project economics
Ticket growth should come with stable conversion and margin.
Average transaction by customer segment.
Units and yards per transaction.
Kit, notion and backing attachment rate.
Class-to-retail spend within 30 days.
Compare average ticket with gross margin so a bigger basket created by heavy discounting is not mistaken for better economics.
4. Labor efficiency and the owner's role
Price owner labor before calling profit passive
BLS retail wage data put the 2025 median at $17.01 an hour for retail salespersons and $23.18 for first-line retail supervisors. The model's $14,000 monthly labor budget covers hired sales, cutting, fulfillment and class support while the owner remains the working manager and buyer. It is not passive ownership.
A $5,000 monthly loaded manager layer drops base annual owner income from $95,760 to about $53,760. If the owner exits day-to-day work, replacement management, buying and teaching hours must be modeled. Salary for labor and distributions from residual profit are different; counting both without replacement labor overstates passive income.
Schedule to gross profit per labor hour
Labor should flex with traffic and class demand while maintaining service.
Sales and gross profit per paid hour.
Owner hours by management, buying and teaching.
Overtime and shift overlap.
Payroll as a percent of revenue by month.
Record owner hours even when no paycheck is issued; otherwise the business can look profitable only because the owner is donating labor.
5. Inventory turns and cash conversion
Make every bolt earn its shelf space
Base annual COGS is $499,200. At a planning 3.5x inventory turn, average stock at cost is about $142,600; at 2.5x, nearly $199,700. The roughly $57,000 difference is cash the owner cannot distribute while it remains in stock. IRS inventory guidance likewise ties purchases, freight-in and ending inventory to COGS.
Segment new collections, basics, kits and aged inventory. Buying too shallow loses sales; buying too deep forces clearance. Seasonal and block-of-the-month commitments need separate purchase plans because supplier cash outflows can lead customer collections.
Run an aging report every month
Inventory age explains why a profitable P&L can coexist with a thin bank balance.
Inventory turns by category.
Stock older than 90, 180 and 365 days.
Open-to-buy dollars versus cash reserve.
Markdown recovery versus original gross margin.
Tie purchase orders to a cash forecast so the owner does not distribute money that is already committed to incoming collections.
6. Fixed overhead, marketing and debt service
Know the monthly floor before setting owner draws
The base model carries $8,000 fixed overhead, $2,500 marketing and $2,500 debt service before payroll, a $13,000 non-labor burden. With $14,000 hired labor, operating costs are $27,000. At a 48% gross margin, about $56,250 of monthly revenue is needed before owner income and reserves.
Marketing stays separate so its return can be measured; the $2,500 base assumption is 3.1% of monthly revenue. Debt is separate because principal and interest are cash claims. The reinvestment reserve protects inventory and equipment. Residual cash is distributable only after those claims are funded.
Set a distribution gate
Use a monthly checklist before moving cash to the owner.
Next four weeks of payroll and rent funded.
Supplier invoices and open purchase orders covered.
Debt service and tax reserve transferred.
Inventory and repair reserve still above the minimum.
When any gate fails, reduce the draw even if the income statement shows a profit. That is the difference between accounting earnings and cash the owner can safely take home.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.