How Much Remote Start Installation Owners Make: $143K Year 1
Remote Car Start Installation Bundle
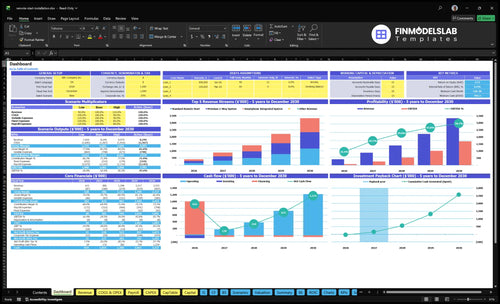
A remote start installation business owner can model about $143K before taxes in Year 1 if they fill the general manager role and the business also produces the modeled $68K EBITDA That is based on researched planning assumptions, not a guaranteed paycheck or distribution Revenue grows from $415K in Year 1 to $333M in Year 5, while EBITDA grows from $68K to $169M What this estimate hides is timing: the model needs $793K minimum cash in Month 2 and reaches payback after 18 months
Owner income$143KNet margin16%–51%Revenue for target pay$873KBusiness difficultyHard
Want to test your owner-pay number?
Owner income calculator
Estimate owner take-home and target-pay gap from revenue, margin, costs, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Want the six main income drivers?
1
Install Volume
96-592/mo
More monthly installs spread rent and admin across more jobs, so owner take-home rises fastest when bays stay full.
2
Ticket Size
$360-$469
A higher mix of premium and smartphone systems lifts average ticket, which grows revenue without adding the same number of jobs.
3
Parts Margin
79%-82%
Hardware kits and supplies stay near one-fifth of sales, so most of each job is left to cover labor, overhead, and profit.
4
Tech Capacity
$149K-$545K
Payroll climbs as you add technicians and support, so output per labor dollar has a big effect on owner income.
5
Fixed Overhead
$42K
Rent, software, insurance, and admin sit near $42K a year, so once volume is in place, extra installs fall more cleanly to profit.
6
Lead Flow
$65->$45
Seasonal swings and a lower CAC push more booked jobs per marketing dollar, which helps protect margin when demand softens.
How does the Remote Car Start Installation model show owner income?
Is mobile or shop-based remote start installation more profitable?
Mobile Remote Car Start Installation is usually the leaner setup because it avoids shop rent, but it picks up fuel, vehicle maintenance, travel time, fleet insurance, and scheduling friction. In this model, you already have $1,200 a month for storage and office rent, $800 for fleet vehicle insurance, and 50% higher Year 1 fuel and maintenance, so the savings can shrink fast. A shop can improve bay workflow and customer trust, but it also raises fixed overhead, and dealer accounts can smooth lead flow while putting pressure on price and timing.
Mobile model costs
Lower rent than a shop
Fuel and maintenance add up
50% higher Year 1 fuel and maintenance
Travel and scheduling hurt throughput
Shop model tradeoffs
Better bay workflow
Stronger customer trust
Higher fixed overhead
Dealer accounts may help, but hiring techs adds payroll, training, and quality-control risk
Can a remote start installation business support an owner?
Yes, Remote Car Start Installation can support an owner-manager, but only after gross profit covers payroll, overhead, marketing, and rework risk; see How Much To Start Remote Car Start Installation Business? for the startup cost view. In Year 1, the model shows $415K revenue, a $75K general manager salary, and $68K EBITDA, but EBITDA is not automatic take-home because taxes, reserves, debt service, and capex come next.
Owner Pay Test
$415K Year 1 revenue
$75K manager salary included
$68K EBITDA before owner extras
16.4% EBITDA margin
Risk Checks
$3,500 monthly overhead before payroll
$42K annual fixed overhead
Warranty callbacks tighten cash
Slow onboarding delays reliable pay
What profit margin can remote start installation earn?
Remote Car Start Installation can post a strong parts margin, but owner income is much lower once labor and overhead hit. If you want the launch steps, see How Do I Launch Remote Car Start Installation Business? In the model, Year 1 gross margin is about 79.0% after hardware kits, harnesses, consumables, and shop supplies, and EBITDA margin is about 16.4% before labor, marketing, insurance, rent, and admin payroll.
Parts margin
79.0% gross margin in Year 1
81.8% gross margin in Year 5
Lower supply mix lifts margin
Cheap kits can raise rework
Owner income
16.4% EBITDA margin in Year 1
50.7% EBITDA margin in Year 5
Labor and overhead cut take-home
Callbacks can eat installer time
Key Takeaways
Volume matters only when quality stays high.
Ticket growth must cover extra hours and hardware.
Payroll and overhead can outrun gross profit.
Plan cash for winter dips and bottlenecks.
Compare lean, base, and high owner-income outcomes
Owner income scenarios
Owner income shifts fast in this model because volume, ticket mix, staffing, and marketing spend all change as the shop ramps. Early ramp, multi-tech growth, and scaled operations produce very different take-home paths.
Three planning cases for owner take-home.
Scenario
Low CaseEarly ramp
Base CaseMulti-tech
High CaseScaled operation
Launch model
This is the cautious Year 1 case with modest volume and a small owner take-home path.
This is the modeled Year 3 case with steady growth and a more established owner income path.
This is the stronger Year 5 case with the highest modeled owner income path.
Typical setup
Year 1 runs at about $415K revenue, about 96 installs a month, and $68K EBITDA while the owner takes a $75K general manager salary.
Year 3 runs at about $1.398M revenue and $545K EBITDA with a multi-tech team and fuller schedule density.
Year 5 reaches about $3.333M revenue and $1.691M EBITDA with a scaled crew and higher job throughput.
Cost drivers
Early ramp demand
$360 average ticket
96 installs/month
owner salary
fixed overhead
Higher install count
multi-tech labor
stronger ticket mix
marketing spend
fuel and processing fees
Scaled install volume
larger crew
premium mix
marketing spend
capacity utilization
Owner income rangeBefore owner reserves
$143KLean take-home
$545KModeled income
$1.69MUpside income
Best fit
Use this if you want a conservative Year 1 check and a stress test for cash strain during launch.
Use this for a normal growth plan with steady demand and a staffed operation.
Use this to stress-test a full-scale shop with high demand and strong operating execution.
!
Planning note: These scenario ranges are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distributions.
Remote Car Start Installation Core Six Income Drivers
Install Volume And Capacity
Install Volume and Capacity
More installs only help if quality holds. Volume grows from 96 installs per month in Year 1 to 592 installs per month in Year 5, so the owner is trading labor capacity for revenue. If missed appointments, vehicle complexity, or rework rise, the extra sales can still shrink take-home pay through callbacks and wasted technician time.
Capacity depends on install mix and crew size. The model uses 20 standard hours, 30 premium hours, and 35 smartphone hours per job, so each booked job must fit the calendar. More technicians raise throughput, but payroll rises too, so the real test is completed installs per labor dollar, not lead flow.
Track Completed Jobs, Not Just Leads
Track booked jobs, completed jobs, no-show rate, hours per install, and rework rate. Those inputs tell you whether growth is real or just busywork. One clean win: every slot filled with a completed install should cash in without creating a later warranty fix.
Completed installs per tech per week
Average install hours by type
Missed appointment rate
Rework hours
When the calendar looks full, protect margin by tightening dispatch, confirming appointments, and documenting each wiring step. If job quality slips, the business pays twice: once in labor now, and again in rework later. That pulls down gross margin and leaves less cash for the owner’s draw.
Seasonality And Lead Flow
Seasonal Lead Flow
Winter demand can fill the calendar, but the owner still needs cash reserves for slow months. With marketing spend at $125K in Year 1 and $45K in Year 5, customer acquisition cost (CAC) improves from $65 to $45, so lead quality matters as much as lead count.
Dealer relationships, local search leads, referrals, and repeat fleet work are the stabilizers. When weather softens, weaker lead flow cuts booked installs, and that hits owner pay fast because the schedule still carries fixed labor and vehicle time.
Keep Leads Steady Year-Round
Track booked jobs by source, CAC by source, and close rate by month. If one channel keeps CAC near $45 while another drifts above $65, shift spend there and protect the winter calendar with local search and referral follow-up.
Set a peak-season cap on daily installs. When demand spikes, use tighter scheduling so bottlenecks do not turn into overtime, missed appointments, or warranty mistakes that drain margin and delay owner draws.
Parts Cost And Hardware Margin
Parts Cost And Hardware Margin
Parts margin is the gap between what the customer pays and the kit, harness, module, supply, and shipping cost you carry on each job. The disclosed benchmark is tight: hardware kits and wiring harnesses run 180% of revenue in Year 1 and 160% in Year 5, while consumables and shop supplies run 30% and 22%.
Parts margin is not total margin. Labor time, callbacks, payment fees, and travel still cut into profit, so a strong parts spread can still leave weak owner take-home pay. If price moves slower than parts inflation, cash gets squeezed job by job.
Track True Job-Level Parts Spread
Track invoice price against actual kit, harness, module, supply, and shipping cost by vehicle type. Price freight and vehicle-specific modules separately when they change the bill. If a package drifts toward the Year 1 cost pattern, re-quote before it hits volume.
Build a per-job report that includes labor minutes, rework, payment fees, and travel, not just parts gross profit. One clean rule: if the price does not cover parts plus install time, don’t sell it. That protects cash flow and owner pay.
Overhead And Operating Costs
Fixed Cost Drag
Overhead cuts into income every month, even when the schedule is slow. This model carries $3,500 per month in fixed costs for storage and office rent, insurance, software, communication, accounting, legal, and fleet insurance. Mobile work adds fuel and vehicle maintenance at 50% of Year 1 revenue, and payment processing adds another 30%, so owner pay gets squeezed fast.
If volume is weak, those costs hit cash flow before the owner sees a draw. A month with $10,000 in Year 1 revenue would leave $5,000 for fuel and maintenance and $3,000 for card fees, plus the $3,500 fixed base. The risk is simple: scale fixed costs before install volume and close rate can cover them.
Control Cost Per Job
Track overhead as cost per install, not just a monthly bill. Watch installs completed, close rate, average ticket, and payment fee rate together, because weak conversion makes fixed costs harder to spread. Keep storage, software, and insurance lean until monthly volume can absorb the base load.
Here’s the quick math: if overhead stays at $3,500 and operating drag runs at 80% of Year 1 revenue, each job has to carry enough gross profit to protect cash. Before adding a second vehicle or more admin spend, test whether current install volume can pay the bills and still leave owner income.
Technician Labor Productivity
Technician Labor Productivity
Faster, accurate installs raise capacity and protect margin. In this model, staffing grows from 1 lead technician in Year 1 to 4 lead technicians by Year 5, with junior technicians added after year one, so payroll climbs from $149K to $545K. If install speed improves but wiring mistakes create callbacks, the extra labor cost eats the owner’s take-home profit fast.
The key inputs are hours per install, rework rate, documentation quality, and jobs completed per technician per week. The owner’s income rises when each tech finishes more clean installs without redo work. One clean one-liner: productivity only helps if it holds up after the truck leaves the site.
Measure Output, Then Cut Rework
Track hours per install by system type, plus callback count and why the job failed. If lead technicians are handling more volume, use a simple scorecard for wiring photos, module notes, and vehicle-specific steps so junior techs do not copy bad habits. Better documentation keeps jobs consistent and protects labor margin.
Log jobs per tech per week.
Flag any rework within 30 days.
Review install notes on every job.
Separate fast work from clean work.
Use the staffing ramp to forecast payroll before hiring. With labor rising to $545K by Year 5, a few extra callbacks can wipe out the gain from a faster schedule. If quality slips, the business spends more on paid labor, loses calendar slots, and delays the owner’s profit draw.
Average Ticket And Add-Ons
Average Ticket And Add-Ons
Average ticket is the revenue per completed install, including hardware and labor. Here, the weighted ticket rises from $360 in Year 1 to $469 in Year 5, a $109 gain per job. If labor time and parts cost stay controlled, that extra revenue flows into gross profit and gives the owner more cash for payroll, overhead, and draw.
The mix matters. Standard systems move from 500% in Year 1 to 300% in Year 5, while smartphone-integrated systems rise from 200% to 350%. That can lift ticket size, but only if pricing keeps pace with extra wiring, module cost, and install time. Add-ons help only when the quote covers the extra work.
Price Add-Ons by Time
Track average ticket by system type, plus the attach rate on upgraded modules, bypass parts, and convenience add-ons. The key inputs are completed installs, base price, add-on price, extra labor hours, and hardware cost. If an add-on adds time, price it as time plus parts, not as a flat upsell.
Use a clean quote sheet that separates base install, extra hardware, and extra labor. That protects gross profit when a smartphone integration takes longer than a standard unit. If the team cannot price the extra hours up front, revenue may rise, but owner take-home can still fall.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.