Which Metrics Best Predict Owner Income from a Warehouse Robotics Business?
Warehouse Robotics Bundle
A U.S. owner-led warehouse robotics integrator can realistically produce about $650,000 to $800,000 of annual owner income in a solid base year; the reconciled model below lands at $725,760 on $7.8 million of annual revenue. This scope is a small systems integrator that buys AMRs and controls hardware from third parties, designs the solution, integrates software, installs and commissions it, then sells support—not a venture-scale robot manufacturer. The base case assumes eight accepted deployment projects averaging about $800,000 plus $1.4 million of software, service, upgrades, and support revenue. The largest constraints are hardware and project direct costs, technical payroll, fixed engineering overhead, customer-acquisition spend, financing, and the timing gap between supplier bills and customer milestones. The $725,760 figure is cash available to the active owner after a modeled tax reserve and reinvestment reserve; it is not guaranteed salary, passive income, a GAAP net-profit figure, or a promise that the full amount is legally safe to distribute after actual taxes, capital spending, working-capital swings, or unusual warranty claims.
Owner income$726KNet margin9%Revenue for target pay$6.05MBusiness difficultyHard
How should you read the owner-income estimate?
Read the $725,760 base figure as economic owner take-home after modeled reserves, not as one accounting line. Revenue is $7.8 million. Gross profit is $3.432 million after robot hardware, freight, project materials, payment fees, and other non-labor direct costs. Hired payroll is then $1.44 million, fixed overhead $480,000, marketing $216,000, and debt service $144,000, leaving $1.152 million before reserves. The calculator sets aside $253,440 for taxes and $172,800 for reinvestment, leaving $725,760 for the owner.
That residual contains compensation for the founder's labor plus a return on ownership. For an active S corporation shareholder, the IRS reasonable-compensation guidance requires reasonable compensation for services before non-wage distributions. The model therefore does not claim that $725,760 is all a distribution. It keeps owner pay out of hired labor, then shows the total owner pool; tax and payroll advice should split that pool appropriately. Passive income would be lower if managers must replace the owner.
Owner income calculator
Estimate owner take-home from deployment revenue, project margin, payroll, overhead, financing, reserves, and target pay.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
What are the six quickest owner-income levers?
More owner cash comes from well-scoped deployments, contract values that cover integration risk, productive engineering labor, and collections that arrive before supplier obligations. The International Federation of Robotics 2025 service-robot summary says transportation and logistics was the largest professional service-robot application group in 2024 and logistics robot sales rose 14%. A3 North American robot-order data shows 17,995 robots worth $1.166 billion ordered in the first half of 2026. That indicates demand, not guaranteed sales for a new integrator.
1
Accepted deployments
8 projects/yr
The base model needs eight accepted installations; slipping one $800,000 project can cut revenue by about 10% before any cost response.
2
Contract value
$800K/project
Scope, robot count, controls, software, travel, commissioning, and acceptance terms determine whether a large contract actually contributes cash.
3
Project gross margin
44% pre-payroll
Every point of base gross margin is worth about $78,000 a year before reserves because payroll is modeled separately.
4
Technical labor utilization
$120K/mo
Engineering and field payroll must stay tied to billable design, deployment, commissioning, and support rather than idle bench time.
5
Milestone cash timing
30% deposit target
A planning target of 30% upfront can reduce the amount of robot hardware and travel the owner must finance before acceptance.
6
Recurring service mix
18% of base sales
Software, monitoring, maintenance, spares, and upgrades smooth project lumpiness and can improve margin quality when priced correctly.
Want to test deployment, margin, and cash assumptions in a full forecast?
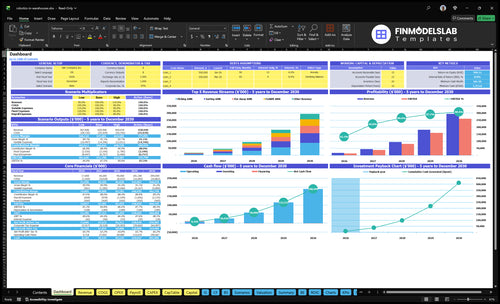
The Editable Robotics In Warehouses Financial Model in Excel includes a business-specific dashboard that can help you test unit sales, project costs, payroll, scenarios, cash flow, and break-even assumptions. For an owner-income plan, focus on whether accepted project volume, pre-payroll gross margin, hiring cadence, and working-capital timing produce enough cash to fund reserves before distributions.
What revenue level supports a meaningful owner draw?
In this model, about $5.18 million of annualized revenue is the operating break-even level before owner take-home and reserves, while about $6.05 million supports the chosen $240,000 annual target owner pay after the modeled 22% tax reserve and 15% reinvestment reserve. The base case at $7.8 million creates a larger cushion. A useful demand check is that 2026 North American robot orders imply roughly $64,800 of reported order value per robot across the broad industrial-robot market; the figure comes from the same A3 order release and is only an adjacent hardware reference, not a warehouse-system contract benchmark.
Base revenue build
8 accepted deployments × about $800,000 = $6.4M
Software, support, spares, upgrades = $1.4M
Total annual revenue = $7.8M
Average month for calculator purposes = $650,000
What one missed project does
One $800,000 slip equals about 10% of base revenue
Payroll and shop costs do not fall immediately
A delayed acceptance can push cash into the next quarter
Track backlog by signed value and expected acceptance month
Marketing is a $18,000 monthly planning assumption, about 2.8% of base revenue, covering trade shows, demos, targeted demand generation, partner activity, and sales collateral. Track qualified pipeline coverage, proposal-to-win rate, sales-engineering hours per win, and expected gross profit per opportunity rather than clicks.
How much margin can warehouse robotics projects support?
The base calculator uses a 44% pre-payroll gross margin, but that percentage is a modeling convention, not a published industry norm. It means 56% of revenue is consumed by robots, controls, freight, project materials, project-specific subcontracting that is not payroll, and other non-labor direct costs. All employee payroll is shown separately. That distinction matters because public warehouse-automation businesses report margins after a different cost classification. For example, Symbotic's 2025 Form 10-K reports $422.6 million of gross profit on $2.247 billion of revenue, about 18.8%, after its cost of revenue. KION's warehouse-automation segment also shows how much operating expense remains below gross profit: its 2025 Supply Chain Solutions results reported a 6.0% adjusted EBIT margin.
Base margin bridge
$7.8M revenue × 44% = $3.432M gross profit
Hired payroll = $1.440M
Other modeled operating cash costs = $840,000
Profit before modeled reserves = $1.152M
Where margin disappears
Robot or battery price changes after quoting
Extra integration work not covered by change orders
Site readiness delays and repeated commissioning trips
Warranty fixes, damaged freight, and acceptance rework
Here's the quick sensitivity: one gross-margin point on $7.8 million is $78,000 before reserves. With the base reserve mix, about 63% of incremental positive profit remains for owner income, or roughly $49,000. A badly scoped project can erase months of distributions despite a large invoice.
Can a warehouse robotics firm run without the owner?
It can, but the base owner-income figure assumes the owner is still a working executive who leads some combination of sales, solution design, vendor negotiation, project review, and key-account management. Replacing that work with senior hires can reduce owner distributions by several hundred thousand dollars unless project volume or margin rises. Technical talent is expensive: 2024 median pay was $101,140 for industrial engineers in BLS wage data, $133,080 for software developers in the BLS software-developer profile, and $70,760 for electro-mechanical and mechatronics technologists and technicians in BLS technician data.
Owner-operated case
Owner carries executive sales and technical-review work
Owner compensation is not buried in hired labor
Residual owner cash includes pay for work plus ownership return
Track owner hours separately from employee billable hours
Manager-run case
Add leadership salary before calling income passive
Keep controls, field service, and project management coverage
Raise recurring revenue to absorb non-owner management
Do not treat founder labor as free margin
Safety limits how aggressively labor can be trimmed. The OSHA robotics standards page points to machine guarding, lockout/tagout, and ANSI/RIA guidance. Integrators still need risk assessment, testing, documentation, training, and acceptance time; cutting those hours can create expensive rework and liability.
Why can a profitable robotics project still squeeze cash?
Because cash timing can move independently of recognized revenue and project margin. A robot fleet may require deposits to suppliers, freight, travel, and field payroll weeks before customer acceptance. As an adjacent public-company example, Symbotic's 2025 filing says customer consideration is often due in advance or at billing milestones and that timing differences can create contract assets or liabilities; it also reports that working-capital changes can become a source or use of operating cash depending on customer-payment timing versus deployment costs. That is why the model's 15% reinvestment reserve should not be treated as optional.
Cash protections
Target a meaningful deposit before hardware orders
Use engineering, delivery, commissioning, and acceptance milestones
Match vendor terms to customer billing where possible
Keep warranty and field-rework cash outside owner draws
Financing reality
Base debt service is a $12,000 monthly planning assumption
Working-capital needs rise with simultaneous deployments
Interest and principal reduce safe cash, even when EBITDA is positive
Test delayed milestone collections before increasing owner draws
Financing helps only when its cash service is modeled. The SBA 7(a) program can finance working capital and machinery or equipment up to $5 million, with monthly principal-and-interest repayment for most term loans. Actual underwriting, rates, collateral, and maturity vary, so the calculator uses a fixed planning payment instead of assuming a current rate.
Key Takeaways
The reconciled base case produces $725,760 of annual owner income on $7.8M of revenue after modeled tax and reinvestment reserves.
About $5.18M annualized revenue covers base operating costs before owner take-home; about $6.05M supports the modeled $240,000 annual owner target after reserves.
Owner salary and owner distributions are different tax and accounting concepts; the calculator shows one total owner cash pool and does not claim it is all distributable profit.
Project margin, technical labor utilization, milestone collections, and recurring service mix matter as much as headline contract value.
How do low, base, and high scenarios change owner income?
The model moves from $39,000 of annual owner income in the low case to $725,760 in the base case and $1,263,780 in the high case, all after the corresponding tax and reinvestment reserves. These are not salary promises. They are arithmetic outcomes from different project volume, margin, staffing, overhead, marketing, debt, and reserve assumptions. The high case adds labor and overhead rather than pretending extra revenue is free.
Owner income scenarios
Low, base, and high cases show how accepted deployments, project margin, staffing and reserves change owner cash.
Warehouse Robotics low, base, and high owner-income planning cases
Scenario
Low CaseDownside
Base CasePlanning
High CaseUpside
Launch modelRevenue architecture
Six $700,000 deployments plus $1.2M recurring revenue; $5.4M annual revenue.
Eight $800,000 deployments plus $1.4M recurring revenue; $7.8M annual revenue.
Eleven $900,000 deployments plus $1.5M recurring revenue; $11.4M annual revenue.
Owner income rangeAfter modeled tax + reinvestment reserves
$39,000
$725,760
$1,263,780
Best fitPlanning use
Stress-test a thin backlog, price pressure, and minimum fixed staffing before committing to owner draws.
Use for a stable owner-led integrator with eight accepted projects, disciplined scope and normal staffing.
Use only when backlog, project management capacity and working capital can support eleven larger deployments without quality erosion.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move Warehouse Robotics owner income most?
The six drivers below expand the same levers used in the compact cards. They are ranked by how quickly they can change cash available to the owner in an integrator model. The important discipline is to measure each driver at the project level first, then roll it into a monthly owner-income forecast; annual averages can hide one bad deployment, a quarter of idle engineers, or a large receivable.
1. Accepted deployment volume
Build revenue from accepted systems, not pipeline
The base model requires eight accepted deployments a year. That is roughly two per quarter, with $6.4 million of project revenue plus $1.4 million of recurring and follow-on work. The broader robotics market supports the idea that customers are still investing: A3 reported 17,995 North American robot orders worth $1.166 billion in the first half of 2026. But a new integrator should not convert market growth into an automatic sales forecast.
If one $800,000 base project slips beyond year-end and costs do not move, revenue falls to $7.0 million. At 44% pre-payroll margin, that can remove up to $352,000 of gross profit before avoided costs. Forecast signed backlog, delivery, commissioning, and acceptance separately.
Track acceptance-weighted backlog
Count revenue when the operational and contractual milestones are credible, not when a prospect asks for a proposal.
Signed contract value by month
Robots and sites per deployment
Expected commissioning date
Acceptance risk and open punch-list items
Backlog gross profit, not only backlog revenue
2. Contract value and scope discipline
Price the whole solution, including risk
The $800,000 base contract value is a planning assumption for a mid-market deployment that combines purchased robots with controls, WMS or WES integration, engineering, site work, commissioning, training, and acceptance support. It is intentionally higher than a single robot's hardware value because the customer is buying a functioning system, not a loose machine. The quote should explicitly define robot quantity, maps, interfaces, throughput tests, safety work, travel, customer prerequisites, and change-order triggers.
A 5% pricing miss on an $800,000 contract is $40,000. Repeated across eight projects, that is $320,000 of annual revenue leakage. If the work is still performed, the loss hits contribution and owner cash. Scope clarity and change-order discipline matter more than headline price.
Track realized value per accepted project
Compare the signed price with the final price after approved changes and credits, then compare both with the hours and hardware actually consumed.
Quoted versus final contract value
Change-order dollars captured
Unbilled extra engineering hours
Travel days versus quote
Customer-caused delay cost recovered
3. Project gross margin
Separate hardware margin from labor efficiency
The calculator's 44% gross margin is before all employee payroll. That makes the input useful for testing robot procurement, controls, batteries, freight, materials, non-payroll subcontracting, and other direct project costs without double counting engineers and technicians. It should not be compared directly with a published gross margin that includes direct deployment labor. As an adjacent reference, Symbotic reported an 18.8% consolidated gross margin in fiscal 2025 after its own cost-of-revenue classification.
Each one-point margin movement equals $78,000 of annual gross profit at $7.8 million of sales. After the modeled reserves, about $49,000 of that incremental profit remains as owner income if nothing else changes.
Track margin at quote, order, and acceptance
A monthly blended margin can hide one project that is destroying cash. Review the same job at three checkpoints.
Quoted gross margin
Committed hardware cost
Freight and damage variance
Approved versus absorbed changes
Final margin after acceptance
4. Technical labor utilization
Keep scarce technical payroll close to billable work
A 10% annual overrun on the base payroll budget costs $144,000 before reserves. The answer is not 100% billability because pre-sales, safety, training, documentation, and testing are real work. Track productive utilization by role and gross profit per payroll dollar.
Track hours by economic purpose
Separate project delivery, support, sales engineering, internal development, warranty, training, and idle time so hiring decisions are based on capacity evidence.
Billable deployment hours
Pre-sales engineering hours
Warranty and rework hours
Overtime by project
Gross profit per payroll dollar
5. Milestone billing and working capital
Make customer cash arrive before the owner finances the project
The compact card uses a 30% deposit target as a planning policy, not an industry standard. On an $800,000 deployment, that is $240,000 before the heaviest hardware and field costs. The exact structure should reflect vendor deposits, lead times, acceptance risk, and customer credit. If a customer will not pay upfront, intermediate design, factory-acceptance, delivery, commissioning, and site-acceptance milestones can reduce the cash gap.
Working capital directly changes safe distributions. The base calculator can show $96,000 of monthly profit before reserves while bank cash falls because a customer milestone is late and robot invoices are due. Before a large draw, reconcile receivables, unbilled work, supplier commitments, warranty exposure, and near-term payroll.
Track cash conversion by deployment
The owner should know which projects are cash-positive, cash-neutral, or temporarily financed by the company.
Deposit percentage
Days from invoice to cash
Unbilled completed work
Supplier deposits due before milestones
Cash committed through acceptance
6. Recurring software and service mix
Use recurring work to smooth installation lumpiness
The base case assigns $1.4 million, about 18% of annual revenue, to software, monitoring, preventive maintenance, spares, training, upgrades, and support. That is a planning mix, not a published benchmark. Its purpose is to reduce dependence on the exact timing of eight large deployments and to keep customer relationships active between major capital projects. Recurring work only improves owner income if response commitments, spare-parts inventory, travel, and support staffing are priced into the contract.
If recurring revenue grows from 18% to 25% of the same $7.8 million base without lowering total margin, another $546,000 of sales becomes less tied to new-site acceptance timing. It is not automatically profit; compare support gross profit, renewal, service hours, and expansion sales with the cash needed to support the installed base.
Track installed-base economics
A growing installed base can become a cash stabilizer or an underpriced service obligation. Measure it separately from new deployments.
Recurring revenue as a percent of sales
Renewal and expansion rate
Support gross profit
Field visits per customer
Spare-parts and warranty consumption
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.