Where Does Owner Income Come From in a Sports Bar?
Sports Bar Bundle
A U.S. owner-operated Sports Bar can realistically plan for about $22,500 to $262,080 a year in owner income after modeled tax and reinvestment reserves, with a defensible base case around $127,680 a year on $1.92 million of annual sales. In this planning model, a 72% gross margin after food, beverage, payment-processing, and other non-labor direct costs leaves $115,200 of monthly gross profit; $52,000 of hired labor, $38,000 of fixed overhead, $4,000 of marketing, and $6,000 of debt service reduce that to $15,200 before reserves, then a 20% tax reserve and 10% reinvestment reserve leave $10,640 per month for the owner. That figure combines compensation for an owner who works as the general manager with the residual return on ownership; it does not include a second owner salary, guaranteed distributions, or a promise about the owner's final personal tax bill.
Owner income$128KNet margin7%Revenue for target pay$1.86MBusiness difficultyHard
What does a realistic Sports Bar owner-income model look like?
The base case is intentionally more conservative than a headline “bar profit” estimate. The National Restaurant Association reported that full-service restaurants had median income before taxes of just 2.8% of sales in 2024. That benchmark covers a broad mix of full-service concepts and does not isolate sports bars, so the model below treats its 72% blended gross margin as a planning assumption supported by a beverage-heavy mix, then keeps labor, occupancy, marketing, debt, and reserves explicit rather than hiding them in one margin. See the Association's 2024 restaurant profitability benchmark.
Owner income calculator
Estimate owner take-home from sports-bar sales, blended margin, staffing, overhead, debt, and reserve choices.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Which six levers move Sports Bar owner income the most?
Sports-bar economics are unusually sensitive to a handful of controllable ratios. The National Restaurant Association found full-service labor at a 36.5% median share of sales in 2024; a sports bar can still lose money with a strong beverage mix if staffing, purchasing, pours, comps, waste, and kitchen execution drift together. The six cards below use that industry labor anchor plus explicit planning assumptions for direct costs and owner coverage, not a claim that every sports bar will hit the same mix. See the Association's labor-cost data.
1
Guest volume and seat turns
133 checks/day
The base model needs about 4,000 monthly checks at a $40 average check; empty seats on ordinary nights are more damaging than a weak playoff peak is helpful.
2
Blended check and beverage mix
$40 base check
Beer, cocktails, appetizers, and shareable food can lift spend without adding seats; menu mix matters as much as headline prices.
3
Direct-cost control
72% gross margin
The base case assumes 28% non-labor direct costs. A two-point margin leak costs $3,200 per month at $160,000 sales before reserves.
4
Labor and owner coverage
$52K/month
Base hired payroll excludes owner pay because the owner covers the GM role; hiring that role without more sales reduces owner cash almost dollar for dollar.
5
Occupancy and sports overhead
$38K/month
Rent is only one fixed cost. Commercial sports programming, utilities, insurance, repairs, security, software, and equipment maintenance all sit underneath the bar's break-even point.
6
Debt and reserve discipline
30% reserve
The base plan holds back 20% for taxes and 10% for reinvestment after $6,000 of monthly debt service, keeping reported profit from becoming an automatic draw.
Want to test the game-day assumptions in a full forecast?
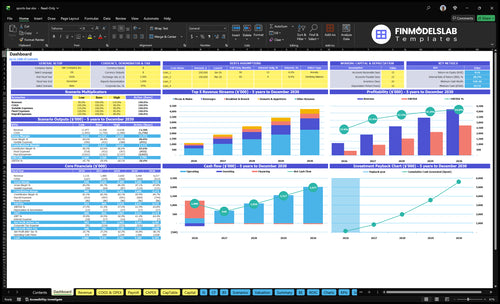
The Sports Bar Financial Model Template in Excel includes a dashboard, revenue drivers, cost inputs, payroll, scenarios, and cash-flow outputs that can help you test traffic, average check, beverage mix, labor, debt, and owner-income assumptions together. The preview is useful for checking whether strong game-day sales actually produce enough cash after slower periods, staffing, fixed overhead, and reinvestment.
How many guests does a Sports Bar need to support owner pay?
In this base model, roughly 4,000 checks per month at a $40 blended check produce $160,000 of monthly sales, or about 133 checks per calendar day. That is not a national traffic benchmark; it is the operating volume implied by the financial model. The price side is grounded in current menu data: Toast reported a $6.45 median beer price on U.S. restaurant and bar menus in July 2025, so a $40 check typically requires more than a single drink and depends on food attachment, second rounds, group ordering, or higher-value beverages. See Toast's U.S. bar beer pricing data.
Base traffic math
$160,000 monthly revenue
$40 planning average check
4,000 checks per month
About 133 checks per day
What this estimate hides
Friday and Saturday concentration
Major-game surges and ordinary-night softness
Table dwell time during long broadcasts
Different checks for drink-only and meal guests
What margin must a Sports Bar protect before the owner can draw cash?
A sports bar needs to protect both gross margin and labor at the same time. The 2024 full-service restaurant benchmark put salaries, wages, and benefits at a 36.5% median share of sales, while profitable full-service respondents were lower at 34.2%. In this base model, hired labor is $52,000, or 32.5% of sales, specifically because the owner is doing the GM job and owner compensation is not included in payroll. If you compare that model to an industry P&L, add an economic value for the owner's labor before calling the remaining amount passive profit. The May 2025 BLS data showed food-service managers at a $74,880 annual mean wage nationally, which is a useful reference point for that reclassification. See BLS May 2025 wage data.
Owner-operated base
$115,200 monthly gross profit
$100,000 operating costs before reserves
$15,200 profit before reserves
$10,640 monthly owner income after reserves
Salary versus distribution
Owner-GM labor is real economic work
A wage-equivalent amount is not extra cash
Residual profit is the entrepreneurial return
Entity and tax treatment can change classification
Key Takeaways
The base case produces about $127,680 of annual owner income after modeled reserves, but that includes the value of an owner-GM's work.
At $160,000 monthly sales, every one percentage point of gross margin is worth about $1,600 per month before reserves.
Full-service restaurant labor and occupancy benchmarks show why a busy room can still generate weak owner cash if staffing or rent drifts.
Debt service, tax reserves, equipment replacement, and working capital are paid before a distribution is truly safe.
Can a Sports Bar owner step out of daily operations and keep the same income?
Usually not at the same sales level. The base case assumes the owner covers the GM function, and BLS reported a May 2025 mean annual wage of $74,880 for food-service managers. Replacing the owner with a hired manager can therefore consume a large share of the $127,680 modeled owner income unless the bar grows volume, price, or margin. It is also a demanding role: the BLS Occupational Outlook Handbook notes that food-service managers commonly work evenings, weekends, and holidays, which lines up directly with a sports bar's peak demand. See the BLS food-service manager profile.
Owner stays operational
No separate GM line in base labor
Owner income includes labor value
More control over scheduling and comps
Lower passive-owner interpretation
Owner steps back
Add a market-based manager cost
Increase management and payroll burden
Require more revenue or better margins
Judge distributions after replacement labor
How much fixed overhead can a Sports Bar carry?
The base model carries $38,000 a month of fixed overhead before marketing and debt service. That is intentionally broader than rent: it includes occupancy, utilities, insurance, commercial sports programming, repairs, POS and software, permits, cleaning, security base costs, and administration. National Restaurant Association data put full-service occupancy costs at a 5.7% median share of sales in 2024, with urban full-service restaurants at 6.0%. At $160,000 monthly revenue, a 5.7% occupancy ratio is about $9,120 a month, leaving the rest of the $38,000 overhead bucket for the many non-rent costs a sports bar must absorb. See the Association's occupancy-cost benchmark.
Sports programming is a genuine business input, not a consumer subscription copied onto bar TVs. DIRECTV for Business states that its 2026 NFL Sunday Ticket offering is available to commercial locations including bars and restaurants and that pricing for public-viewing establishments is based on fire-code occupancy. That makes capacity a two-sided financial driver: more legal occupancy can create more sales opportunity, but it can also raise sports-programming costs and game-day staffing requirements. See commercial NFL programming guidance.
What do low, base, and high owner-income cases look like?
The scenarios below use the same calculator formulas and change costs as volume changes. The low case does not pretend fixed costs disappear when sales soften, and the high case adds management, labor, overhead, marketing, and debt rather than letting revenue rise against a frozen expense base. Financing matters because SBA 7(a) interest rates are negotiated with lenders but capped relative to a base rate, so actual debt service can vary materially with loan size and terms; see the SBA 7(a) loan terms. Tax reserves are also planning amounts, not tax rates: the IRS notes that owners such as sole proprietors, partners, and S corporation shareholders may need estimated tax payments when they expect to owe enough tax; see IRS estimated-tax guidance.
Owner income scenarios
Low, base, and high cases show how guest volume, check size, gross margin, staffing, fixed overhead, debt, and reserves change owner take-home.
Sports Bar low, base, and high owner-income planning cases.
Scenario factor
Low CaseDownside
Base CasePlanning
High CaseStretch
Launch modelDemand posture
Slower neighborhood and game-night demand; owner stays hands-on; no extra manager.
Stabilized owner-operated bar with regular game-day traffic and controlled beverage mix.
High-volume destination operation with added management, staff, security, and marketing.
Typical setupVolume and check
$120,000 monthly revenue; 70% gross margin; about 111 daily checks at a $36 planning check.
$160,000 monthly revenue; 72% gross margin; about 133 daily checks at a $40 planning check.
$240,000 monthly revenue; 74% gross margin; about 182 daily checks at a $44 planning check.
Cost driversMonthly cash load
$40,000 labor
$33,000 fixed overhead
$2,500 marketing
$6,000 debt
25% combined reserves
$52,000 labor
$38,000 fixed overhead
$4,000 marketing
$6,000 debt
30% combined reserves
$82,000 labor
$48,000 fixed overhead
$7,000 marketing
$7,000 debt
35% combined reserves
Owner income rangeAfter modeled reserves
$22,500After modeled reserves
$127,680After modeled reserves
$262,080After modeled reserves
Best fitPlanning use
Stress-test a soft opening, weak non-game nights, or a smaller trade area.
Budget an established owner-operated neighborhood sports bar with disciplined prime cost.
Test a destination sports bar with stronger pricing, occupancy, and added management capacity.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
What are the six detailed Sports Bar income drivers?
The strongest owner-income levers are the same six shown earlier, but each has a different operating mechanism. Track them separately so a sales increase cannot conceal a weaker gross margin, overstaffing, rent pressure, or a distribution that drains cash needed for the next slow month.
1. Guest volume and seat turns
Build the week around checks, not just headline game nights
Revenue capacity starts with how many paying parties the room can process. The base case needs about 4,000 checks a month. At a $40 blended check, 100 fewer checks in a month means roughly $4,000 less revenue; at a 72% gross margin, that removes about $2,880 of gross profit before labor and fixed costs change. A sports bar is especially exposed to long dwell times because customers may hold a table through an entire game. That makes revenue per occupied seat-hour a better operational KPI than raw foot traffic. Commercial sports packages can support the draw, and DIRECTV for Business says 2026 NFL Sunday Ticket pricing for public-viewing establishments is tied to fire-code occupancy, reinforcing that capacity has both revenue and cost consequences.
Track demand by daypart and event
Separate routine trade from event-driven traffic so a strong Sunday does not hide a weak Tuesday.
Checks per open hour
Revenue per available seat-hour
Game-day versus non-game-day sales
Table dwell time
2. Blended check and beverage mix
Increase spend without forcing another seat turn
The base model uses a $40 blended check, while the low and high cases use $36 and $44. Those are planning assumptions rather than national sports-bar averages. Toast's July 2025 menu data showed a $6.45 median beer price across U.S. restaurants and bars. The implication is simple: a $40 check usually needs multiple items, not just one beer. If the base bar keeps 4,000 monthly checks and raises the blended check by $2 without damaging traffic, revenue rises by $8,000. At a 72% gross margin, that is $5,760 of added gross profit before any incremental labor or marketing. Menu engineering should therefore focus on attachment rate, second-round conversion, appetizer and wing bundles, premium beverage mix, and responsible upselling rather than indiscriminate price increases.
Measure what each check is made of
A healthy average check should come from repeatable mix, not occasional high tabs.
Average check by daypart
Beverage revenue share
Food attachment per drinking party
Second-round conversion
3. Direct-cost control
Protect the blended gross margin item by item
The model's 72% base gross margin means 28% of sales goes to non-labor direct costs. That is a sports-bar planning blend, not the National Restaurant Association's restaurant benchmark. The Association reported that higher-volume full-service restaurants above $2 million had food and non-alcohol beverage costs at a 31.0% median in 2024, compared with 33.7% for respondents below $2 million. A sports bar with meaningful beverage sales can have a lower blended cost percentage than food-only economics suggest, but poor pours, comps, theft, draft loss, spoilage, card fees, and heavy discounting can erase that advantage. At $160,000 monthly sales, every one-point drop in gross margin costs $1,600 before reserves; a fall from 72% to 68% removes $6,400 a month, more than half the base owner's $10,640 take-home.
Reconcile theoretical and actual cost
Gross margin should be explained by inventory and recipe data, not accepted as a POS percentage.
Food cost by category
Beer, wine, and liquor cost
Waste, comps, and spills
Gross-margin points lost per month
4. Labor and owner coverage
Price the owner's shifts even when cash payroll does not
The National Restaurant Association's 2024 full-service median for salaries, wages, and benefits was 36.5% of sales, and profitable respondents were at 34.2%. The base model shows only 32.5% hired labor because the owner covers the GM role; that lower payroll ratio is not free efficiency. May 2025 BLS wage data reported a $74,880 annual mean wage for food-service managers, while bartenders averaged $40,790 and restaurant cooks $38,730. Those national wages are not a local staffing budget, but they show why adding one manager plus peak kitchen and bar coverage can consume owner cash quickly. If a manager costs the business about $6,000 to $7,000 a month in wage and payroll burden, the base owner income can fall by more than half unless sales or margins improve.
Separate owner labor from ownership return
Do not call the whole owner draw passive profit when the owner is closing the bar, scheduling staff, and managing vendors.
Labor percentage before owner pay
Manager-equivalent cost
Sales per labor hour
Overtime and game-day security hours
5. Occupancy and sports overhead
Keep the fixed-cost base survivable in ordinary weeks
Full-service occupancy costs were a 5.7% median share of sales in 2024, according to the National Restaurant Association, and urban operators were at 6.0%. The base model's $160,000 monthly revenue would put 5.7% occupancy near $9,120, but the $38,000 fixed-overhead input is much broader: it also has to carry utilities, insurance, commercial television, repairs, POS and software, permits, cleaning, security base costs, and administration. Alcohol adds compliance work as well. TTB retailer guidance requires retail alcohol dealers to register before operating and notes that state and local alcohol rules also apply. The key owner-income question is not whether rent is affordable on Super Bowl Sunday; it is whether the full fixed-cost stack remains affordable during a month with weak local-team performance or fewer marquee events.
Track fixed costs against normal-month sales
Budget on a stabilized ordinary month and treat championship traffic as upside, not as the amount required to pay rent.
Occupancy percentage
Utilities per open hour
Commercial sports-programming cost
Repair and equipment reserve
6. Debt and reserve discipline
Decide what is distributable only after financing and reserves
The base calculator pays $6,000 of monthly debt service before it calculates owner income, then withholds 20% of positive profit for taxes and 10% for reinvestment. That leaves $10,640 a month from $15,200 of profit before reserves. The order matters: accounting profit can exist while cash is unavailable because principal payments, tax deposits, equipment replacement, working capital, or required lender covenants consume it. SBA notes that 7(a) loan rates are negotiated but subject to maximum spreads over a base rate, so refinancing or a different loan size can change monthly debt service materially. The IRS estimated-tax guidance also notes that many owners may need estimated tax payments during the year. A draw should therefore be the last line of the cash bridge, not an amount chosen first and forced into the budget.
Use a distribution gate every month
Before moving cash to the owner, verify that taxes, debt, payroll timing, vendors, and the next repair cycle are funded.
Debt-service coverage
Tax reserve balance
Reinvestment reserve balance
Weeks of operating cash after the draw
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Choosing a selection results in a full page refresh.