What Is a Realistic Pay Range for Water Refill Station Owners?
A single, owner-operated Water Refill Station in a mid-cost U.S. market can reasonably plan around $79,200 of annual owner income in a stabilized base case, with a modeled range of about $27,816 to $129,756 across conservative and stronger-volume scenarios. The base case assumes $33,000 of monthly revenue ($396,000 annually), an 80% gross margin before payroll, $6,500 of non-owner labor, $7,000 of fixed overhead, $1,500 of marketing, and $1,400 of monthly debt service. The $79,200 figure is cash remaining after a 24% tax reserve and 10% reinvestment reserve; it is not a guaranteed salary, does not include the owner's personal tax outcome, and does not assume extra distributions from cash needed for filters, membranes, repairs, working capital, or expansion.
Owner income$79KNet margin20%Revenue for target pay$405KBusiness difficultyModerate
What does a Water Refill Station need to sell to pay the owner $84,000 a year?
In this planning model, the station needs about $33,758 of monthly revenue, or $405,096 annually, to support a $7,000 monthly owner-income target after the modeled reserves. That target is slightly above the base case's $396,000 annual revenue, which is why the base output lands at $79,200 rather than $84,000. A 2025 City of Santa Monica rate-study presentation showed water fill stations and stores at roughly $0.40 to $1.00 per gallon; that is a California market reference, not a national tariff. The base case uses an approximately $0.55 blended refill price and assumes a small share of revenue from containers and accessories. With the same base cost structure, operating break-even is about $20,500 per month, or $246,000 annually, before owner pay and reserves.
At that mix, roughly 90% of base revenue comes from water: about $29,700 per month. At $0.55 per gallon, that is about 54,000 gallons per month, or 1,800 gallons per day across a 30-day month. That sounds large until you compare it with commercial equipment capacity. Watts lists a 5,000-gallon-per-day light-commercial RO system, so the base sales volume is within equipment capability for a properly designed station. Capacity is not demand, so the site still needs repeat households and reliable uptime.
Owner income calculator
Estimate owner take-home from refill revenue, margin, operating costs, reserves, and a target pay level.
!
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
1
Daily gallons sold
1,800 gal/day base
Small changes in repeat refill volume flow directly through a largely fixed site cost base, so utilization is the strongest owner-income lever.
2
Price and product mix
$0.55/gal base
A few cents per gallon matter at tens of thousands of gallons per month, while containers and accessories can lift revenue per visit.
3
Purification yield
80% gross margin
Feedwater, reject water, media, sanitation, host or payment costs, and filter life determine how much revenue survives before payroll.
4
Staffing and owner role
$6.5K/month labor
The base case is owner-managed; replacing owner coverage with another full-time manager or attendant reduces residual owner cash unless volume rises.
5
Site economics and uptime
$7K/month overhead
Rent, utilities, testing, maintenance, insurance, and downtime are mostly paid whether the station sells 900 or 2,000 gallons in a day.
6
Marketing and repeat visits
$1.5K/month base
Because the product is low-ticket, paid acquisition works only when households return often enough for lifetime gross profit to exceed acquisition cost.
Want to test gallons, pricing, staffing, and cash flow in a full forecast?
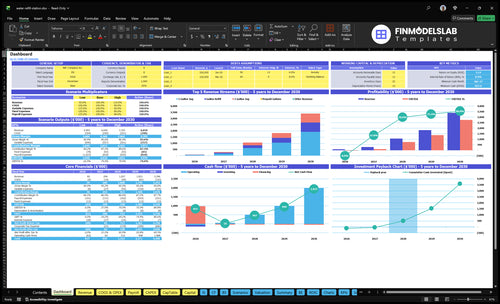
The Water Refill Station Financial Projections Template in Excel includes a dashboard and operating assumptions that can help you pressure-test refill volume, pricing, cost structure, cash runway, and financing. The preview is useful for seeing how changes in daily gallons or fixed costs roll through a multi-year forecast rather than treating owner income as a single percentage of sales.
What gross margin can a water refill station realistically keep?
A practical underwriting range is roughly 74% to 83% gross margin before payroll for this owner-income model, with 80% used in the base case. That is a reconstructed planning range, not a published national industry margin. Raw municipal water is inexpensive relative to the refill price, but treatment efficiency and transaction costs still matter. Santa Monica's 2025 comparison put municipal Tier 1 water near $0.008 per gallon and refill stores at $0.40 to $1.00 per gallon. The gap is not pure profit: the station still pays for rejected water, sewer charges, filters, membranes, ultraviolet or ozone equipment, electricity, card processing or host share, sanitation, testing, and maintenance.
Reverse osmosis is the first place to challenge a rosy margin. The EPA notes that a typical point-of-use system can reject five gallons or more for each gallon treated, while WaterSense-labeled units must send no more than 2.3 gallons to drain for each gallon produced. Commercial systems differ, but the lesson is the same: recovery changes the effective water-and-sewer cost per gallon. The U.S. Energy Information Administration reported a 2025 average commercial electricity price of 13.41 cents per kWh; pumps, UV treatment, chilling, lighting, and HVAC still erode margin.
What belongs above gross profit
Feedwater and wastewater attributable to purification.
Filters, membranes, sanitizer, mineral cartridges, and other direct consumables.
Payment or site-host costs that rise with sales.
Container cost when jugs are sold as merchandise.
What stays below gross profit
All employee payroll and payroll burden.
Rent, insurance, software, accounting, and routine administration.
Marketing and customer-acquisition spending.
Debt service, tax reserves, and reinvestment reserves.
Key Takeaways
Base owner income is $79,200 after modeled reserves, not 20% of sales available automatically.
The base revenue engine is about 1,800 refill gallons per day at a roughly $0.55 blended gallon price plus accessory sales.
Owner labor is not counted in payroll here; the owner-income output compensates both the owner's work and ownership risk.
Debt, maintenance, quality testing, and replacement reserves must be funded before distributions are considered safe.
Can a Water Refill Station run without the owner working every day?
Yes, but a single-site station usually gives up meaningful owner income when it replaces owner coverage with paid management before sales are large enough to absorb it. The base case includes $6,500 per month of non-owner labor and assumes the owner handles management, purchasing, quality oversight, bookkeeping review, vendor coordination, and some customer or opening coverage. For wage context, the U.S. Bureau of Labor Statistics reported a $16.62 median hourly wage for retail salespersons in May 2024. A station that needs two staffed shifts, weekend coverage, or a separate manager can quickly spend several thousand dollars more per month than the owner-operated base.
This distinction matters because owner salary and owner distributions are not interchangeable. In this calculator, owner pay is not included in labor cost; owner take-home is the residual cash after operating costs and the modeled reserves. If the business is taxed as an S corporation and the owner works in it, the tax treatment can require payroll compensation before distributions. The IRS states that S corporations must pay shareholder-employees reasonable compensation for services before non-wage distributions. Do not double-count that compensation in both payroll and distributions.
Owner-operated base
Owner manages the site and vendor relationships.
$6,500 monthly non-owner labor.
Residual owner cash: $6,600 per month after modeled reserves.
Best when the owner can cover management without sacrificing sales or maintenance discipline.
Manager-run adjustment
Add the market cost of the manager plus payroll burden.
Do not call replaced owner labor passive profit.
Raise volume, price, or gross margin before expecting the same distribution.
Track revenue per paid labor hour, not payroll dollars alone.
When is cash actually safe to distribute to the owner?
Cash is safe to distribute only after the station has paid direct treatment costs, non-owner payroll, rent and other fixed overhead, marketing, debt service, current tax obligations, and a credible reserve for filter changes, membranes, pumps, sanitation, testing, and working capital. Revenue is the top line; gross profit is after direct gallon costs; operating profit or EBITDA is not the same as cash because debt principal and replacement spending can still be due. Owner salary pays for work performed, while a draw or distribution comes from residual cash. Accounting profit can be positive while loan principal, replacement equipment, or delayed bills consume cash. In the base case, $10,000 of monthly profit before reserves becomes $6,600 of owner income after setting aside $2,400 for tax and $1,000 for reinvestment.
Debt is especially important because principal payments reduce cash even though they are not an operating expense on an income statement. The SBA notes that 7(a) loan interest rates are negotiated but subject to maximums, and most 7(a) terms are 10 years or less unless real estate or longer-lived equipment supports a longer term. The $1,400 monthly debt-service input is a planning assumption; replace it with the actual rate, term, and down payment.
Taxes also depend on entity type and the owner's wider return. The IRS explains that the way an owner pays themself depends on the business structure, including whether the owner is a corporate officer, partner, or sole proprietor; its paying-yourself guidance is a useful starting point. The 24% tax reserve is a cash-management placeholder, not a tax rate or proof that every remaining dollar can be drawn.
Cash waterfall before a draw
Collect revenue and remove sales-tax pass-throughs where applicable.
Pay direct gallon costs and all payroll.
Fund rent, utilities, testing, maintenance, marketing, and debt.
Set aside tax, repairs, replacement, and working-capital reserves.
What this estimate hides
State rules vary; California, for example, requires licenses or permits for water-vending machines and retail water facilities.
California law also requires routine sanitation, records, and product-water testing.
A failed disinfection system can force shutdown rather than sales.
These compliance costs are modest until poor maintenance creates downtime or emergency repairs.
As one concrete state example, California law requires water-vending machines and retail water facilities to operate under a license or local permit, and it requires water-vending machines to be cleaned, serviced, and sanitized at least every 31 days; the same code also sets testing requirements. Review the California Health and Safety Code provisions for bottled and vended water as an illustration of why compliance belongs in the cash plan. Your own state's requirements may be different.
How do low, base, and high cases change Water Refill Station owner income?
The model produces about $27,816 of annual owner income in the low case, $79,200 in the base case, and $129,756 in the high case, all after each scenario's modeled tax and reinvestment reserves. The high case adds labor, marketing, and fixed overhead rather than pretending extra sales are free. The low case also keeps minimum site costs and debt in place, so lower sales do not create an unrealistically light expense structure.
Owner income scenarios
Low, base, and high cases connect daily gallon volume with price, margin, staffing, overhead, debt, and reserves.
Water Refill Station low, base, and high owner-income planning cases.
Scenario factor
Low CaseConservative
Base CasePlanning case
High CaseUpside
Launch model
Slower traffic; owner covers more shifts; low marketing spend.
Stabilized single site; owner-managed; repeat household demand.
Strong site utilization; more paid coverage; larger local marketing budget.
Owner income rangeAfter modeled tax + reinvestment reserves
$27,816
Annual owner income after modeled reserves.
$79,200
Annual owner income after modeled reserves.
$129,756
Annual owner income after modeled reserves.
Best fit
Stress-test a slow ramp or weaker location before cutting fixed costs unrealistically.
Use for an owner-operated, single-site station in a mid-cost market.
Test stronger repeat demand after staffing and marketing scale with volume.
!
Planning note: These scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Which six drivers move Water Refill Station owner income most?
Owner income is most sensitive to daily refill volume, price and product mix, purification yield, staffing, site economics and uptime, and the cost of acquiring repeat customers. These drivers interact: a higher-volume site can support more labor, but weak water recovery or frequent downtime can erase the benefit; a higher gallon price can improve profit, but only if customers keep returning. Track the drivers in operational units, not only in monthly dollars.
1. Daily gallons sold and repeat refill frequency
Turn installed capacity into paid utilization
The base case sells about 1,800 refill gallons per day, while the high case is closer to 2,400 gallons per day before accessory revenue. That is still below the 5,000-gallon-per-day rated capacity of the referenced Watts light-commercial RO system. At an 80% gross margin, an extra $1,000 of monthly revenue creates about $800 of gross profit before added labor, marketing, and overhead. Off-peak gallon growth can therefore be very valuable.
For owner income, watch gallons by daypart and repeat household frequency. A station that sells 1,800 gallons only on weekends may need more storage and queues, while the same monthly volume spread through the week may need less labor and less peak capacity.
Track paid gallons, not foot traffic
The financial KPI is gallons actually dispensed and paid for.
Gallons per day and per open hour.
Visits per repeat customer per month.
Revenue per dispenser and per square foot.
Peak-hour queues and abandoned fills.
2. Price per gallon and accessory mix
Price in cents, model in thousands of gallons
The base case uses a roughly $0.55 blended refill price, inside the $0.40 to $1.00 range shown in Santa Monica's 2025 public comparison. At 54,000 gallons per month, a five-cent price change moves monthly water revenue by about $2,700 before any demand response. That is large relative to the base $6,600 monthly owner-income output. Test price in cents per gallon, not only as an annual growth rate.
Accessory sales can raise the first-visit ticket without changing purification throughput. Watermill Express's official store lists 3-gallon containers at $10 and 5-gallon containers at $15, showing why bottles and pumps can add meaningful dollars to a low-ticket refill visit. Subtract merchandise cost when calculating margin.
Separate water price from visit value
Track the economics of the core gallon and the basket around it.
Realized price per gallon after promotions.
Accessory revenue per new customer.
Price-change retention after 30 and 90 days.
Gross profit per visit, not only average ticket.
3. Purification recovery, consumables, and direct cost per gallon
Protect the 80% gross-margin assumption
The model's 80% base gross margin means each $1 of sales leaves $0.80 before payroll and fixed overhead. That is achievable only if direct cost is controlled. RO reject water is a hidden lever: the EPA says conventional point-of-use RO can waste five gallons or more for each treated gallon, while efficient WaterSense systems must stay at 2.3 gallons or less of reject water per gallon produced. Commercial recovery is system-specific, so use actual feed, product, and reject meters.
Here's the quick math: a four-percentage-point drop in gross margin, from 80% to 76%, on $33,000 of monthly revenue removes $1,320 from monthly gross profit before reserves. After the same cost base, that could reduce owner income by hundreds of dollars per month. Include filter life, sanitizer, card fees, and host commissions in direct cost.
Measure cost per sellable gallon
Use meter readings and replacement logs to catch margin drift early.
Feed gallons divided by sellable gallons.
Filter and membrane cost per 1,000 gallons.
Reject-water and sewer cost per gallon sold.
Payment and host fees as a percent of sales.
4. Staffing level and the owner's operating role
Do not make owner labor look free
The base case carries $6,500 of monthly non-owner labor and leaves the owner as working manager. BLS reported a May 2024 median of $16.62 per hour for retail salespersons. A 40-hour position at that wage is roughly $2,880 per month before payroll burden, benefits, overtime, and scheduling gaps.
If the owner wants passive ownership, add the replacement manager's full loaded cost and rerun the model. Do not call the distribution passive while the owner still performs operating work.
Track labor against gallons and gross profit
Hours should flex with demand without compromising sanitation or service.
Paid labor hours per 1,000 gallons.
Gross profit per paid labor hour.
Owner hours by operating task.
Overtime, call-outs, and uncovered shifts.
5. Site economics, compliance, and uptime
Rent is paid even when the dispenser is down
The base fixed-overhead assumption is $7,000 per month, covering rent plus utilities, insurance, routine testing, maintenance, software, accounting, and administration. The correct number is local; poor access can make a cheap lease economically expensive. Uptime belongs in the same discussion because fixed costs continue while a failed pump, UV unit, card reader, or sanitation issue stops sales.
Compliance also has a direct cash effect. California's vended-water law requires water-vending machines to use approved sources, provide effective treatment and disinfection, and includes shutdown safeguards for treatment failures; it also requires service at least every 31 days and periodic product testing. See the California vended-water code as a state-specific example. Your state or local rules may differ, so budget them before signing the lease.
Track occupancy cost and lost sales together
A site is productive only when customers can find it, reach it, and use it.
Rent and occupancy cost as a percent of sales.
Uptime percentage by dispenser.
Hours of lost sales from maintenance failures.
Testing, sanitation, and inspection calendar completion.
6. Marketing efficiency and repeat-customer economics
Low-ticket sales demand repeat behavior
The base model spends $1,500 per month on marketing. That budget is useful only if new customers return. A refill business has a structural advantage when convenience is strong because the product is replenished repeatedly; Watermill Express describes a large drive-up network where customers bring their own containers and says its locations are open 24 hours a day, seven days a week. That is not an independent-store benchmark, but it shows how access supports repeat use.
For an independent station, calculate acquisition cost as monthly marketing divided by first-time paying households, then compare it with 90-day gross profit from those households. If $1,500 produces 100 new households, acquisition cost is $15 each; compare that with their 90-day gross profit before spending more.
Measure retention before increasing ad spend
The goal is recurring gross profit, not cheap clicks or one-time coupons.
Cost per first paid refill.
30-, 60-, and 90-day repeat rate.
Gross profit per acquired household.
Referral share and neighborhood penetration.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Water Refill Station Bundle
Choosing a selection results in a full page refresh.