

Revenue and Monthly Calc
Enter capacity, common occupancy, category shares, and annual rents. The monthly calculation schedule applies launch timing and consolidates rental revenue.


The Antique Mall Financial Model is an Excel financial planning template for a staff-operated, rent-only antique mall. It forecasts vendor-space rental income, operating costs, staffing, and EBITDA from 2026 through 2030, using editable occupancy, rental category, and pricing assumptions.
The illustrated case is a Michigan secondary-market location with 180 rentable places in approximately 26,000 gross square feet. Dealers own their merchandise; the mall earns rent rather than sales commissions, and the operating example does not assume outside financing.
The template connects operating assumptions to monthly calculations, financial reports, and scenario controls.
Enter capacity, common occupancy, category shares, and annual rents. The monthly calculation schedule applies launch timing and consolidates rental revenue.
Plan consumables, collection fees, marketing, premises expenses, and staff compensation separately, with effective dates and payment timing.
CAPEX, CapTable, and Debt separate asset purchases, owner contributions, and potential financing schedules. Dashboard debt controls support four facilities, but the illustrated operating case assumes no external borrowing.
Income Statement, Cash Flow, Balance Sheet, Summary, Sources & Uses, Returns, Scenarios, and Checks support broader financial review. Values quoted here are limited to the documented operating forecast through EBITDA.
Rental revenue equals available places multiplied by occupancy, category mix, and the corresponding monthly rental rates.
The model uses 180 rental places, not merchandise-sales or customer-traffic engines. Occupancy increases from 65% in 2026 to 92% in 2030, with each place allocated once.
The mix is 50% standard booths, 20% large booths, and 10% each deluxe cases, standard cases, and open shelves. Category rents change annually.
The Revenue Forecast organizes capacity, occupancy, booth and showcase mix, and the rental price per occupied place per month. Those assumptions flow into the monthly Calc sheet to generate projected vendor rent.
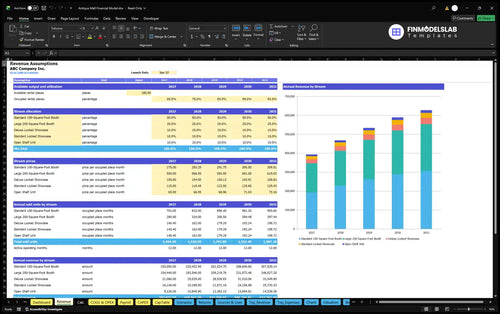
180 places × 65% occupancy × $280.50 weighted monthly rent × 12 months = $393,822 annual revenue.
The $280.50 weighted rent reflects five 2026 category rates and shares. Occupancy produces planning averages rather than physical fractional booths.
Rents are prepaid, with no sales commissions, required dealer labor, or card-cost markup. The January 2026 launch counts as a full operating month.
The model calculates percentage-based operating costs, recurring fixed expenses, and employee salaries as distinct expense groups.
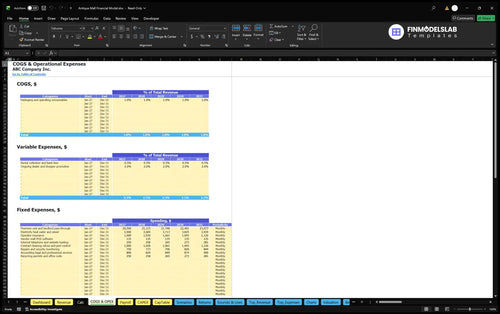
Consumables equal 1% of revenue, rental collection and bank fees 0.5%, and ongoing promotion 2%. These costs move with rent income.
Fixed costs cover rent, utilities, insurance, POS, connectivity, cleaning, security, repairs, and professional services. Premises rent starts at $20,500 monthly in 2026.
The COGS and Operating Expenses forecast separates direct consumables, variable collection and promotion costs, and fixed premises overhead. Its cost assumptions feed monthly expense schedules and operating margins without mixing in payroll salaries.
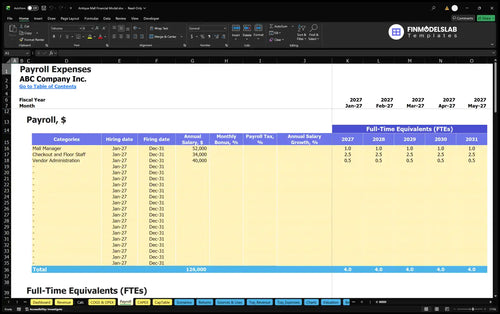
Payroll includes one $52,000 manager, 2.5 floor staff FTE at $34,000 each, and 0.5 administration FTE at $40,000: four FTE and $157,000 annually.
The Payroll Forecast tracks staffing by role, annual-average FTE assumptions, salary inputs, and their monthly expense effect. In the selected case, fixed base salaries are included only in Payroll and not repeated in direct or fixed operating costs.
Startup asset purchases, preopening cash payments, owner funding, and operating expenses serve different planning purposes.
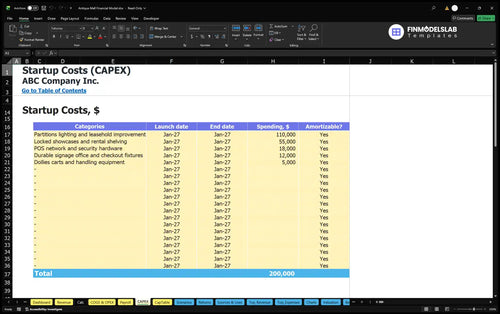
Opening assets include $110,000 for leasehold improvements, $55,000 for cases and shelves, $18,000 for POS and security, and $12,000 for fixtures, plus equipment.
Preopening payments cover deposits, legal setup, vendor recruitment, occupancy, and training. These are separate from annual EBITDA operating costs.
The Capital Expenditure Plan records asset purchase amounts and timing, with supporting depreciation schedules where applicable. It helps distinguish the initial fit-out of the mall from recurring operating costs in later forecast periods.
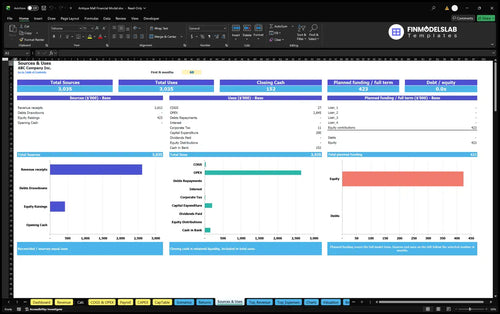
Initial owner funding is $422,575 for assets, preopening payments, launch supplies, and a three-month outflow reserve. This is not operating earnings or proof of future liquidity.
Sources and Uses of Funds summarizes modeled funding sources and how cash is allocated to operations, investment, financing, and retained balances. This report can be used to review owner contributions alongside planned startup outflows.
Receivable and payable days are zero; inventory days are 30. Vendor-owned antiques should not be treated as mall-owned inventory.
The supplied base operating example moves from an EBITDA loss in 2026 to positive operating EBITDA in 2029 and 2030.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $393,822 | $509,004 | -$115,182 |
| 2027 | $468,042 | $521,699 | -$53,657 |
| 2028 | $533,509 | $534,392 | -$883 |
| 2029 | $589,235 | $547,055 | $42,180 |
| 2030 | $627,365 | $559,424 | $67,941 |
Illustrative case, not historical performance or an industry benchmark. Figures are rounded to whole dollars; slight differences arise from rounding.
Revenue grows with occupancy and rent increases. Direct costs, variable expenses, fixed overhead, and payroll together grow more slowly in this illustrative case.
EBITDA is negative $883 in 2028 and positive $42,180 in 2029. EBITDA excludes interest, taxes, depreciation, and amortization, and is not cash flow or net profit.
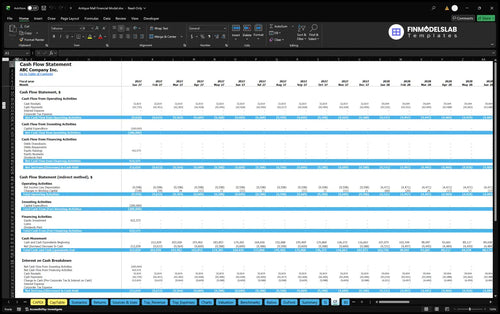
The Cash Flow Forecast is a separate liquidity report that considers operating, investing, and financing cash movements. Use it to investigate the cash effects of prepaid rents, startup assets, owner contributions, and any financing entered into the workbook.
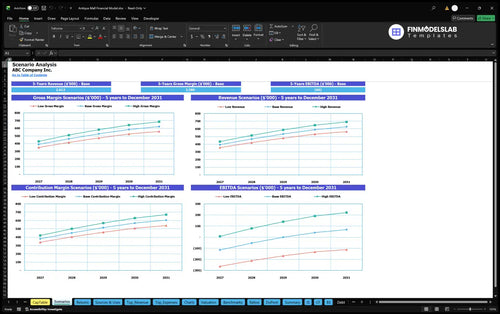
Dashboard Low, Base, and High multipliers let users compare rental revenue and direct, variable, fixed, and payroll expense cases.
Financial Scenario Analysis compares Low, Base, and High operating results, including revenue, margins, and EBITDA. The report helps assess the sensitivity of the five-year model to edited revenue, direct cost, operating expense, and payroll assumptions.
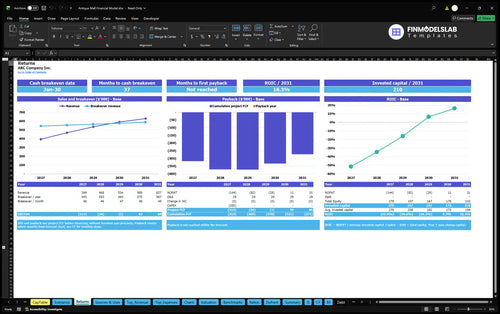
The workbook includes return analysis, but the documented EBITDA forecast does not establish an investment payback date or return percentage.
Sales break-even measures rent needed to cover operating costs; cash break-even reflects timing; payback measures recovery of invested cash; annual ROIC measures capital efficiency.
Positive EBITDA does not prove positive cash flow or recovery of the opening investment. Review Returns, Cash Flow, and Sources & Uses separately.
The Returns analysis contains operating break-even, cash break-even, investment payback, and annual ROIC measures. These calculations support separate questions about covering ongoing costs, funding shortfalls, and recovery of capital committed to the antique mall.
Valuation sensitivities, ratios, and user-entered benchmarks are available, but the case provides no actual valuation, payback date, or return result.
These answers describe the operating assumptions and report functions included in this Excel template.
No. The documented business earns vendor-space rental income only; dealers own their inventory and merchandise card costs are passed through without markup.
Yes. Edit the common occupancy assumption, the five rental category shares, and each category’s annual monthly rent to recalculate revenue.
The case includes 180 places: 90 standard booths, 36 large booths, 18 deluxe cases, 18 standard cases, and 18 shelf units.
No. The documented manager, checkout and floor staff, and vendor administration base salaries are booked to Payroll once.
No. The published illustrative operating results stop at EBITDA, which does not establish net profit or a positive cash balance.
Yes. Dashboard debt controls support financing inputs, and CapTable records equity contributions; the documented base case assumes initial owner funding without external debt.
No. Investment payback requires separate cash-flow calculations, while sales break-even, cash break-even, and annual ROIC answer different questions.
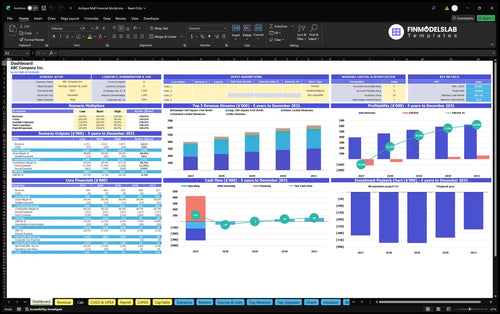
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
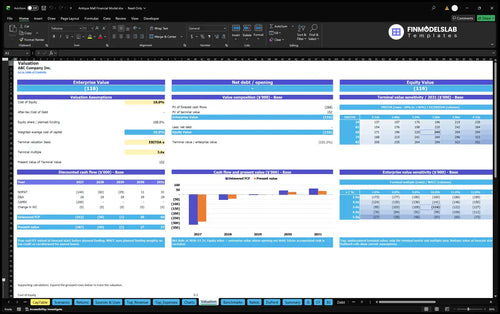
DCF valuation and sensitivity analysis.
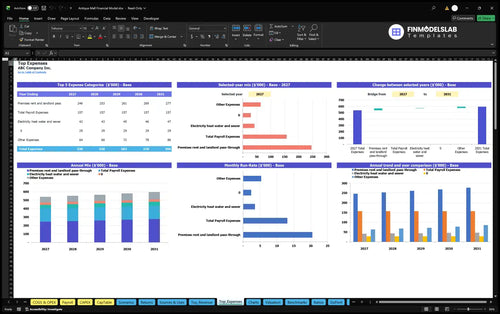
Largest costs and spending trends.
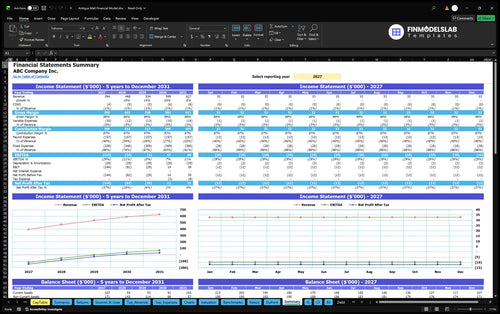
Annual and monthly financial performance.
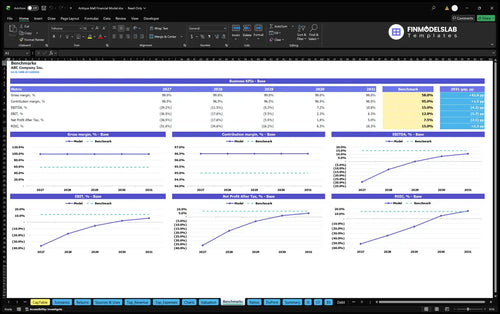
Compare margins and returns to benchmarks.

I stopped juggling separate low, base, and high cases by hand, and the template made scenario setup much cleaner. It saved me a few hours and made the assumptions easy to compare.

Building the projections from scratch would have taken me all weekend. This model got me to a working draft in under two hours, which made planning the launch a lot less stressful.
My statements and charts were all over the place before this. Now everything is in one file, so I had a clearer package to share in my investor update and booked a follow-up meeting faster.