

Room Revenue & Calc
Set room inventory, the 28-night monthly booking limit, occupancy, seasonal factors, and category rates. Monthly calculations allocate sold nights across room types without duplicating room-night capacity.


The Boutique Hotel Financial Model is an Excel template for forecasting room-night revenue, operating costs, staffing, and startup investment for a leased 30-room hotel. It connects room occupancy and tariffs to monthly calculations and financial reports for 2026–2030.
The illustrative North Carolina case has five room categories, continental breakfast, and parking included in lodging rates, without standalone restaurant, bar, spa, or event revenue. Its assumptions and projections are examples, not observed hotel results.
The workbook combines a room-night revenue build with the supporting costs, financing schedules, statements, and management analysis needed to evaluate a hotel plan.
Set room inventory, the 28-night monthly booking limit, occupancy, seasonal factors, and category rates. Monthly calculations allocate sold nights across room types without duplicating room-night capacity.
Plan linen, breakfast, booking commissions, property expenses, staffing levels, and pay by role. Separate schedules show how each operating cost enters the forecast.
Record leasehold improvements, furnishings, technology, opening expenses, equity contributions, and optional debt inputs with supporting depreciation and repayment schedules.
Use the Income Statement, Cash Flow Statement, and Balance Sheet to examine accounting earnings, cash movements, and financial position under the selected settings.
Compare Low, Base, and High cases; review break-even, payback, return on invested capital, valuation sensitivity, and performance charts without treating these as established outcomes.
Hotel room revenue equals occupied room-nights multiplied by the realized nightly rate for each category, with monthly seasonality shaping when stays occur.
Each of the 30 rooms has 28 bookable nights a month, creating 840 potential room-nights. Occupancy progresses from 52% in 2026 to 72% in 2030, while repeating January–December multipliers adjust the distribution of booked nights across months.
Sold nights are allocated once to 12 Classic Queen, 9 Classic King, 5 Deluxe King, 3 Junior Suite, and 1 Signature Suite. Each category has its own annual nightly tariff. Breakfast and parking are included in these rates, not modeled as additional revenue streams.
The Revenue Forecast links room inventory, occupancy, seasonal booking patterns, room-type allocation, and nightly pricing to annual hotel sales. It also feeds the detailed monthly calculations used in the financial projections.
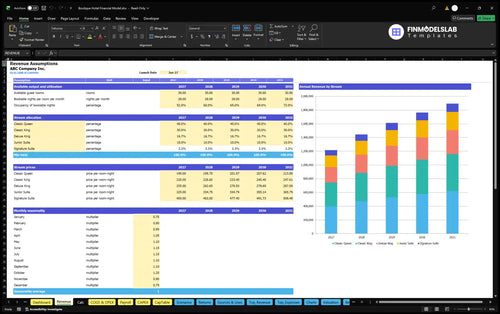
840 bookable nights/month × 52% occupancy × $232 room-mix weighted nightly rate × 12 annualized seasonal months = $1,216,051 (approximately).
Direct costs, variable expenses, fixed overhead, and role-based payroll are modeled separately to show which spending changes with revenue and which spending must be covered regardless of occupancy.
COGS total 9% of revenue: outsourced laundry 4%, cleaning and guest consumables 1.5%, breakfast ingredients 2.5%, and replacement smallwares 1%. Variable operating expenses add 13.2% for OTA commissions, payment charges, direct booking marketing, and guest recovery.
The COGS & Operating Expense Forecast separates revenue-linked laundry, breakfast supplies, booking fees, and marketing from monthly lease and property costs. Use it to understand cost mix, contribution margin, and the expenses feeding EBITDA.
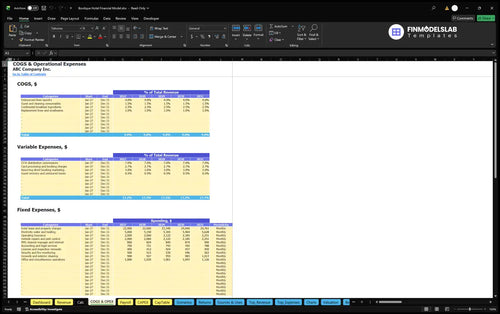
Monthly fixed expenses cover the lease, utilities, insurance, maintenance, technology, administration, licenses, security, and grounds. Hotel lease and property charges begin at $22,000 per month in 2026.
Payroll covers management, front desk, housekeeping, maintenance, and guest breakfast service. Room attendant staffing increases from 3.0 to 3.5 annual-average FTE across the example years.
The Payroll Forecast plans staff by role, annual-average FTE, and fixed annual compensation. In the example, first-year base pay ranges from $36,000 for front desk and room attendant FTE to $75,000 for the manager; payroll is not counted again in COGS or fixed expenses.
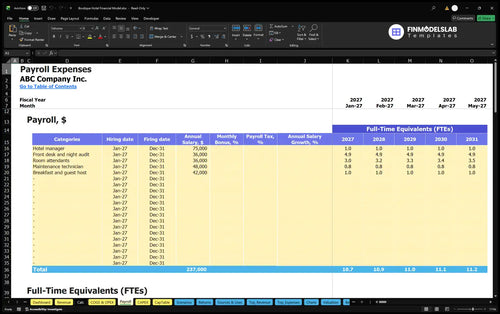
The documented cost case keeps Payroll separate from COGS, revenue-based variable expenses, and fixed overhead. Employer payroll taxes and benefits are excluded from these illustrative assumptions.
The opening budget separates durable improvements and equipment, preopening cash needs, working capital settings, and owner contributions from regular annual hotel operating expenses.
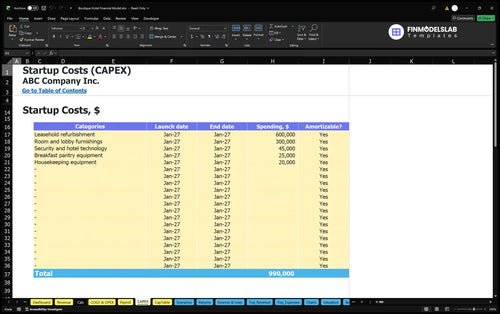
The illustrated startup assets include $600,000 of leasehold refurbishment, $300,000 of room and lobby furnishings, $45,000 of security and hotel technology, and $25,000 of pantry equipment, plus housekeeping equipment. These are investment inputs, not an additional annual operating expense line.
Other opening cash items include lease deposits, training, licensing, launch marketing, and setup costs. The working-capital controls assume zero receivable days and eight days each for payables and inventory.
The Capital Expenditure Plan records refurbishment, furnishings, technology, equipment purchases, spending dates, and depreciation treatment. It distinguishes investment timing from the monthly operating cost schedule.
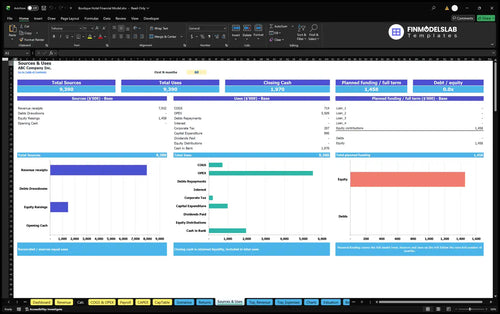
The model case uses $1,457,574 of estimated initial owner funding, based on opening assets, separate preopening cash, physical launch working capital, and three months of first-year operating outflows. It assumes owner funding for the example rather than an established lending commitment.
The Sources and Uses of Funds report reconciles financing inflows with operating payments, capital investment, and cash retained in the business. The Dashboard also supports optional debt facilities, but the illustrated startup funding input is equity.
The documented North Carolina planning case projects annual hotel revenue, total operating expenses, and EBITDA from 2026 through 2030 in nominal US dollars.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $1,216,051 | $1,130,963 | $85,088 |
| 2027 | $1,445,230 | $1,201,749 | $243,481 |
| 2028 | $1,612,635 | $1,255,602 | $357,033 |
| 2029 | $1,763,245 | $1,306,119 | $457,126 |
| 2030 | $1,895,090 | $1,352,876 | $542,215 |
Forecast values are illustrative and rounded to whole dollars. Display rounding can create minor differences in row arithmetic.
In this case, higher modeled occupancy and tariffs expand annual revenue while fixed costs and staffing grow more slowly. EBITDA rises from approximately $85,088 in 2026 to $542,215 in 2030. These are model outputs, not an assurance of hotel profitability.
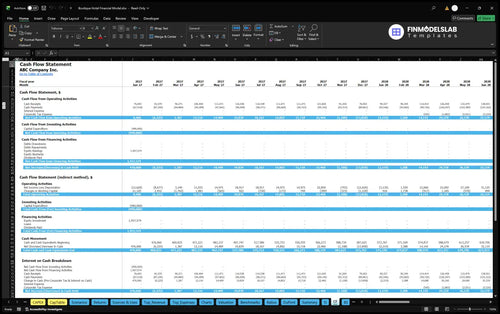
The Cash Flow Forecast tracks operating receipts and payments, capital spending, debt movements, and equity funding through monthly cash reconciliations. Review this report to assess liquidity rather than treating the example EBITDA figures as cash available for distribution.
The Returns, scenario, valuation, and benchmark tools help compare operating viability with longer-term investment outcomes without assigning unsupported payback dates or return percentages.
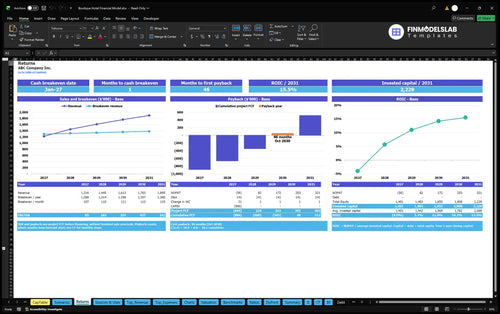
Sales break-even identifies revenue needed to cover the modeled cost structure. Cash break-even examines the timing of cash coverage, while investment payback asks when cumulative project cash flow recovers invested funds. Annual ROIC measures return relative to invested capital; none is interchangeable with EBITDA margin.
Dashboard Low, Base, and High controls adjust revenue and costs. Scenario comparisons, discounted cash-flow valuation, and sensitivity analysis support further investment review.
The Return on Invested Capital Analysis brings together break-even, cash-flow-based investment payback, and annual ROIC measures. Use these distinct outputs to examine investment recovery and capital efficiency after adjusting hotel occupancy, pricing, spending, and funding assumptions.
The source operating case ends at EBITDA. The documented inputs do not establish net income, a specific payback month, ROIC, valuation, or proof that opening capital is sufficient under every scenario.
These answers clarify the scope, editable assumptions, financial reports, and limits of the boutique hotel example.
Yes. Edit five nightly tariffs, annual occupancy, and monthly seasonality to recalculate sold room-nights, revenue, and connected financial projections.
No. Continental breakfast and parking are included in lodging tariffs; separate restaurant, bar, spa, and event operations are outside the documented case.
No. Role-based Payroll is separate from COGS, variable operating expenses, and fixed overhead in the illustrated operating forecast.
Yes. The standard workbook includes Income Statement, Cash Flow Statement, Balance Sheet, and combined Summary reports; the documented sample figures only establish revenue, operating expenses, and EBITDA.
Yes. Equity and debt schedules, Sources & Uses, Cash Flow, and investment-return reports are included. The illustrated opening funding assumption is owner equity.
No. EBITDA values are scenario-based projections, and no specific payback date or investment return is established by the supplied case.
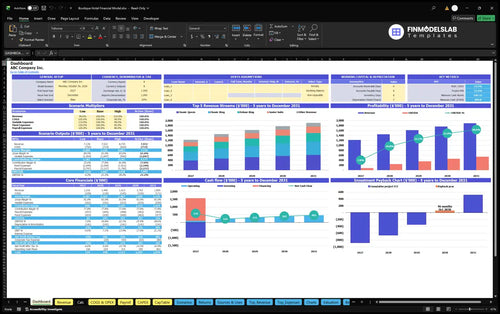
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
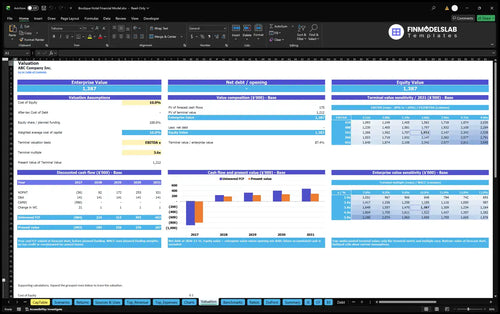
DCF valuation and sensitivity analysis.
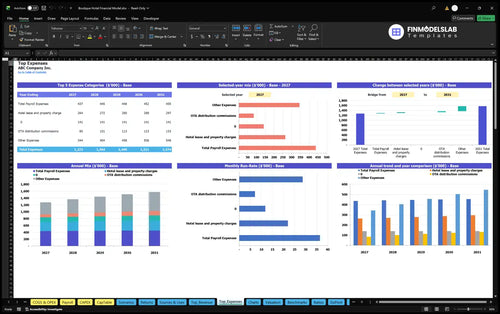
Largest costs and spending trends.
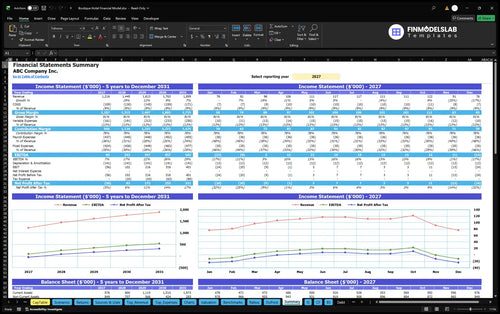
Annual and monthly financial performance.
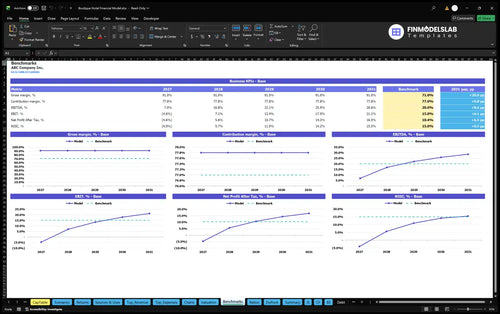
Compare margins and returns to benchmarks.

I stopped digging through scattered files and finally had one place for statements and charts. It saved me about 6 hours on monthly reporting and made the numbers easy to send to our team.
I’m not an Excel expert, so this template was a relief. The layout made advanced hotel modeling feel manageable, and I had a working forecast ready for review in under an hour.
The pricing, cost, and growth inputs were organized in a way that made sense right away. It helped me clean up my assumptions and get a planning call booked the same day.