Turn fixed costs, variable costs, selling price, and a target profit into clear break-even requirements for your business, product, service, or proposed project.
This Excel workbook supports both unit-based and price-based analysis. Enter your operating assumptions, review contribution margin and break-even outputs, and test how a different price or sales volume changes the level of activity required to cover costs or reach a selected net-income target.
Set a minimum sales target
Calculate the units and sales revenue required for total revenue to cover fixed and variable costs.
Evaluate pricing decisions
Estimate a break-even selling price and compare it with the price needed to reach a chosen profit objective.
Test operating sensitivity
Review how changes in price affect the number of units required to deliver the targeted result.
What does the template help you analyze?
The workbook applies cost-volume-profit logic to show the relationship between price, unit economics, fixed overhead, sales volume, and profit. It is designed for planning decisions where the central question is how much must be sold, or at what price, before the activity becomes financially viable.
Break-even volume and sales: determine the units and revenue required to cover the modeled cost structure.
Contribution economics: calculate contribution margin per unit and the contribution margin ratio after variable costs.
Target-profit requirements: estimate the units and sales needed to reach a selected net income before taxes.
Break-even pricing: calculate the selling price required at a specified number of units.
Price-volume sensitivity: compare the target units associated with alternative price percentages.
What is inside the workbook?
The visible workbook views separate editable assumptions from calculated results. Input areas cover selling price or unit volume, fixed-cost categories, variable-cost categories, and targeted net income. The calculation areas summarize total fixed costs, variable cost per unit, contribution margin, break-even units, break-even sales, target-profit requirements, and return on sales before taxes. Charts then present the relationship among total cost, total revenue, profit or loss, and the selected profit target.
Editable operating assumptions
Organize fixed costs by category, enter per-unit or percentage-based variable costs, and set the relevant price or activity level.
Calculated decision metrics
Review contribution margin, break-even units, break-even sales, and the activity required for a chosen profit amount.
Visual and scenario outputs
Use break-even charts and sensitivity views to compare cost, revenue, profit, and alternative price-volume combinations.
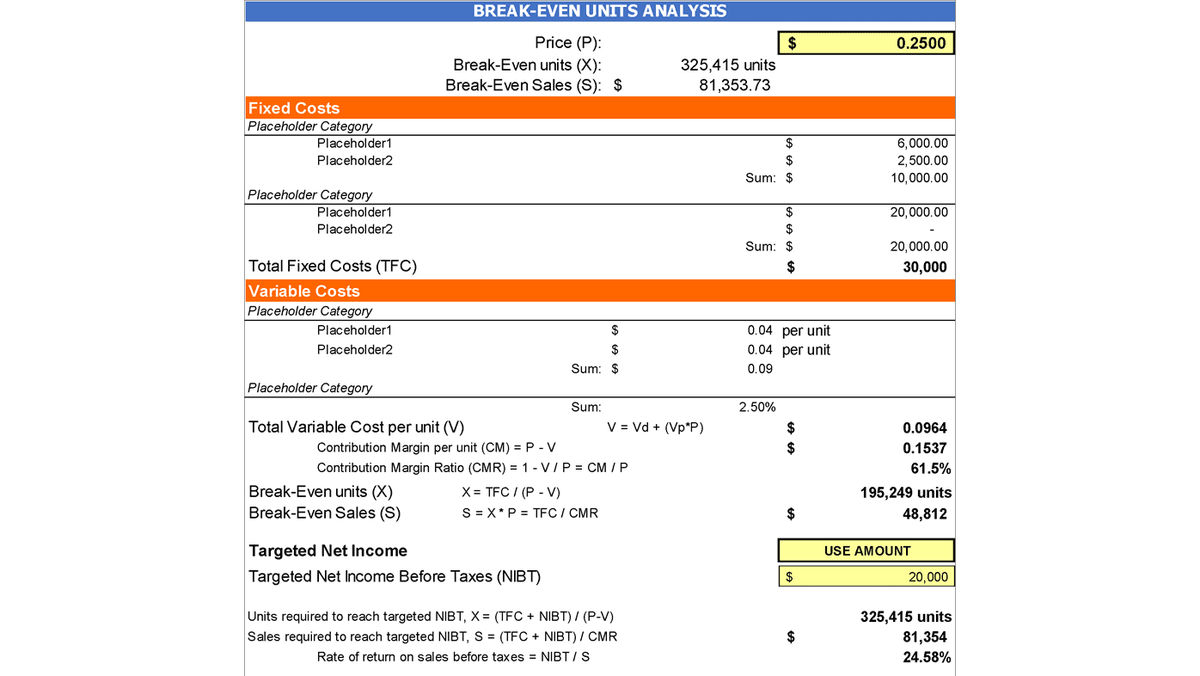
The unit-analysis worksheet connects price and cost inputs to break-even units, break-even sales, contribution margin, and target-income requirements.
Build the unit-based break-even case
Enter a selling price, group recurring fixed costs, and add variable costs per unit or as a percentage of price. The worksheet then calculates how much each unit contributes toward fixed costs, the break-even volume, and the volume needed to reach the selected net-income target.
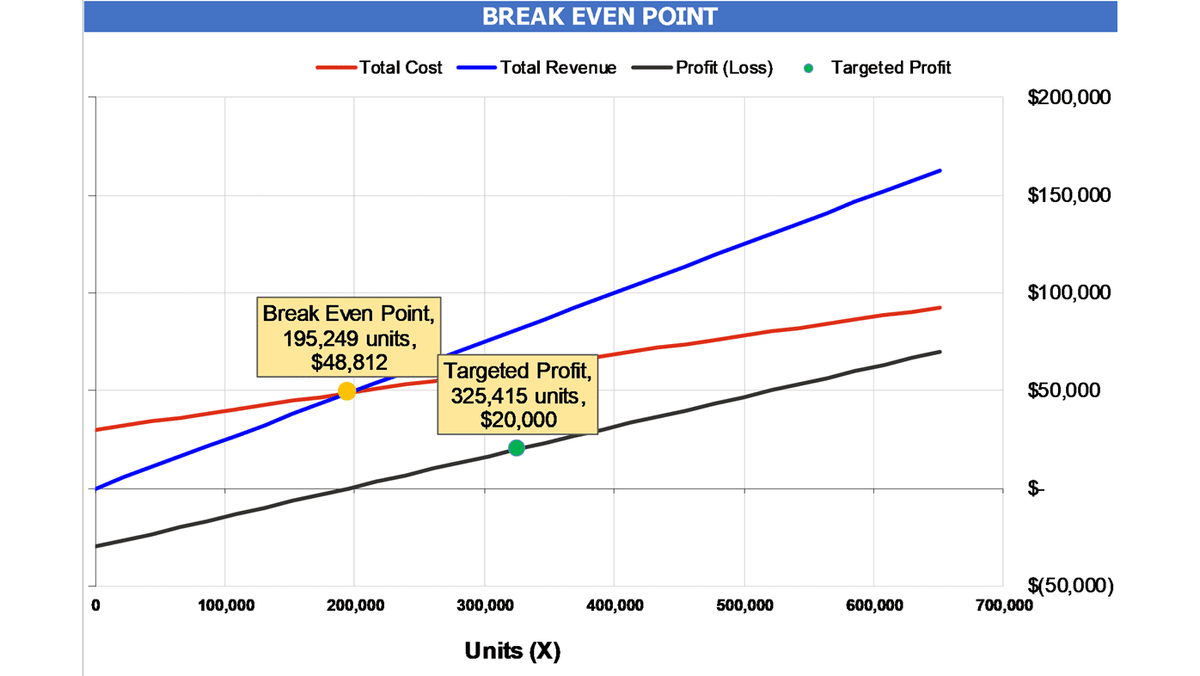
The chart marks where total revenue meets total cost and shows the separate volume associated with the targeted profit.
See where revenue overtakes cost
The break-even chart plots total cost, total revenue, and profit or loss across unit volume. Labeled markers identify both the break-even point and the target-profit point, helping managers communicate the operating threshold without relying only on a formula table.
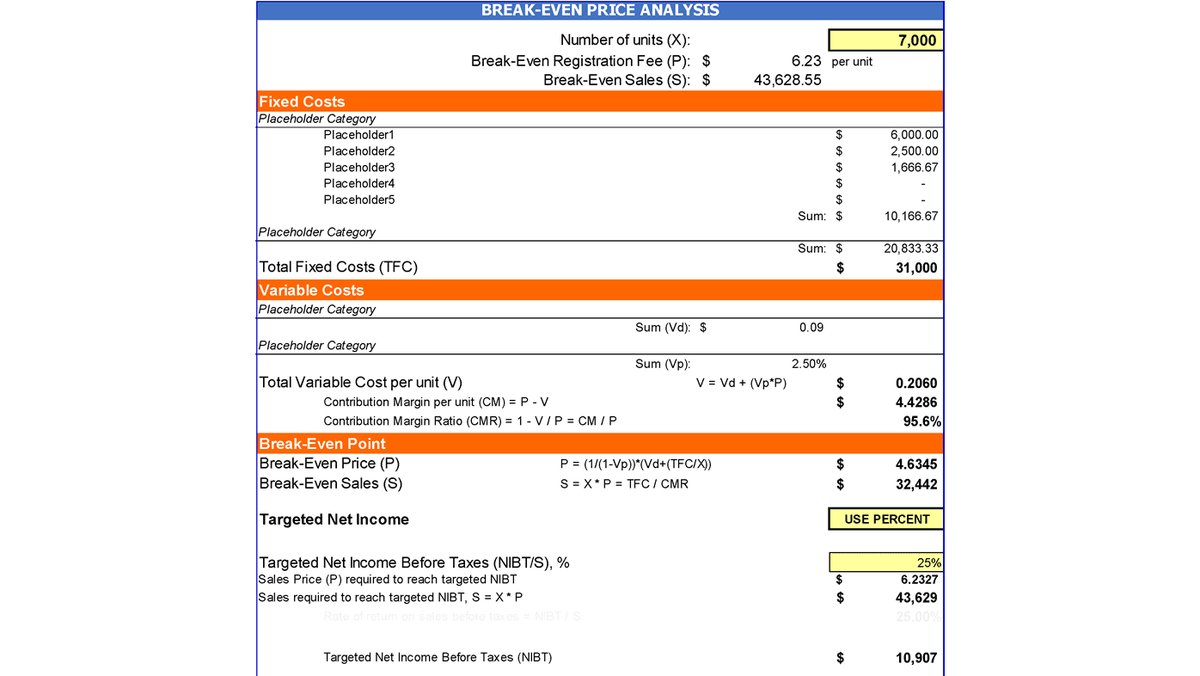
The price-analysis worksheet estimates the break-even price and the price required for a selected profit at a defined sales volume.
Work backward from expected volume
When expected unit sales are known, the price analysis reverses the question. It uses the modeled cost structure and unit count to calculate a break-even price, break-even sales, and the selling price needed to reach the target net income.
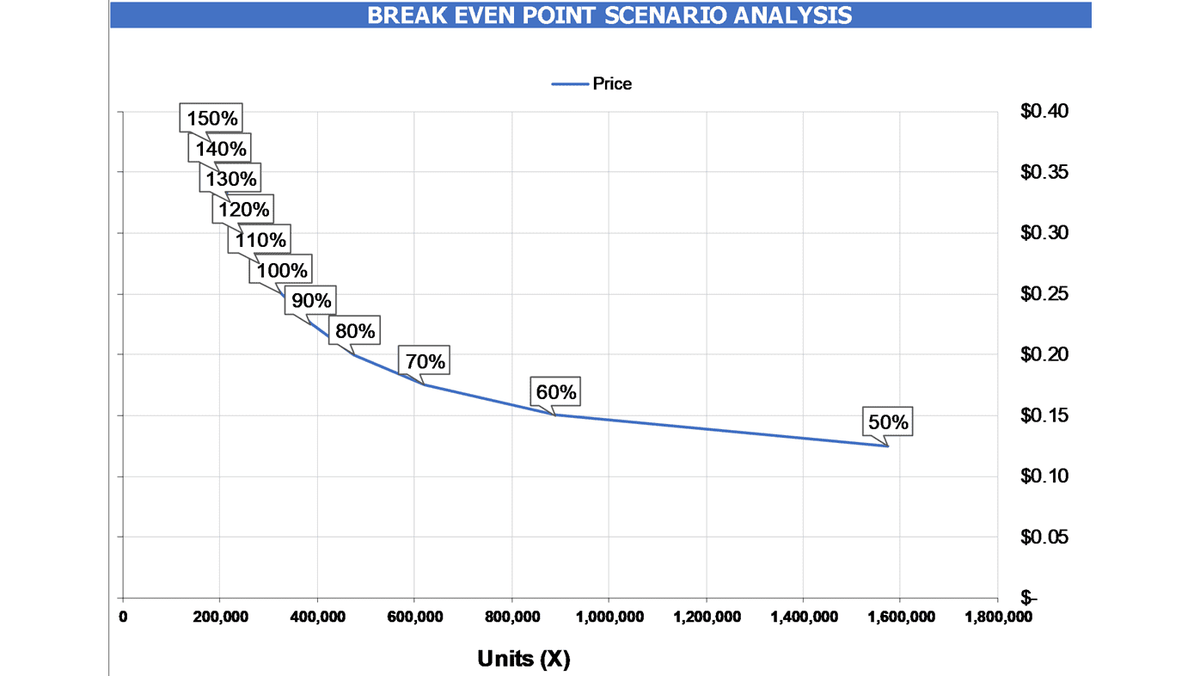
The scenario curve shows how the units required for the target result change as the modeled price moves above or below the base case.
Compare alternative price levels
The sensitivity view displays the trade-off between price and required volume. It can be used to assess whether a lower price would demand an unrealistic increase in sales, or whether a higher price materially reduces the operating volume needed to achieve the target.
How do you use the template?
Define the decision
Choose whether you need to solve for required units at a known price or solve for the required price at a known unit volume.
Enter the cost structure
List fixed-cost categories and input variable costs that change with each unit sold or as a percentage of selling price.
Set the operating target
Enter the base price or expected unit volume, then specify the desired net income before taxes using the available target input.
Review and stress-test
Compare break-even and target-profit outputs, inspect the charts, and test alternative price assumptions before setting sales goals or approving the plan.
Who is this template for?
This workbook is suited to founders validating a new offer, business owners reviewing whether current pricing covers overhead, managers setting unit or revenue targets, and analysts evaluating a project, product launch, service line, or expansion. It is most useful when costs can be separated into fixed and variable components and the decision depends on the relationship among price, volume, contribution margin, and profit.
Use the results as a structured planning reference alongside realistic sales assumptions and complete cost data. The model makes the operating threshold visible so decision-makers can compare the base case with alternative pricing and volume choices.
Choosing a selection results in a full page refresh.