

Revenue & Calc
Store visits, purchase conversion, retained units, seasonal demand, category shares, and item prices flow into monthly and annual boutique sales.


The Clothing Boutique Financial Model is an Excel template for planning a neighborhood women’s apparel and accessories store. It converts customer traffic, purchase conversion, retained items, product mix, and selling prices into monthly revenue, then connects merchandise costs, store expenses, and staffing to financial projections.
The illustrative case covers a roughly 1,100-square-foot, affordable midrange multibrand boutique in a suburban U.S. secondary market from 2026 through 2030. Its launch is January 31, 2026, with January treated as a full active sales month; the location and assumptions are estimates, not a signed retail plan.
Connected planning schedules translate editable store assumptions into management reports and financial statements.
Store visits, purchase conversion, retained units, seasonal demand, category shares, and item prices flow into monthly and annual boutique sales.
Merchandise purchasing, inbound freight, shrinkage, variable selling costs, recurring overhead, and role-based compensation remain separate inputs.
Store fixtures and equipment, owner contributions, and optional financing facilities feed capital and funding schedules without being treated as sales.
Central settings and Low, Base, and High operating multipliers provide a management view of how different assumptions affect margins and EBITDA.
Income Statement, Cash Flow, Balance Sheet, Summary, Returns, Valuation, Charts, and checks help review distinct aspects of the modeled business.
Demand drives the forecast: trading days and visitors become retained item sales through conversion, items per purchase, seasonality, category share, and net item price.
The 2026 Base case uses 26 trading days per month, 55 visitors per trading day, 25% purchase conversion, and 1.6 retained items per purchase. That produces 572 items in an unadjusted month before applying the repeating seasonal demand profile.
A single pool of sold items is divided among tops (30%), dresses (22%), bottoms (25%), outerwear (8%), and accessories (15%). Category volumes are multiplied by net prices, starting at $48, $88, $68, $110, and $32 per item respectively; sales exclude returns, markdowns, and sales tax.
The Revenue Forecast connects boutique traffic, conversion, seasonal retained-item volume, category allocation, and realized selling prices. Its monthly calculations are consolidated into annual sales so you can see how a change in either demand or merchandise mix affects projected revenue.
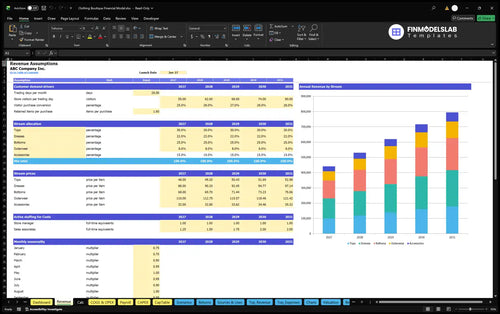
26 days × 55 visitors × 25% conversion × 1.6 items = 572 base-month items; 572 × $64.36 weighted item price × 12.0 annual seasonality total = approximately $441,767, rounded to whole dollars.
The monthly demand factors range from 0.75 in January and February to 1.50 in December, repeating each forecast year. The daily visitor assumption rises to 80 by 2030, while modeled conversion reaches 28%; the revenue engine has no capacity ceiling.
The cost plan separates sales-linked merchandise and selling expenses from monthly fixed overhead and salaries.
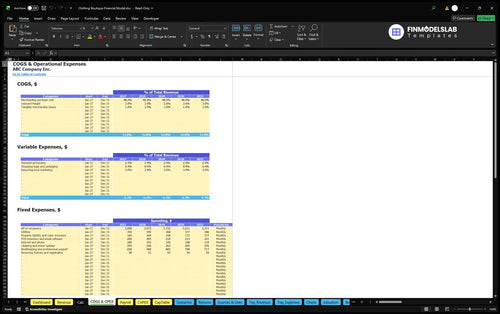
COGS includes merchandise purchases at 48% of revenue, inbound freight at 3%, and tangible merchandise losses at 1%. Variable costs comprise payment processing at 2.9%, packaging at 0.4%, and recurring local marketing at 3%, while fixed overhead covers occupancy, utilities, insurance, software, and operating support.
For 2026, the illustrative operating cost plan includes $229,719 in COGS, $27,831 in variable expenses, $57,120 in fixed expenses, and $94,500 in payroll. These categories total approximately $409,170, with salaries counted only in Payroll.
The COGS and Operating Expenses forecast separates revenue-linked merchandise and selling costs from fixed expenses, including the modeled $3,000 monthly all-in occupancy input in 2026. This distinction makes changes in gross margin and EBITDA easier to trace to their assumptions.
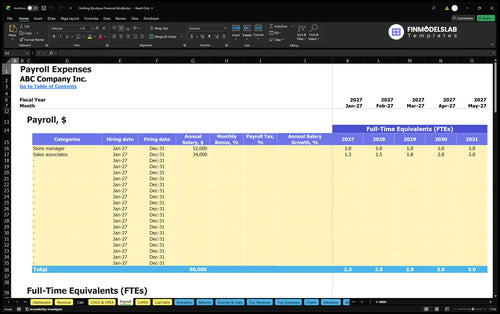
The store manager is modeled at 1.0 full-time equivalent with $52,000 annual base salary. Sales associate staffing increases from 1.25 FTE in 2026 to 2.0 FTE by 2029, at a $34,000 annual base salary per FTE.
The Payroll Forecast schedules staffing levels and compensation by role, including the boutique manager and sales associates. It lets you connect changes in annual-average FTE and annual base pay to monthly personnel costs without mixing those salaries into merchandise cost ratios.
Opening investment and cash requirements are modeled separately from ongoing operating expenses and EBITDA.
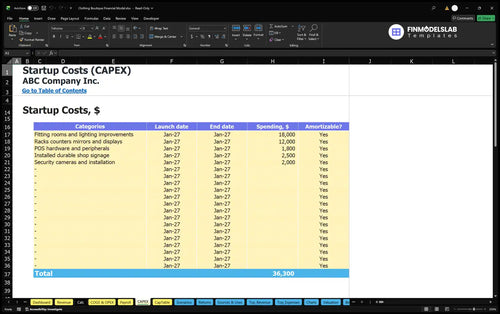
Illustrative startup assets include $18,000 for fitting rooms and lighting, $12,000 for racks and displays, $1,800 for POS hardware, and $2,500 for installed signage, plus security equipment. Separate preopening cash items include the lease deposit, registration and legal costs, launch advertising, and training.
Working-capital controls use 90 inventory days, zero receivable days, and zero payable days. These settings distinguish cash tied to physical merchandise from immediately collected retail sales; the case makes no claim that its starting cash reserve has been stress-tested.
The Capital Expenditure Plan records store improvements, displays, equipment, and other asset purchases by date and tracks the associated depreciation schedule where applicable. It helps separate one-time investment in the boutique from the recurring expense assumptions used for operating EBITDA.
Estimated initial owner funding is $211,636, assembled from durable assets, pre-calendar payments, opening inventory, and a three-month recurring outflow reserve. The selected case assumes no committed external financing; debt controls exist in the workbook for a buyer to model alternatives.
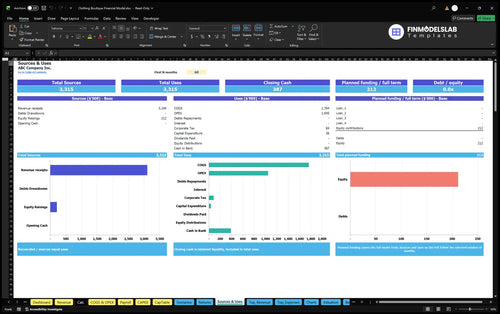
The Sources and Uses of Funds report organizes equity, optional borrowing, operating and investing cash uses, and cash retained over a selected forecast period. It is useful for checking where initial boutique funding is allocated, not for treating owner contributions as operating income.
The selected operating case projects growing revenue and EBITDA as traffic, conversion, prices, and store operating costs develop over five forecast years.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $441,767 | $409,170 | $32,597 |
| 2027 | $530,859 | $471,039 | $59,820 |
| 2028 | $619,727 | $532,813 | $86,915 |
| 2029 | $716,900 | $599,464 | $117,435 |
| 2030 | $794,391 | $646,179 | $148,211 |
Selected Base-case projections, rounded to whole dollars; displayed arithmetic may differ by $1 because of rounding.
In this illustration, revenue increases from $441,767 in 2026 to $794,391 in 2030, while EBITDA rises from $32,597 to $148,211. The reported 2030 operating expenses are $646,179, reflecting both sales-linked costs and expanded staffing.
EBITDA is operating earnings before interest, taxes, depreciation, and amortization, not net income or available cash. The documented scenario provides numerical results only through EBITDA, even though the workbook includes linked Income Statement, Cash Flow, and Balance Sheet reporting functions.
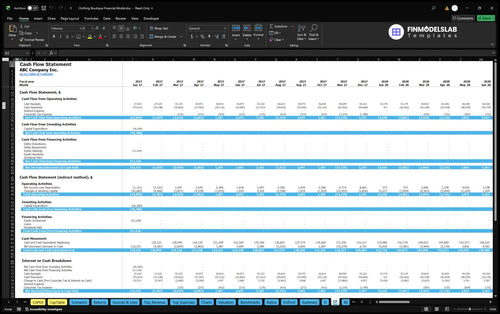
The Cash Flow Forecast organizes operating receipts and payments alongside investing and financing movements, including potential debt and owner funding entries. Use it to assess modeled cash balances and liquidity separately from boutique EBITDA; the case brief does not establish an independently tested cash sufficiency result.
The workbook supports separate operating, cash, and investment questions, but the supplied case does not establish numerical payback or valuation results.
Sales break-even examines the level of boutique revenue needed to cover modeled operating costs. Cash break-even instead looks at cash timing, investment payback tracks recovery of the initial investment through project cash flows, and annual ROIC compares returns against invested capital.
Low, Base, and High scenario multipliers can vary revenue, COGS, variable expenses, fixed expenses, and payroll. Review the resulting EBITDA and margins together with cash flow and financing schedules rather than assuming a stronger operating margin automatically guarantees adequate liquidity.
The Returns report distinguishes sales break-even, cash break-even, investment payback, and return on invested capital. Those measures can help compare alternative boutique plans, but no specific payback period, annual ROIC, or investment IRR is evidenced by the provided operating forecast.

Quick answers about the boutique Excel template, its drivers, and how to interpret the forecasts.
It multiplies trading days, daily store visitors, purchase conversion, retained items per purchase, seasonality, category unit share, and net category item price.
Yes. Tops, dresses, bottoms, outerwear, and accessories have editable unit shares and prices within one shared demand pool.
The documented case uses a 90-day inventory assumption; the workbook also includes working-capital and balance-sheet reporting schedules.
No. The manager and sales associates are costed separately in Payroll, with employer taxes and benefits excluded from the illustrative case.
No. It is illustrative 2030 EBITDA, before depreciation, interest, and tax; neither net income nor available cash is established by that figure.
Yes. Low, Base, and High controls can vary sales, direct costs, other operating expenses, and payroll for scenario comparisons.
No specific payback month is provided. The Returns report can evaluate investment payback after appropriate investment and cash-flow assumptions are entered.
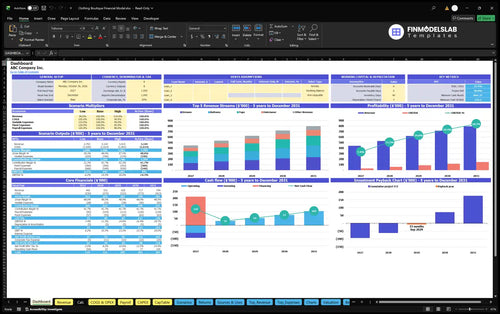
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
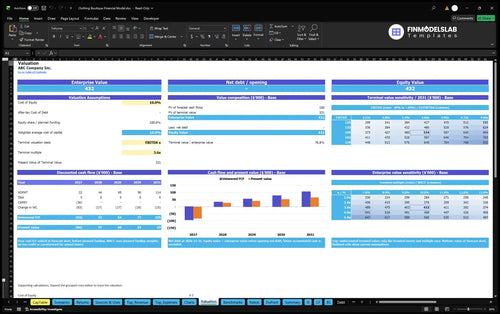
DCF valuation and sensitivity analysis.
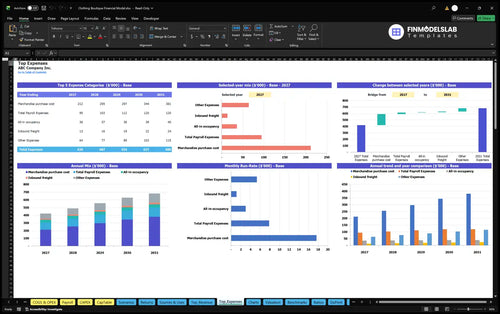
Largest costs and spending trends.
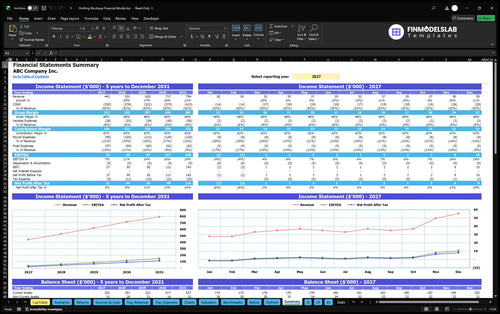
Annual and monthly financial performance.
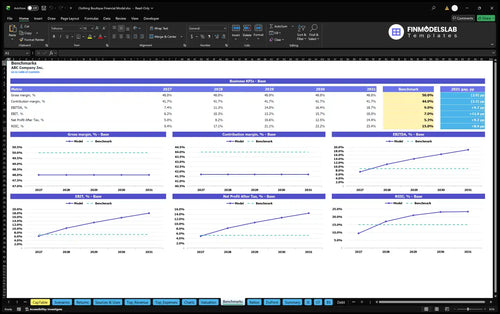
Compare margins and returns to benchmarks.

I was stuck staring at an empty spreadsheet, and this gave me a place to start right away. I cut my setup time by hours and had a working boutique forecast the same day.
The pricing, inventory, and expense sections finally felt organized instead of scattered. I was able to tighten my assumptions in one sitting and walk into my planning meeting with clearer numbers.

I worried one bad formula would throw everything off, but this template kept the calculations clean. I caught issues faster and trusted the model enough to share it without rechecking every cell.