

Revenue and Calc
Set operating days, selling hours, drinks per hour, utilization, monthly seasonality, six beverage shares, and annual net selling prices. Monthly calculations allocate one sold-drink pool across all beverages.


The Coffee Truck Financial Model is an Excel template for building 2026–2030 financial projections for one mobile coffee truck. It connects selling days, beverage throughput, menu mix, prices, and seasonality to revenue, operating expenses, and EBITDA.
The workbook links coffee-truck-specific operating inputs to monthly calculations, financial statements, and decision reports.
Set operating days, selling hours, drinks per hour, utilization, monthly seasonality, six beverage shares, and annual net selling prices. Monthly calculations allocate one sold-drink pool across all beverages.
Plan ingredients, beverage supplies, card processing, host commissions, fixed truck expenses, and role-based compensation without counting wages in another expense category.
Select Low, Base, or High multipliers for revenue and cost assumptions, then compare revenue, margins, and EBITDA. The Dashboard also provides debt-entry controls if financing is later modeled.
Monthly beverage sales depend on available truck service capacity, utilization, seasonal demand, beverage mix, and each category’s net selling price.
The case starts with 22 selling days per month, 5 selling hours per day, and 40 drinks per hour, giving 4,400 available beverages before utilization. Selected utilization rises from 55% in 2026 to 75% in 2030.
A repeating January–December seasonality profile adjusts monthly sales. Five entered shares plus one residual share allocate beverages once among brewed coffee, Americano, latte/cappuccino, flavored latte/mocha, cold brew, and tea/chocolate.
The Revenue Forecast connects selling capacity, utilization, seasonality, six beverage shares, and net prices. Changing these inputs shows how monthly sales vary with service throughput and product mix.
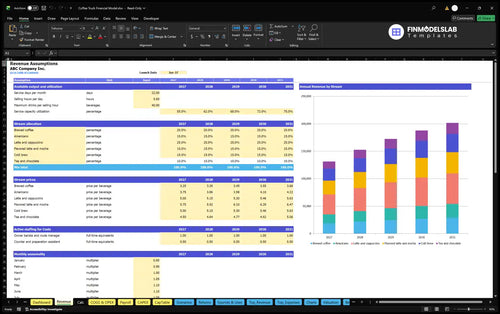
22 days/month × 5 hours/day × 40 drinks/hour × 55% utilization × 12 seasonality-weighted months = 29,040 drinks; 29,040 × $4.525 weighted net beverage price = $131,406 revenue.
Launch is set to January 31, 2026, and the selected launch month is treated as fully active. All streams are zero before launch; there are no separate catering receipts, tax collections, or customer tips in the modeled beverage revenue.
The model separates sales-linked direct costs and commissions from monthly fixed expenses and payroll so each cost enters the forecast once.
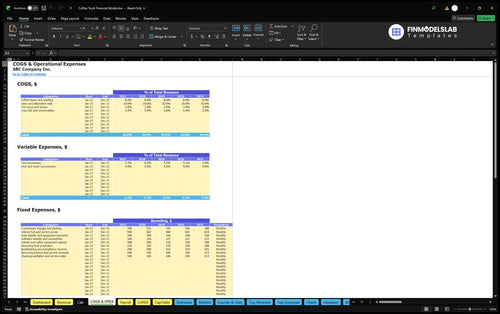
Direct costs are estimated as 26% of total revenue: coffee beans and roasting 8%, dairy and alternative milk 10%, tea/cocoa/syrups 3%, and cups/lids/consumables 5%. Card fees decline from 5.32% of revenue in 2026 to 4.99% in 2030, with host/event commissions at 4%.
Fixed expenses cover commissary parking, fuel and service power, insurance, connectivity, maintenance, promotion, bookkeeping, permit renewals, and sanitation. Commissary storage and parking begins at $700 per month in 2026, increasing to $787.86 per month in 2030.
The COGS and Operating Expenses forecast tracks ingredients, packaging, transaction fees, commissions, and recurring truck expenses. These costs feed operating margins without double-counting payroll.
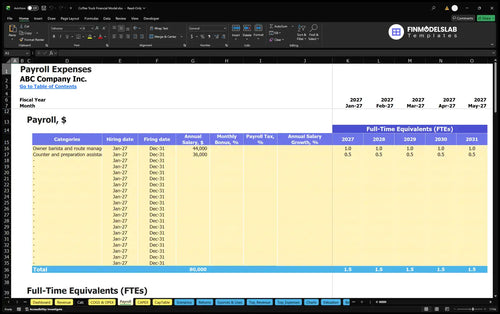
The personnel plan uses one owner-barista and route-manager FTE at $44,000 annual base pay and a 0.5-FTE counter/preparation assistant at $36,000 per full FTE. That produces $62,000 in annual base payroll in the selected case.
Employer payroll taxes, benefits, and personal income taxes are excluded from these illustrated operating assumptions. Buyers can use staffing dates, compensation, and relevant controls to test different schedules without double-counting labor.
The Payroll Forecast calculates FTE and salaries by role using staffing schedules. It helps compare labor costs against expected drink volumes and planned service hours.
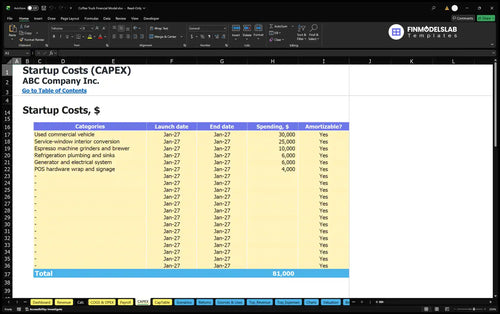
Starting the coffee truck requires capital assets, preopening cash outlays, inventory, and funding decisions in addition to recurring operating expenses.
The selected startup assets include a $30,000 used commercial vehicle, $25,000 service-window conversion, $10,000 espresso and brewing equipment, and $6,000 refrigeration/plumbing. Generator, electrical, POS, wrap, and signage investments are separate items.
Initial permits, refundable commissary deposits, a launch campaign, and preopening training are separately identified cash uses. The case also sets zero accounts-receivable and payable days, plus 14 inventory days as a working-capital assumption.
The Capital Expenditure Plan records truck conversion, equipment purchases, timing, and depreciation treatment. These investment cash uses sit outside operating EBITDA.
Illustrative initial owner funding is $122,778, with no loan or grant in the case. Its planning basis includes startup assets, other opening cash items, opening inventory, and a reserve equal to three months of first-year operating outflows.
That reserve is a funding policy, not proof that initial cash covers every future shortfall. Dashboard debt controls and CapTable contributions allow financing assumptions to be assessed separately from sales and operating earnings.
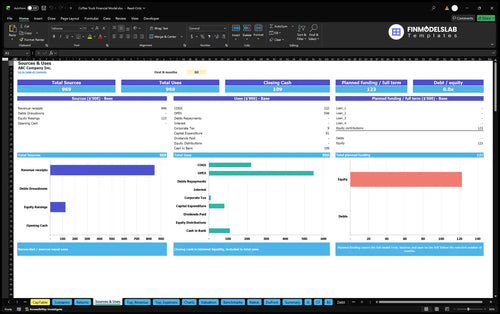
The Sources and Uses of Funds report reconciles owner contributions, optional borrowing, operating payments, and capital purchases. Funding receipts are not revenue or EBITDA.
The supplied Base-style operating illustration moves from a first-year EBITDA loss to positive EBITDA as beverage utilization increases.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $131,406 | $138,657 | −$7,251 |
| 2027 | $152,583 | $146,912 | $5,671 |
| 2028 | $172,303 | $154,652 | $17,652 |
| 2029 | $187,913 | $160,947 | $26,966 |
| 2030 | $201,703 | $166,612 | $35,091 |
Illustrative estimates rounded to the nearest dollar; rounding can affect displayed differences.
These numbers are planning outputs, not actual performance or industry averages. EBITDA reflects revenue less the specified operating expenses before depreciation, interest, taxes, and other items that may affect net earnings and liquidity.
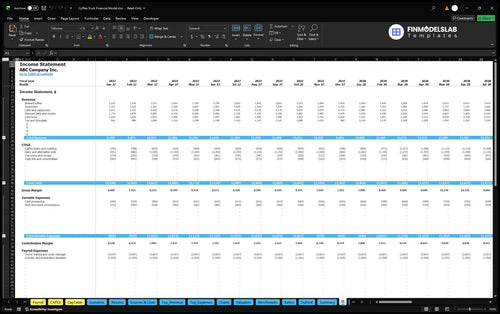
The Projected Income Statement reports monthly margins, EBITDA, depreciation, financing costs, tax, and net profit. The supplied case confirms illustrative EBITDA, not net income.
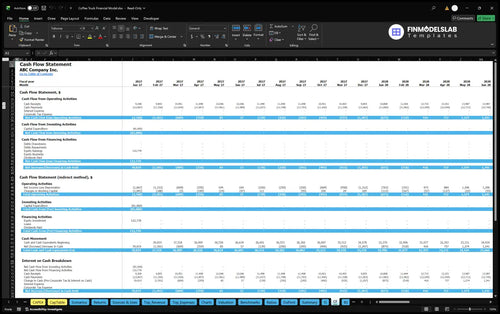
For cash planning, beverage receipts occur at sale under the zero-receivables-day case, while inventory purchases, truck investments, owner contributions, and any debt cash flows can shift the cash balance independently of EBITDA.
Inspect the working-capital, financing, and investment schedules before using the workbook to assess liquidity. The supplied operating illustration does not establish an opening cash balance or validate full-period cash sufficiency.
The Cash Flow Forecast distinguishes operating cash from investment and financing flows. It supports cash-balance reviews and tests of seasonal funding needs.
The Returns and scenario reports help compare operating coverage, investment recovery, and sensitivity without treating EBITDA as available cash.
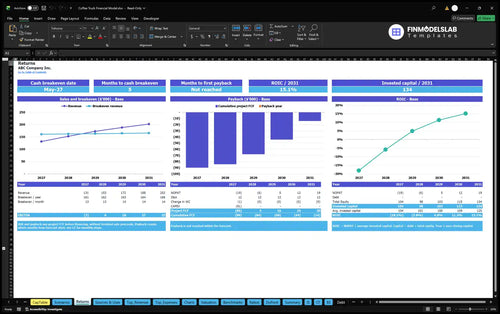
Sales break-even examines the revenue needed to cover modeled costs. Cash break-even considers when cash flows cover cash outlays; investment payback measures recovery of the initial investment, while annual ROIC measures returns relative to invested capital.
The supplied case does not provide calculated payback timing, ROIC, IRR, or valuation. Those results require the workbook’s full investment, cash-flow, and financing schedules and should not be inferred from its EBITDA trend.
The Returns, Payback, and ROIC report separates sales break-even, cash break-even, cumulative project cash flows, payback, and annual returns on invested capital.
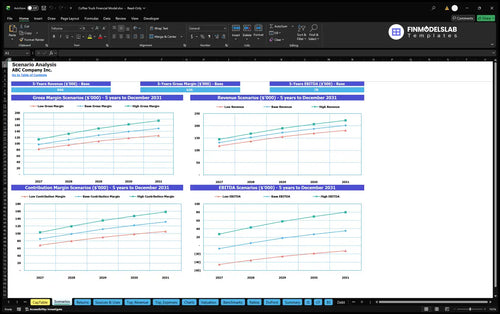
Low, Base, and High scenario controls vary revenue and operating expense multipliers to expose sensitivity to weaker traffic, ingredient inflation, host fees, or staffing changes. These are configurable cases, not forecasts validated against local market observations.
The Financial Scenario Analysis compares Low, Base, and High revenue and margin outcomes. It helps examine sensitivity to route volume and operating-cost assumptions.
Answers to common questions about the template’s editable assumptions and financial reporting.
It multiplies selling days, selling hours, hourly drink capacity, utilization, and monthly seasonality, then allocates one beverage-volume pool across six priced categories.
Yes. Edit the six beverage categories’ sales shares and annual net selling prices in the revenue assumptions.
Yes. Payroll includes role-based FTE, salaries, and staffing schedules; the illustrated case uses one full-time owner-barista and a half-time assistant.
No. EBITDA excludes depreciation, financing interest, taxes, and other factors that may change accounting profit and cash flow.
Yes. The Dashboard offers debt controls and the Debt sheet builds repayment schedules, although the provided example assumes owner funding without borrowing.
No. It is an estimated opening-funding policy based partly on a three-month operating reserve, not a tested cash sufficiency result.
Yes. Returns includes sales break-even, cash break-even, investment payback, and annual ROIC, but no specific payback or ROIC result is established by this case.
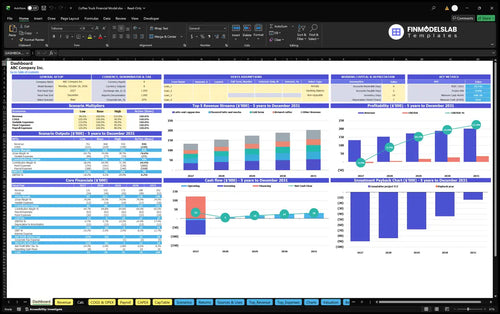
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
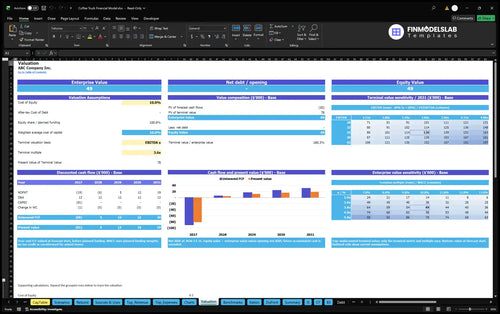
DCF valuation and sensitivity analysis.
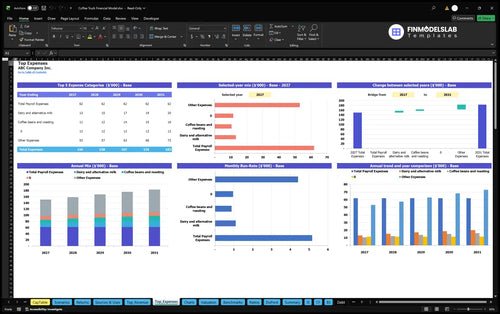
Largest costs and spending trends.
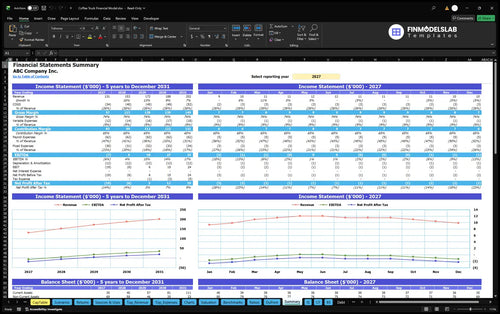
Annual and monthly financial performance.
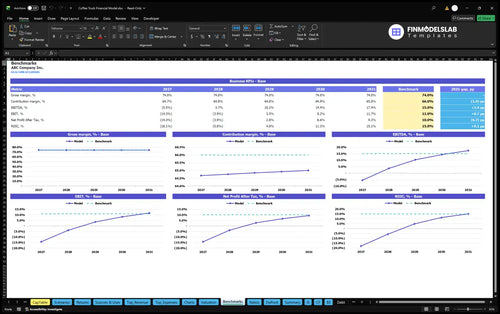
Compare margins and returns to benchmarks.

This pulled my statements and charts into one view, so I wasn’t digging through scattered files before our lender update. I saved about 4 hours and had everything ready to share.

The cash flow view made it obvious when we’d hit a shortfall, and I could see our runway by month instead of guessing. It helped me book a planning call two weeks earlier than planned.
Pricing, costs, and growth assumptions were finally laid out in one place, which made the forecast much easier to follow. I cut my cleanup time by 5 hours and handed off a cleaner model.