

Revenue and Calc
Adjust active contractor accounts, monthly category orders, product-order prices, allocation shares, seasonality, and the launch date. Monthly calculations translate those assumptions into the five materials sales streams.


The Construction Materials Financial Model is an Excel template for planning contractor-account sales, purchased-material costs, yard expenses, staffing, and financial projections for a regional building-materials distributor. It converts editable monthly operating assumptions into annual revenue, EBITDA, and supporting financial reports.
The included planning case represents an owner-operated materials yard near Columbus, Ohio, with an 8,000-square-foot leased covered warehouse, outdoor aggregate bins, and outsourced customer hauling. The business purchases and resells materials; it does not manufacture products or provide installation.
The workbook connects sales drivers, monthly calculations, operating costs, funding inputs, and management reports.
Adjust active contractor accounts, monthly category orders, product-order prices, allocation shares, seasonality, and the launch date. Monthly calculations translate those assumptions into the five materials sales streams.
Set purchased-goods and hauling rates, variable selling costs, fixed yard spending, and staffing by role. Personnel costs have a separate salary schedule to avoid counting base pay in other expense categories.
Review model settings, working-capital days, and Low, Base, or High operating multipliers. Dashboard financing controls feed the Debt schedule if facilities are entered; no financing facility is assumed in the provided planning case.
The workbook also provides Income Statement, Cash Flow, Balance Sheet, Summary, Sources & Uses, Returns, Valuation, charts, benchmarking, and reconciliation reports. Their calculations depend on the assumptions entered, not on guaranteed business results.
Revenue is driven by active contractor accounts, monthly orders, seasonal demand, each category’s share, and its order price.
The model starts with 80 active accounts in 2026 and rises to 125 in 2030. Orders per account per month increase from 3 to 3.2 over the forecast. These are assumed category orders, not separate full-volume orders for every material.
Cement, sand, and gravel each receive 20% of order count; steel rebar receives 25%; concrete masonry blocks receive the remaining 15%. The per-order prices are $650, $750, $850, $1,600, and $1,100 respectively.
The Revenue Forecast organizes the five material categories, active-account counts, order frequency, price per category order, and allocation shares. The Calc worksheet then applies the same launch flag and seasonal pattern to each category before consolidating monthly sales.

80 active accounts × 3 orders per account per month × 12 normalized seasonal months × $1,015 weighted order price = $2,923,200 annual revenue.
The January-through-December seasonal multipliers total 12, so they shift sales between months without changing the annual baseline. The single January 31, 2026 launch-date control applies across all categories. Change account demand, category mix, prices, or seasonality to test the revenue outlook.
The forecast separates resale costs, revenue-linked expenses, monthly overhead, and fixed-base personnel costs.
Purchased materials equal 72% of revenue, while outsourced hauling adds 4%; together these form 76% direct COGS. Payment processing at 0.8%, trade-credit losses at 0.5%, and pallet protection at 0.7% add 2% in variable operating expenses.
Fixed costs cover warehouse and yard occupancy, utilities, insurance, equipment maintenance, software, accounting, marketing, security, and waste service. The occupancy example is $7,500 monthly for 12 paid months; total modeled fixed spending is $162,600 annually.
The COGS and Operating Expenses forecast separates direct resale materials and hauling from revenue-linked charges and recurring yard overhead. Its monthly expense schedules let buyers trace how different sales volumes and spending assumptions change operating margins.

Payroll separately includes one owner general manager at $75,000 annual base pay, a yard and warehouse team at $45,000 per FTE, and counter sales and dispatch at $55,000 per FTE. Annual-average staffing expands as contractor demand grows.
The Payroll Forecast schedules staff by role and full-time-equivalent assumptions, with hiring dates and compensation controls. For this case, fixed-base payroll rises from $220,000 in 2026 to $292,500 in 2030 as yard and dispatch coverage expands.

Startup purchases, separate opening cash outlays, working capital, and owner contributions are modeled apart from annual EBITDA.
The selected startup assets total $93,000: $40,000 for a forklift and attachments, $25,000 for racks and aggregate bins, $20,000 for yard improvements and security, and $8,000 for office and sales equipment. Lease security, permits, professional fees, and preopening setup are separate cash items.
The Capital Expenditure Plan identifies asset purchases, planned dates, and depreciation treatment for investments such as forklift equipment, yard improvements, and office assets. Those capital outlays are not simply deducted from the operating EBITDA forecast.

The planning inputs specify 21 receivable days, 23 payable days, and 33 inventory days. These controls influence working-capital timing and are important when contractor credit terms and purchased stock absorb cash before invoices are collected.
The Sources and Uses of Funds report traces funding sources and cash allocations, including operations, investments, financing transactions, and cash retained. The planning case identifies $1,015,288 of initial owner funding; that input is not revenue or a measure of operating profitability.

The initial funding estimate incorporates qualifying assets, other opening cash, opening net working capital, and a three-month reserve, net of confirmed non-owner funding. It is a selected funding assumption, not proof that future cash balances will remain sufficient.
The selected Columbus-area planning case projects higher sales volume while retaining material-cost and other operating-expense assumptions.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $2,923,200 | $2,662,696 | $260,504 |
| 2027 | $3,471,300 | $3,090,214 | $381,086 |
| 2028 | $3,964,590 | $3,511,230 | $453,360 |
| 2029 | $4,482,240 | $3,951,247 | $530,993 |
| 2030 | $4,872,000 | $4,255,260 | $616,740 |
Illustrative estimates, not observed results. 2028 and 2029 amounts are rounded to whole dollars.
For 2026, $2,923,200 revenue less $2,662,696 in modeled operating expenses produces $260,504 EBITDA. In 2030, the case reaches $4,872,000 revenue and $616,740 EBITDA. Rising account counts and order frequency are key drivers; these outputs depend on the entered assumptions.
The Income Statement can extend the workbook calculations beyond EBITDA, and the Summary consolidates the financial reports. The supplied business-case evidence, however, documents results only through EBITDA; it does not establish net profit, debt-service coverage, or cash balances.
The Cash Flow Forecast reports operating, investing, and financing cash movements and reconciles opening with closing cash. It helps examine the timing differences between contractor sales, customer collections, inventory purchases, yard assets, and owner or debt financing.

The supporting analysis tools help test operational thresholds, investment timing, and changes to the materials-yard plan.
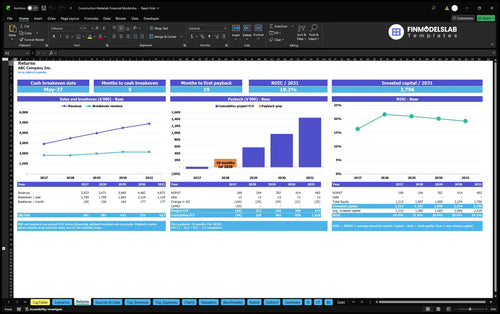
The Returns report distinguishes the sales level needed to cover operating costs from cash break-even, when cumulative project cash flows reach the relevant threshold. Investment payback measures recovery of the initial outlay; annual ROIC compares modeled operating returns with invested capital.
The Returns analysis presents sales break-even, cash break-even timing, investment payback, and return on invested capital as different performance tests. The provided case supplies no verified payback date or ROIC figure, so these must be reviewed after setting the relevant assumptions.
The Low, Base, and High scenario controls can vary revenue, COGS, variable expenses, fixed expenses, and payroll. This is useful for testing slower contractor acquisition, thinner resale margins, higher occupancy costs, or more staffing, without treating any alternative as a historical outcome.
The Financial Scenario Analysis compares Low, Base, and High projections for revenue, gross margin, contribution margin, and EBITDA. Changing those multipliers helps evaluate how sensitive the distribution yard is to sales volume and its materials and operating cost structure.

The workbook also includes valuation, benchmarks, ratios, and model checks for broader evaluation. Those reports are analytical functions; this case does not supply an established business valuation, approved borrowing amount, or industry benchmark result.
Answers to common questions about the workbook’s inputs, financial projections, and scope.
It models a regional contractor-focused materials yard that resells cement, sand, gravel, rebar, and masonry blocks, with outsourced delivery rather than manufacturing or installation.
Yes. Edit active accounts, orders per account, order-share allocation, product prices, seasonal factors, and the launch date to revise the revenue forecast.
No. Fixed-base staff salaries are calculated separately in Payroll and are excluded from the documented direct, variable, and fixed operating expense categories.
Yes. The standard workbook includes projected Income Statement, Cash Flow, and Balance Sheet reports, although the supplied illustrative business-case figures only establish results through EBITDA.
Yes. The Dashboard includes accounts-receivable, accounts-payable, and inventory-day controls that support working-capital and cash-flow analysis.
No. Cash availability also depends on customer collections, inventory, supplier payments, capital expenditure, and financing, which require separate cash-flow review.
No. Returns and Valuation are workbook analysis functions, and their outputs depend on the entered assumptions; the supplied case provides no verified payback or valuation result.

KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.

DCF valuation and sensitivity analysis.

Largest costs and spending trends.

Annual and monthly financial performance.
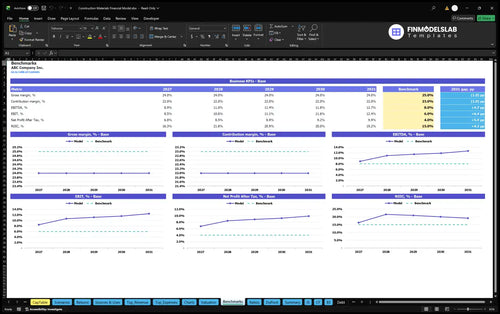
Compare margins and returns to benchmarks.

This template made our margins and break-even point easy to see, so we stopped guessing at pricing. It saved me about 6 hours I’d normally spend rebuilding the math in Excel.

I finally had the right structure for our investor deck instead of piecing it together from old files. We booked a planning call the same day because the outputs were clear and complete.
Having the statements and charts in one model cleaned up a mess that used to live across three spreadsheets. I cut reporting prep by 8 hours and could send one file instead of chasing versions.