

Revenue & Calc
Set launch timing, available craft hours and billable utilization, then allocate sold hours across five services. Monthly calculations apply each fiscal year’s realized prices and consolidate revenue.


The Furniture Refinishing Financial Model is an Excel template for an owner-managed, two-person workshop in Austin, Texas. It turns available craft hours, billable utilization, service mix and realized hourly prices into financial projections for 2026–2030.
The illustrated 1,125-square-foot workshop strips, sands and refinishes customer-owned wood furniture. Its operating forecast runs through EBITDA; furniture resale and upholstery manufacturing are outside the case.
Edit workshop capacity, utilization, service prices, costs, staffing and funding assumptions to evaluate your own operating plan.
Set launch timing, available craft hours and billable utilization, then allocate sold hours across five services. Monthly calculations apply each fiscal year’s realized prices and consolidate revenue.
Separate revenue-linked costs, monthly overhead, fixed salaries and equipment spending. This keeps workshop staffing distinct from consumables, delivery charges and startup assets.
Compare Low, Base and High multipliers for revenue and cost categories. Review the declared financial statements and Returns reports for their respective purposes; case results below establish revenue, operating expenses and EBITDA.
One shared pool of 320 available craft hours per month supplies all five furniture work categories.
Billable utilization rises from 55% in 2026 to 74% in 2030, increasing monthly sold hours from 176 to 236.8. Each sold hour is allocated once; piece quotes reflect the hours required, without a separate customer, order or project forecast.
The launch date is January 31, 2026, and the model assigns a full normal earned-work month to January. Revenue is zero before launch; this timing convention matters when adapting the template to a different opening date.
The Revenue Forecast links workshop capacity, utilization, service mix and realized hourly prices to sales. Edit these drivers to assess whether higher billable use or different quoted rates supports the revenue you need.
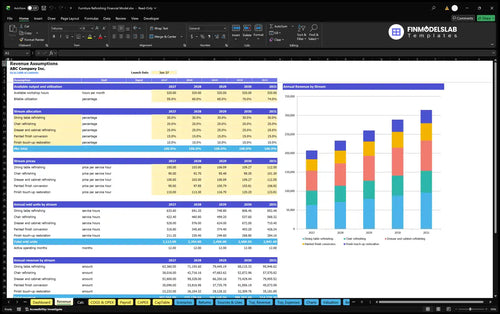
| Work category | Hour share | 2026 / hour | 2030 / hour |
|---|---|---|---|
| Dining table refinishing | 30% | $100.00 | $112.55 |
| Chair refinishing | 20% | $90.00 | $101.30 |
| Dresser and cabinet refinishing | 25% | $100.00 | $112.55 |
| Painted finish conversion | 15% | $95.00 | $106.92 |
| Finish touch-up restoration | 10% | $110.00 | $123.81 |
Shares total 100%; the final category is the residual allocation. Prices and utilization are estimated planning inputs.
320 hours/month × 55% utilization × $98.25 weighted price/hour × 12 months = $207,504 annual revenue.
Revenue-linked costs move with sales, while fixed overhead and base salaries create operating commitments.
The COGS & Operating Expense Forecast separates direct, variable and fixed costs. Finishes, abrasives and repair supplies consume 10% of revenue, with external collection and delivery at 3.5%.
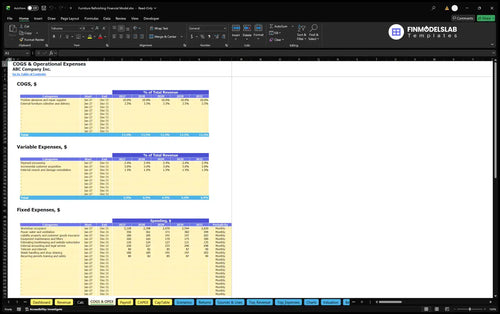
Variable expenses add payment processing at 2.4%, incremental customer acquisition at 3%, and external rework or damage remediation at 1.5% of revenue. Fixed costs cover occupancy, utilities, ventilation, insurance, equipment upkeep, subscriptions, professional services, telecom, waste handling and recurring safety requirements.
Workshop occupancy starts at $2,328 per month for 12 paid months. Total fixed operating expenses rise from $44,376 in 2026 to $49,945 in 2030, separately from payroll.
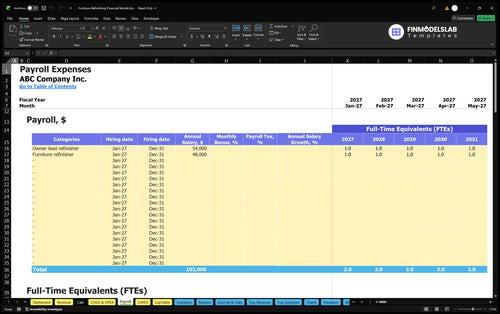
The Payroll Forecast organizes staffing and fixed base compensation by role. This case includes one owner lead refinisher at $54,000 annually and one furniture refinisher at $48,000, totaling $102,000 each forecast year.
The case estimates $85,538 of initial owner funding across assets, prelaunch cash, working capital and a reserve.
The funding build includes $27,500 of startup assets, $9,156 of separate prelaunch cash, $1,706 of opening net working capital and one $47,177 three-month reserve. These rounded components may differ from the rounded funding total by a dollar.
The Capital Expenditure Plan schedules asset spending and depreciation. Startup assets comprise $14,000 of installed finishing ventilation and enclosure, $8,000 of sanding, extraction and spray equipment, $4,000 of benches, clamps and drying racks, and $1,500 of computer and POS equipment.
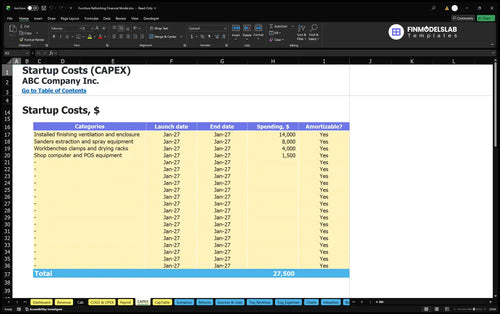
Separate opening cash items cover a refundable workshop deposit, formation and safety setup, website photography and opening marketing. Working-capital controls use zero receivable days, zero payable days and 22 inventory days.
Sources and Uses of Funds reconciles funding sources and cash allocation over a selected period. Use it to review owner contributions, operating payments and investment spending; the stated reserve is an estimated funding input, not evidence of tested cash sufficiency.
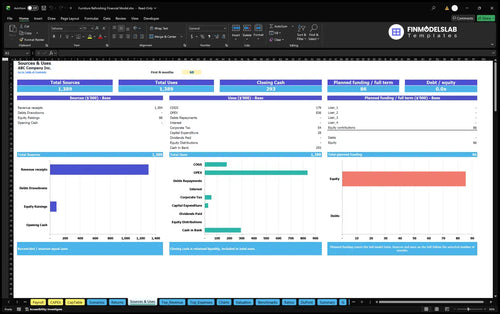
Higher utilization and realized prices increase revenue while annual base payroll remains at $102,000.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $207,504 | $188,707 | $18,797 |
| 2027 | $233,159 | $195,272 | $37,887 |
| 2028 | $260,168 | $202,153 | $58,015 |
| 2029 | $288,584 | $209,362 | $79,222 |
| 2030 | $314,228 | $216,048 | $98,180 |
Forecasts, not historical results or industry averages. Whole-dollar rounding can create small differences between displayed totals.
Operating expenses include COGS, variable expenses, fixed overhead and Payroll. EBITDA rises from $18,797 in 2026 to $98,180 in 2030; these results exclude depreciation, interest and income taxes and do not establish net profit or cash generation.
The Cash Flow Forecast separates operating, investing and financing cash movements and reconciles opening with closing cash. Review it alongside IS and BS to evaluate liquidity after entering funding, working-capital and investment assumptions; no cash-flow result is established by the EBITDA table.
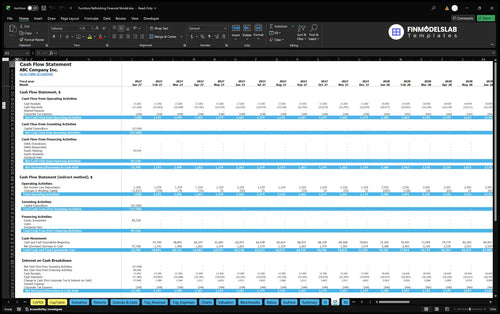
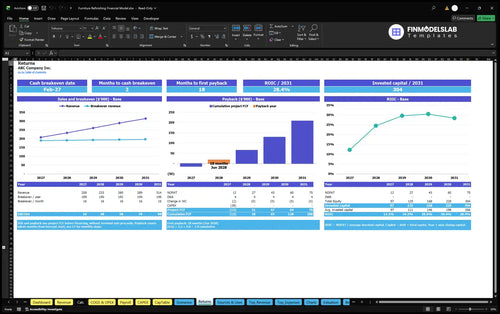
The declared Returns report supports distinct operating, cash and investment questions.
Sales break-even compares revenue with operating cost coverage. Cash break-even concerns cash coverage, while investment payback tracks recovery of invested funds; annual ROIC relates operating returns to invested capital.
Return on Invested Capital Analysis brings the Returns report’s break-even, project cash-flow, payback and annual ROIC measures together. Use these outputs to evaluate funding and operating choices after completing the relevant inputs; the supplied case establishes no payback date or ROIC percentage.
Dashboard Debt Controls feed the Debt repayment schedules when financing assumptions are entered. Owner funding is equity rather than sales revenue, and this case does not establish a borrowing amount, interest rate or debt-service outcome.
The capacity-based structure suits workshops that estimate and sell refinishing labor through piece quotes.
Adapt available hours, billable utilization and service mix to your workshop before relying on the projections. All selected inputs are estimates; the Austin case does not independently verify your local prices, wages, occupancy costs or cash requirements.
Use these answers to check the template’s operating assumptions and reporting scope.
No; revenue comes from service hours spent refinishing customer-owned furniture, allocated across five work categories and multiplied by their realized hourly prices.
Yes; edit the documented capacity, utilization, service mix and annual realized prices to build a different operating forecast.
Yes; Payroll includes $54,000 of annual owner base pay and $48,000 for the furniture refinisher, with salaries excluded from other expense categories.
No; the January 31, 2026 launch receives a full normal earned-work month under the documented model convention.
No; initial owner funding finances startup assets, separate opening cash, working capital and a reserve, while annual operating expenses are reported separately.
No; assess working capital, capital spending, financing and cash balances through the relevant reports, because EBITDA alone does not establish liquidity, payback or net profit.
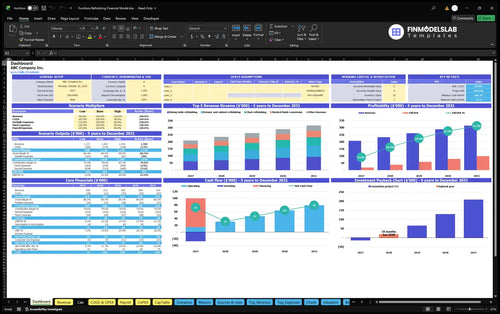
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
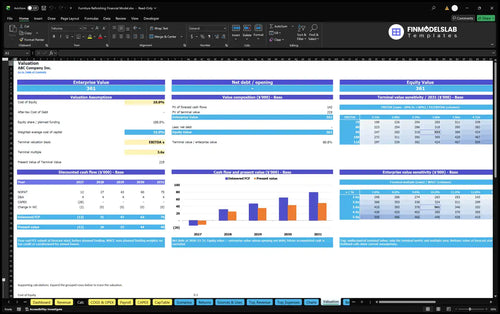
DCF valuation and sensitivity analysis.
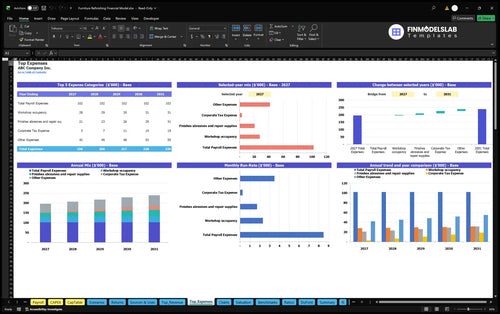
Largest costs and spending trends.
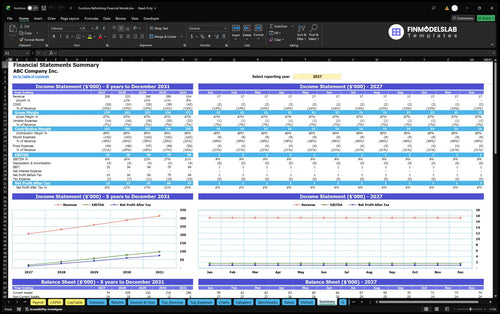
Annual and monthly financial performance.
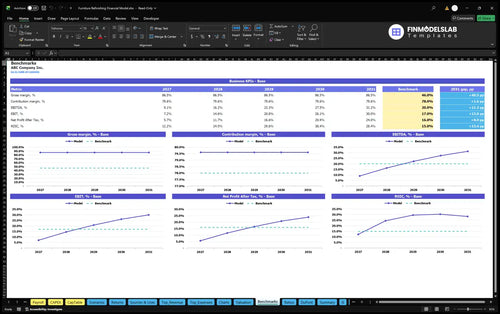
Compare margins and returns to benchmarks.

I stopped wasting time on low, base, and high case drafts and got one clean model instead. It saved me hours and made the assumptions easy to compare.
The cash flow tab made it much easier to see when we’d run short and how long the runway really was. That let me plan funding conversations sooner and avoid guessing.

Pricing, costs, and growth were all in one place, so I wasn’t hunting through messy tabs anymore. I cleaned up the model in under an hour and could explain every input clearly.