

Revenue & Calculations
Revenue and Calc organize the demand inputs, launch timing, monthly purchasing visits, units per visit, category allocation, realized prices, seasonality, and resulting sales by product category.


This Liquor Store Financial Model is an Excel template for an independent off-premise neighborhood store. It converts purchasing visits, items per visit, category mix, selling prices, operating costs, staffing, startup investment, and working-capital assumptions into monthly and annual financial projections.
The illustrated case represents an estimated 2,000 sq ft suburban Illinois store with consumer checkout only, no wholesale or delivery, and a January 31, 2026 launch date. The operating forecast runs through EBITDA; the example results are planning projections rather than observed industry performance.
The workbook links operating assumptions to monthly calculations, financial statements, funding schedules, management reports, and model checks.
Revenue and Calc organize the demand inputs, launch timing, monthly purchasing visits, units per visit, category allocation, realized prices, seasonality, and resulting sales by product category.
COGS & OPEX separates merchandise and stock-related direct costs from variable and fixed operating expenses, while Payroll models the Store Manager, Sales Associates, and Stock Associate separately.
CAPEX, CapTable, Debt, Sources & Uses, and Cash Flow connect startup assets, equity contributions, optional financing, investment spending, and liquidity without treating startup funding as operating profit.
Income Statement, Balance Sheet, Cash Flow, Summary, Scenarios, Returns, Valuation, Ratios, DuPont, Charts, Top_Revenue, Top_Expenses, Benchmarks, and Checks support financial review and model reconciliation.
Revenue is demand-based: purchasing visits generate sale units, then one shared unit pool is allocated across six mutually exclusive bottle or pack categories.
For each month, the model multiplies purchasing visits per open day by 30 open days and 1.35 sale units per visit, then applies the repeating monthly demand factor. The resulting units are distributed across Whiskey and Bourbon, Vodka Gin and Rum, Tequila and Agave, Still Wine, Sparkling Wine, and Beer and Cider.
Each category then applies its own annual net selling price. The base mix totals 100%: 22%, 20%, 12%, 25%, 6%, and 15%, so the same sold unit is never counted in more than one revenue stream.
The Revenue Forecast shows the operating drivers, monthly unit volume, category allocation, selling prices, and resulting sales. It lets a user trace changes in store traffic or basket size through to projected revenue by stream.
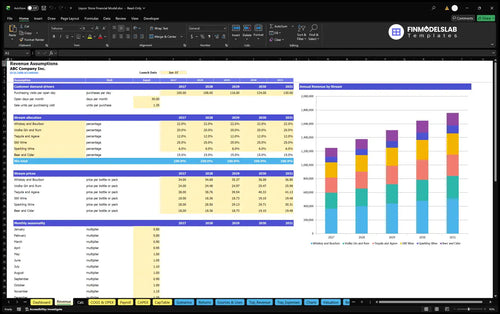
100 purchasing visits/day × 30 open days/month × 1.35 units/visit = 4,050 sale units/month before the repeating monthly factor.
The model separates merchandise COGS, variable operating expenses, fixed overhead, and payroll so each cost is counted once.
The COGS & Operating Expense Forecast separates merchandise purchases, stock breakage and obsolescence, inbound freight, card processing, checkout supplies, and fixed store overhead. These assumptions feed monthly expenses and operating margins without including salaried staff twice.
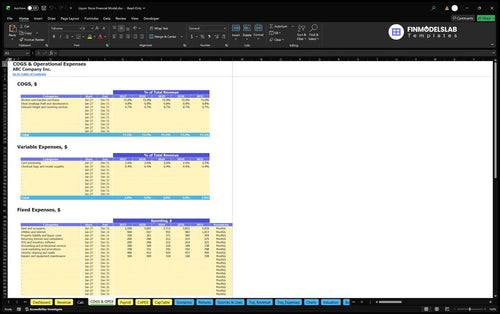
Direct COGS uses 72% of revenue for alcohol merchandise purchases, 0.8% for stock breakage, theft and obsolescence, and 0.7% for inbound freight and receiving. Variable expenses include card processing plus 0.4% of revenue for checkout bags and receipt supplies.
Fixed operating coverage includes rent and occupancy, utilities and internet, insurance, recurring licenses and compliance, POS and inventory software, accounting, local marketing, security, cleaning, waste, repairs, and equipment maintenance. Rent begins at $3,500 per month in 2026.
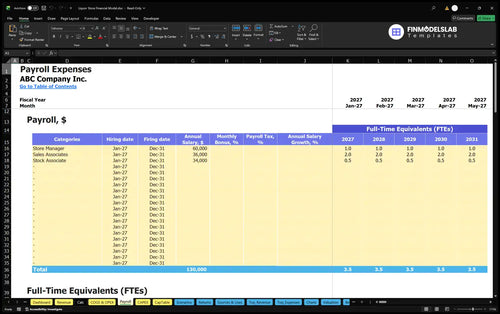
The Payroll Forecast shows staffing FTE and fixed base pay by role. The illustrated plan uses one Store Manager, two Sales Associates, and 0.5 Stock Associate FTE, producing $149,000 of annual base payroll in each forecast year.
Startup assets, opening cash needs, inventory, and owner funding are modeled separately from annual operating expenses and EBITDA.
The Capital Expenditure Plan records durable startup assets and their timing, including leasehold fit-out, shelving and displays, refrigeration, POS and ID-check hardware, security equipment, safe, and exterior signage. Depreciable purchases can then flow into the asset schedule.
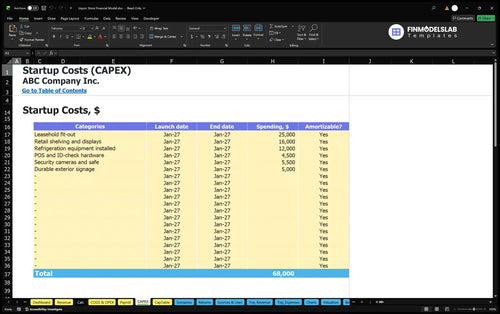
The documented startup assets include $25,000 of leasehold fit-out, $16,000 of retail shelving and displays, $12,000 of installed refrigeration, and $4,500 of POS and ID-check hardware. Other opening cash items include deposits, permits, prelaunch marketing, preopening payroll and training, and preopening utilities.
Initial owner funding is estimated at $538,878. That amount includes durable assets, one-time prelaunch cash, opening stock, and a three-month reserve of gross cash operating outflows; it is a planning funding input, not a demonstrated peak cash requirement.
The Sources and Uses of Funds report reconciles planned funding sources with operating, investing, and financing uses of cash. It helps distinguish owner equity or debt funding from revenue receipts and from the cash retained in the business.
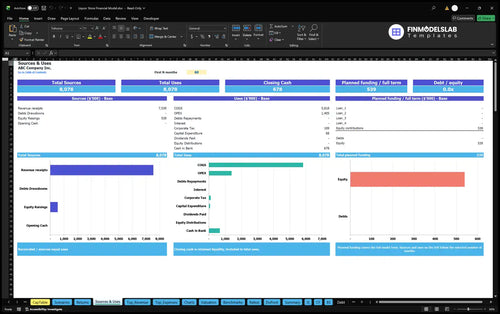
The illustrated base case grows revenue and EBITDA from 2026 through 2030 while keeping the example focused on operating performance rather than promising realized results.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $1,249,992 | $1,187,159 | $62,833 |
| 2027 | $1,376,991 | $1,286,651 | $90,340 |
| 2028 | $1,508,570 | $1,389,703 | $118,867 |
| 2029 | $1,644,861 | $1,496,418 | $148,444 |
| 2030 | $1,758,942 | $1,586,214 | $172,727 |
Illustrative model outputs rounded to whole dollars; totals may differ slightly from displayed arithmetic because the workbook retains underlying precision.
In the example case, purchasing visits per open day rise from 100 in 2026 to 130 in 2030 while category selling prices also increase. The model then carries those revenue changes through COGS, variable expenses, fixed costs, and payroll to calculate EBITDA.
EBITDA is an operating measure and does not establish net profit or cash sufficiency. The full workbook also includes depreciation, financing, tax, working-capital, balance-sheet, and cash-flow schedules for broader financial analysis.
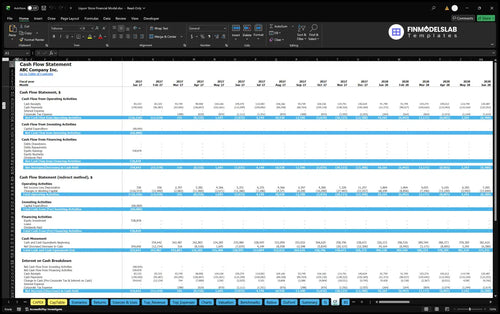
The Cash Flow Forecast shows monthly operating, investing, and financing cash movements together with opening and closing cash reconciliation. It is the report to review when evaluating liquidity, funding timing, investment spending, and debt or equity cash flows.
The Returns report keeps operating break-even, cash break-even, investment payback, and annual ROIC as separate measures instead of treating them as interchangeable.
The Return on Invested Capital Analysis combines sales break-even, cash break-even timing, investment payback, project cash flows, invested capital, and annual ROIC. It helps compare operating coverage with the separate question of when invested funds may be recovered.

Sales break-even compares revenue with the level needed to cover operating costs, while cash break-even considers cash movement and timing. Investment payback tracks cumulative project cash flow, and ROIC relates operating returns to invested capital.
No payback month, ROIC percentage, IRR, or valuation amount is inferred here because those values are not supplied in the documented example outputs. Users can instead adjust operating and financing assumptions and review the calculated reports in the workbook.
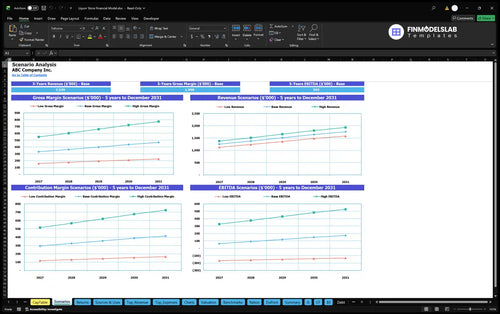
The Financial Scenario Analysis compares Low, Base, and High cases for revenue, gross margin, contribution margin, and EBITDA. Dashboard multipliers can change revenue, COGS, variable expenses, fixed expenses, and payroll to test operating sensitivity.
These answers summarize the model scope, editable assumptions, calculations, and reports.
It multiplies purchasing visits, open days, units per visit, monthly seasonality, category mix, and category selling prices to calculate monthly and annual revenue.
Yes. The six category shares and annual net selling prices are operating inputs, so you can replace the illustrated assumptions with your own planned mix and pricing.
Yes. Store Manager, Sales Associates, and Stock Associate staffing are modeled in Payroll and excluded from the listed COGS, variable, and fixed expense inputs.
Yes. Startup assets, preopening cash items, opening stock, working-capital assumptions, and owner funding are modeled separately from recurring operating expenses.
The workbook includes projected Income Statement, Cash Flow Statement, Balance Sheet, Summary, and supporting schedules, plus management and analysis reports.
No. EBITDA measures operating earnings before depreciation, interest, and tax; liquidity and financing effects are evaluated in the Cash Flow and other financial statements.
Yes. Dashboard Scenario Controls provide Low, Base, and High multipliers for revenue, COGS, variable expenses, fixed expenses, and payroll.
No. The outputs are illustrative projections based on user inputs, and the documented owner funding amount is not presented as a tested peak cash requirement.
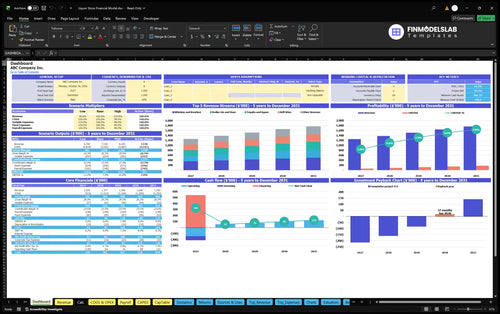
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
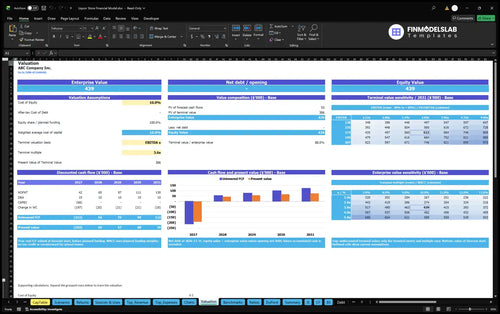
DCF valuation and sensitivity analysis.
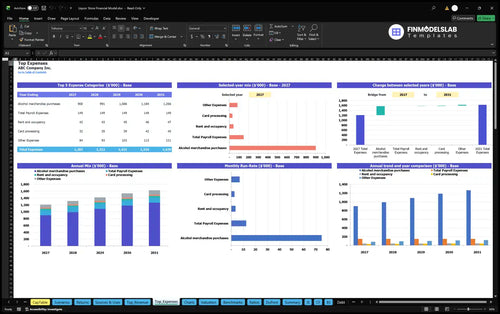
Largest costs and spending trends.
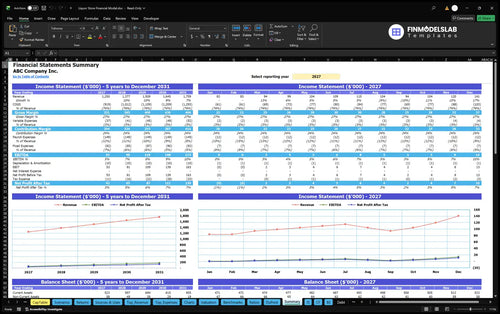
Annual and monthly financial performance.
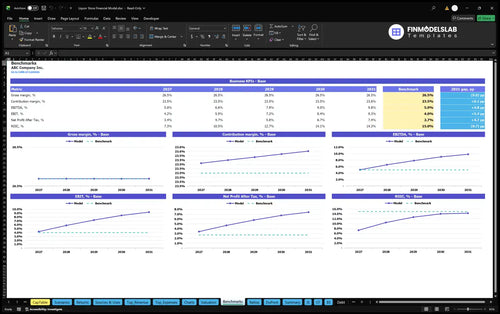
Compare margins and returns to benchmarks.

This template kept one bad input from rippling through the whole model, so I caught mistakes before they hit my lender deck. It saved me about 3 hours of cleanup.
I could switch between low, base, and high cases without rebuilding tabs, which made pricing and margin planning much easier. What used to take half a day now takes 20 minutes.

The monthly cash-flow view made it clear when shortfalls could happen, so I booked my financing meeting with better timing. It gave me a runway readout I could actually trust.