

Revenue & Calc
Set qualified website sessions, checkout conversion, the nonrefunded share, launch timing, five course prices, and purchase mix. Calc converts the single demand pool into mutually exclusive monthly orders and sales by course.


The Online Course Financial Model is an Excel template for planning monthly checkouts, course-level revenue, operating costs, staffing, and opening funding for a small U.S. publisher of self-paced business-skills courses. Editable assumptions feed monthly financial projections and reports across 2026 through 2030.
The documented case uses direct, prepaid single-course sales from one website audience, without subscriptions or enterprise invoices. The January 31, 2026 launch date activates the full launch month; amounts are in U.S. dollars, and all five years are illustrative forecasts rather than historical actuals.
Connected worksheets take course demand and expense assumptions through monthly calculations, financial statements, and decision reports.
Set qualified website sessions, checkout conversion, the nonrefunded share, launch timing, five course prices, and purchase mix. Calc converts the single demand pool into mutually exclusive monthly orders and sales by course.
Set content licensing, payment processing, acquisition and affiliate marketing, fraud losses, and monthly overhead. Expense effective dates, rates, and payment frequencies feed the operating forecast.
Adjust staffing by role, annual base pay, hiring dates, and asset purchases. Payroll builds personnel costs while CAPEX schedules equipment spending and depreciation separately.
Enter equity in CapTable and potential borrowing through Dashboard Debt Controls. The Income Statement, Cash Flow, Balance Sheet, Sources & Uses, and Checks connect profitability, funding, liquidity, and reconciliations.
Review the Dashboard, Summary, Low/Base/High comparisons, Returns, Valuation, Benchmarks, Ratios, and revenue and expense composition. These reports draw on the supporting schedules, not separately assumed performance figures.
A single website-demand pool is converted into nonrefunded paid purchases and allocated across five exclusive course offerings.
In the example, qualified monthly sessions grow from 12,000 in 2026 to 26,000 in 2030; paid conversion rises from 1.5% to 1.8%, while the nonrefunded purchase share stays at 95%. Volume follows demand rather than classroom seats or instructor capacity.
Each checkout purchases one course only. You can change individual prices and topic allocation; the selected 30%, 25%, 20%, and 15% shares leave a calculated 10% residual for business writing.
The Revenue Forecast organizes qualified sessions, conversion, refunds, course mix, prices, and launch timing, while Calc computes each course’s monthly revenue. Compare traffic growth, checkout performance, and pricing before changing the marketing plan.
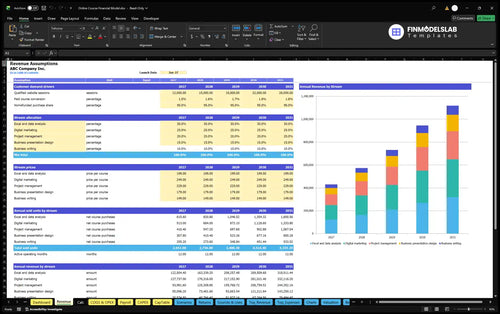
| Course | Share of orders | Price per course |
|---|---|---|
| Excel and data analysis | 30% | $199 |
| Digital marketing | 25% | $249 |
| Project management | 20% | $229 |
| Business presentation design | 15% | $179 |
| Business writing | 10% residual | $149 |
Shares total 100% of nonrefunded purchases; the example weighted course price is $209.50.
12,000 monthly sessions × 1.5% paid conversion × 95% nonrefunded × $209.50 weighted course price × 12 months = $429,894.
Content licensing, selling costs, monthly overhead, and role-based salaries are modeled separately and combined to calculate operating EBITDA.
Licensed learning content is direct COGS at 6% of revenue. Separately, variable expenses total 28.5%: payment processing at 3.3%, acquisition and affiliate marketing at 25%, and chargebacks and fraud at 0.2%.
The COGS and Operating Expenses forecast separates content licensing, revenue-linked selling costs, and monthly fixed overhead. It lets you evaluate gross margin and contribution after marketing without including salaries in those expense groups.
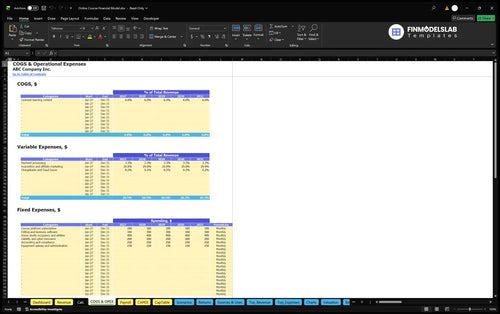
Selected fixed costs total $17,868 annually and cover the course platform, editing software, home studio occupancy, insurance, accounting, and equipment upkeep. The course platform alone is budgeted at $189 per month for 12 paid months.
The Payroll Forecast plans annual-average FTE and fixed base salary for the publisher, instructional designer and editor, and learner support coordinator. Salary costs enter Payroll once, rather than being duplicated in direct, variable, or fixed expense inputs.
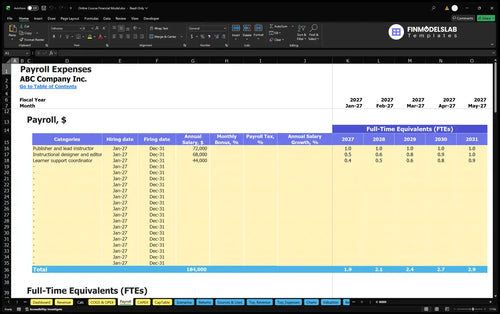
The publisher remains at 1.0 FTE with $72,000 base pay. Instructional design increases from 0.5 to 1.0 FTE, while learner support rises from 0.4 to 0.9 FTE by 2030; this case excludes employer taxes, benefits, and personal taxes.
1 × $72,000 publisher + 0.5 × $68,000 design/editor + 0.4 × $44,000 support = $123,600.
Equipment purchases, distinct preopening cash items, working-capital assumptions, and owner contributions are kept separate from annual operating expenses.
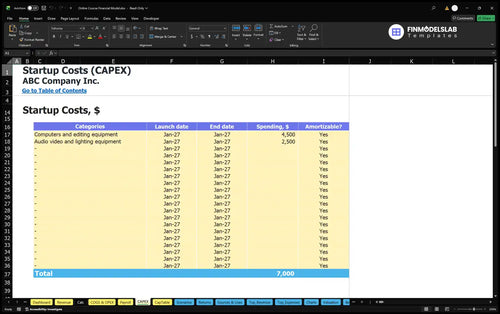
Opening equipment includes $4,500 of computers and editing gear plus $2,500 of audio, video, and lighting equipment. Separate preopening cash items include curriculum and recording labor, website setup and launch media, and registration and intellectual-property legal work.
The Capital Expenditure Plan tracks dated equipment purchases and applicable depreciation. It distinguishes initial studio assets from repeat monthly operating charges, so investing cash requirements are not mistaken for the EBITDA expense forecast.
For this prepaid digital-sales case, accounts receivable, accounts payable, and inventory days are all set to zero. These remain editable working-capital controls, not evidence that monthly cash balances will always be sufficient.
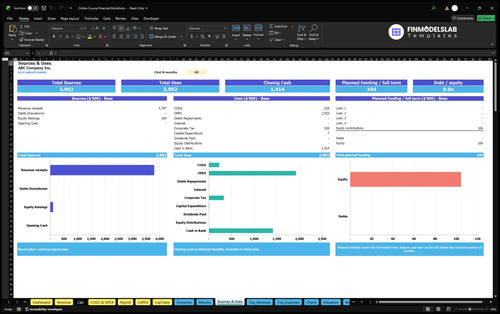
The Sources and Uses of Funds report reconciles funding and cash allocation across operating, investing, and financing activities. The selected $104,445 initial owner contribution covers equipment, separate preopening payments, and an estimated three-month reserve, with no committed funding from other sources.
The selected 2026–2030 demand, cost, and staffing assumptions produce the following annual operating forecast in U.S. dollars.
| Year | Revenue | Operating expenses | EBITDA |
|---|---|---|---|
| 2026 | $429,894 | $289,781 | $140,113 |
| 2027 | $573,192 | $350,419 | $222,773 |
| 2028 | $730,820 | $419,401 | $311,419 |
| 2029 | $945,767 | $510,358 | $435,409 |
| 2030 | $1,117,724 | $583,083 | $534,641 |
Selected scenario only; displayed figures are rounded to whole dollars and may not subtract exactly.
In the illustrative case, revenue rises from $429,894 in 2026 to $1,117,724 in 2030, while annual operating expenses increase from $289,781 to $583,083. EBITDA consequently increases from $140,113 to $534,641 before depreciation, interest, or tax.
These are calculated planning scenarios, not actual sales, sector benchmarks, or a performance guarantee. The documented operating illustration ends at EBITDA even though the workbook also includes broader financial-statement, financing, and cash-flow schedules.
The Cash Flow Forecast separates operating receipts and payments from investment, financing, and changes in cash balances. Use it with the Income Statement to review liquidity, since positive EBITDA and prepaid customer checkouts do not establish cash sufficiency.
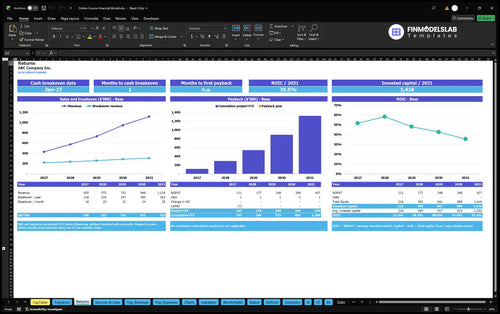
The Returns reports distinguish sales break-even, cash break-even, project investment payback, and annual return on invested capital.
Sales break-even compares revenue with operating cost requirements; cash break-even looks at cash coverage. Investment payback tracks cumulative project cash flow, while annual ROIC relates returns to invested capital. None is equivalent to EBITDA or an assumed investor IRR.
The Returns analysis presents operating break-even, cash break-even, investment payback, and annual ROIC from the linked schedules. The supplied illustration does not establish a specific payback month, achieved investor IRR, or investment-return figure.
Dashboard Low, Base, and High multipliers let you stress revenue, COGS, variable expenses, fixed expenses, and payroll; Scenarios compares operating outcomes. Valuation provides discounted cash-flow and terminal-assumption sensitivity, but no valuation amount is established by the supplied operating case.
The template fits a small U.S. publisher selling individual prerecorded business-skills courses directly to consumers.
Use it to assess qualified traffic targets, customer acquisition spending, the timing of learner support hires, and funding for course production and studio equipment. Change the assumptions to reflect your own pricing and audience rather than treating the sample as verified industry demand.
Subscriptions, cohorts, accredited certificates, physical goods, and enterprise invoices are outside this documented course revenue design. Benchmarks compare model ratios against reference values entered in the workbook, not independently verified industry averages.
Answers to common questions about the template’s assumptions, revenue mechanics, outputs, and operating scope.
Yes. Edit each course price, purchase share, qualified sessions, paid conversion, nonrefunded share, and launch timing in Revenue.
No. The documented revenue model uses direct prepaid, single-course checkouts with no subscription renewals, cohort retention, or enterprise billing.
It applies the selected 95% nonrefunded share to converted purchases before distributing net course orders across the five topics.
No. Publisher, instructional design, and learner support base salaries enter through Payroll, separately from COGS, variable expenses, and fixed overhead.
Yes. Income Statement, Cash Flow, Balance Sheet, and Summary reports link to supporting monthly calculations; this brief provides illustrative figures only through EBITDA.
No. EBITDA excludes investing and financing cash flows; consult Cash Flow, Sources & Uses, and Balance Sheet for liquidity analysis.
Yes. Dashboard Low, Base, and High multipliers adjust revenue and cost assumptions, with comparative results in Scenarios.
No. Returns can calculate break-even, payback, and annual ROIC, but the supplied example provides no specific payback date or return.
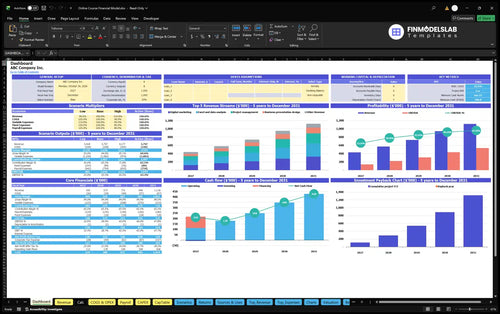
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
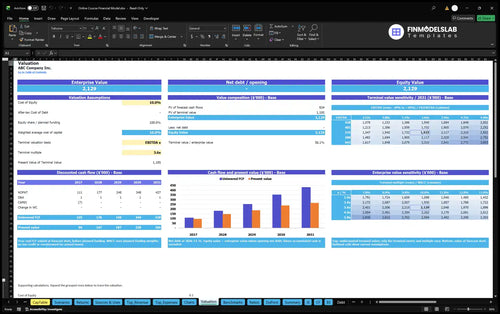
DCF valuation and sensitivity analysis.
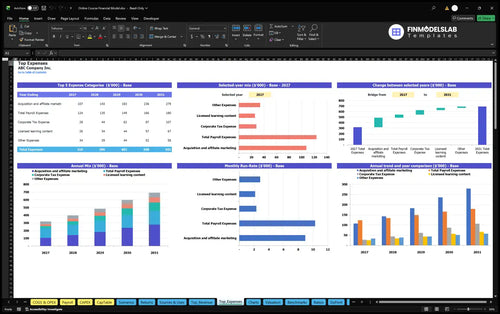
Largest costs and spending trends.
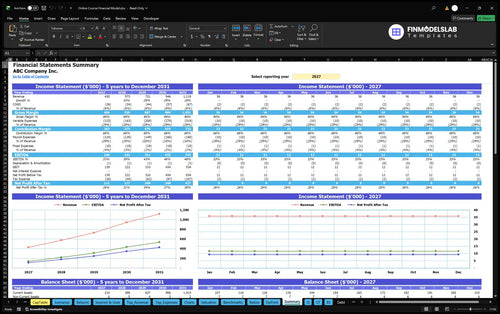
Annual and monthly financial performance.
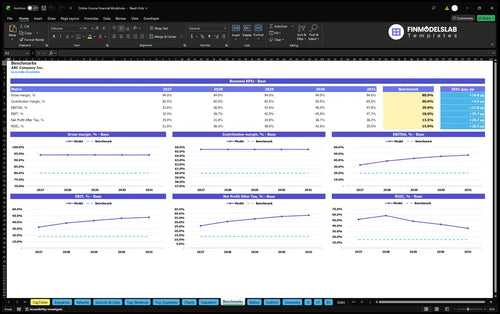
Compare margins and returns to benchmarks.

This template made runway planning much easier. I could see shortfalls months ahead and saved about 6 hours of manual forecasting each week.

I stopped rebuilding low, base, and high cases by hand. The model let me compare assumptions in minutes, and I booked a planning meeting the same day.
All the statements and charts finally live in one file. I cut reporting prep by 4 hours and had a cleaner deck for our next update.