

Revenue and Calc
Set visit capacity, utilization, service shares, prices, and launch timing. Monthly calculations distribute sold appointments once across five treatment lines.


This Physiotherapy Clinic Financial Model is an Excel template for projecting visits, service revenue, expenses, staffing, and EBITDA from 2026 through 2030. It calculates cash-pay outpatient revenue from appointment capacity and utilization, rather than a separate demand estimate.
The illustrative Plano, Texas, clinic occupies 2,000 square feet and employs two salaried physical therapists, including the owner, plus 0.75 administrative FTE. It models individual 60-minute sessions, without insurance billing, group appointments, home visits, or retail.
The workbook connects editable operating inputs with monthly calculations, financial statements, financing schedules, and decision-oriented reports.
Set visit capacity, utilization, service shares, prices, and launch timing. Monthly calculations distribute sold appointments once across five treatment lines.
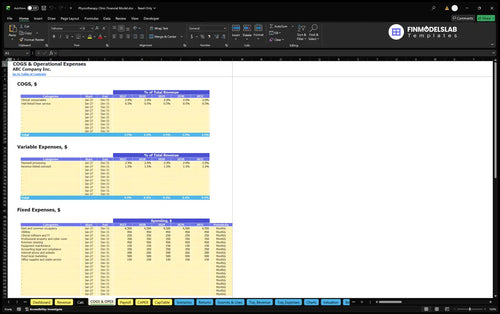
Separate visit-related supplies, payment fees, outreach, premises overhead, and compensation. Clinical and administrative FTE determine personnel costs.
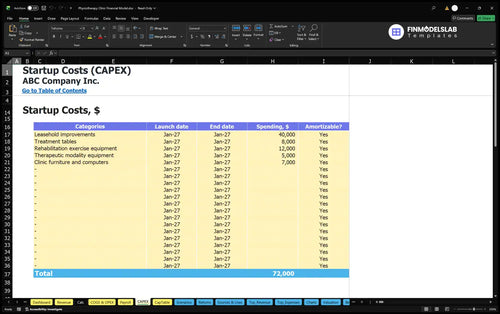
Plan fit-out, equipment, owner contributions, and optional debt separately from operating earnings.
Review financial statements, Dashboard, Scenarios, Returns, Valuation, ratios, charts, and reconciliation checks. Their outputs depend on entered assumptions.
Revenue equals available one-hour appointments multiplied by utilization, then allocated among five exclusive treatments at their respective prices.
The clinic offers 280 appointments monthly: two therapists × seven daily slots × 20 working days. Utilization rises from 50% in 2026 to 65%, 75%, 80%, and 85% in successive years, without material seasonality.
Service shares total 100%: initial evaluations 15%, orthopedic follow-ups 50%, sports rehabilitation 15%, pelvic health therapy 10%, and vestibular rehabilitation 10%. Their prices are $200, $165, $190, $210, and $200 per visit, respectively.
The Revenue Forecast links offered appointment capacity, annual utilization, exclusive service mix, and prices to projected treatment revenue. Changes in one service share require reallocating the same sold-visit pool rather than creating additional visits.
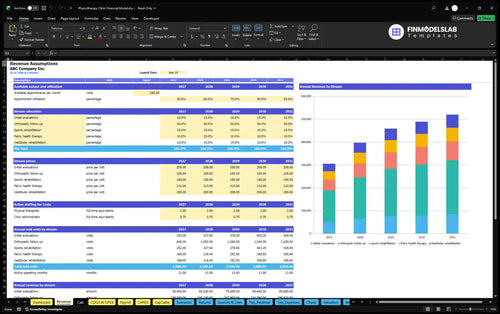
280 monthly slots × 50% utilization × $182 weighted visit price × 12 months = $305,760.
The $182 weighted price reflects the five treatments and their shares. In 2026, 140 monthly appointments are sold, or 1,680 annually; the forecast does not assume full capacity.
The January 31, 2026 launch date is treated as a full launch month, with zero visits before launch and flat nominal prices through 2030.
Direct costs and revenue-linked expenses scale with sales, while premises spending and salaried clinicians create a fixed annual cost base.
Consumables (2%) and linen service (0.5%) create 2.5% direct costs. Payment processing (2.9%) and revenue-linked outreach (1.5%) create 4.4% variable operating expenses.
Fixed costs total $88,200 annually, covering occupancy, utilities, software, insurance, cleaning, maintenance, compliance, communications, local marketing, and supplies. Rent and common occupancy are $4,500 monthly.
The COGS and Operating Expenses forecast separates direct visit costs, revenue-linked charges, and recurring clinic overhead. This helps test how rising appointment utilization changes gross margin, contribution margin, and operating costs without treating salary as COGS.
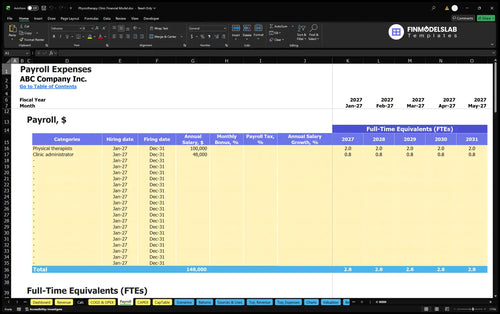
Payroll includes two therapists at $100,000 base pay each and 0.75 administrative FTE at $48,000 per full-time equivalent. Annual salary expense is $236,000, including the clinical owner.
The Payroll Forecast shows therapist and administrator FTE, role-level annual salaries, and the monthly personnel-cost schedule. Adjust staffing or compensation to examine the expense impact of a different clinic operating plan.
Opening assets, preopening cash payments, working-capital settings, and contributed equity are tracked separately from annual operating expenses.
Startup assets include $40,000 in leasehold improvements, $8,000 in treatment tables, $12,000 in rehabilitation equipment, and $5,000 in therapeutic modalities. Furniture and computers are additional assets without stated amounts.
The Capital Expenditure Plan schedules fit-out and equipment purchases and tracks applicable depreciation in the workbook. Initial asset spending is an investing use of funds, not an EBITDA expense at the purchase date.
Separate preopening cash payments include deposits, setup, marketing, occupancy, training, utilities, and website costs. Working-capital settings are zero accounts-receivable days, zero accounts-payable days, and 24 inventory days.
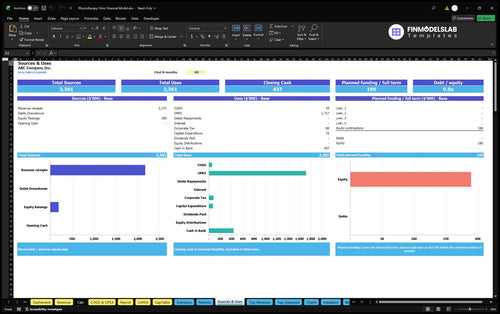
The Sources and Uses of Funds report explains how owner contributions and any configured financing support operating payments, investment, and cash retained in the clinic. It helps compare funding entries with planned allocations, rather than conflating equity with revenue.
The Base case illustrates an initial EBITDA loss as appointment use ramps, followed by positive annual EBITDA from 2027.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $305,760 | $345,297 | -$39,537 |
| 2027 | $397,488 | $351,627 | $45,861 |
| 2028 | $458,640 | $355,846 | $102,794 |
| 2029 | $489,216 | $357,956 | $131,260 |
| 2030 | $519,792 | $360,066 | $159,726 |
Illustrative nominal planning amounts rounded to whole dollars; row subtraction can vary slightly because of rounding.
Low 2026 utilization must cover $236,000 in salaries and $88,200 in fixed costs. At 85% utilization in 2030, revenue reaches $519,792 and EBITDA $159,726 at unchanged treatment prices.
These are illustrative outputs, not observed results or industry averages. EBITDA excludes depreciation, interest, and tax and does not establish net profit, cash on hand, or investment recovery.
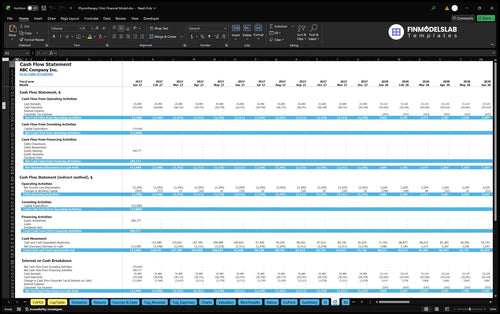
The Cash Flow Forecast tracks operating, investing, and financing cash movements and reconciles opening and closing cash. Inspect it alongside the Balance Sheet for liquidity and working-capital effects that the EBITDA forecast does not show.
The Returns, scenario, and financing tools help assess operating thresholds, cash recovery, and investment performance under edited assumptions.
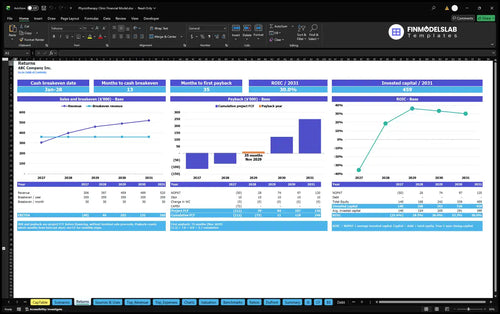
Sales break-even measures revenue needed to cover operating costs. Cash break-even examines cash sufficiency, investment payback tests cash recovery, and annual ROIC relates returns to invested capital.
Positive EBITDA alone cannot establish these measures. No payback period, ROIC, IRR, valuation, or demonstrated cash sufficiency is supplied.
The Returns analysis brings together sales break-even, cash break-even timing, investment payback, and annual ROIC. It is useful for checking whether the revised appointment and salary assumptions support an acceptable investment case.
Dashboard controls compare Low, Base, and High revenue and cost multipliers and model up to four financing facilities. Valuation and sensitivity analyses use the resulting forecasts.
It suits independent operators and advisers planning a one-to-one, self-pay physiotherapy clinic with capacity-constrained treatment sessions.
Evaluate appointment utilization, treatment prices and mix, salary coverage, overhead, opening investment, and financing. The capacity-based engine supports comparisons across clinic plans.
Insurer claims, group classes, mobile visits, and retail sales require different revenue logic. The example is not a physiotherapy industry benchmark.
These answers explain the model’s scope, editable assumptions, and interpretation of the sample projections.
Yes. Change the five visit prices and their service shares in Revenue, keeping total service shares at 100% of sold visits.
It applies annual utilization to 280 monthly one-hour slots, then allocates sold visits across five services.
No. The documented Plano clinic operates as a cash-pay outpatient service without insurance claims, home visits, group billing, or retail sales.
Yes. The two salaried physical therapists include the clinical owner, and the separate administrator is budgeted at 0.75 FTE.
No. Employer taxes, employee benefits, and personal taxes are excluded from the specified operating case despite the workbook’s broader payroll and tax controls.
No. EBITDA excludes capital purchases, financing flows, and other cash adjustments; use the Cash Flow Statement to review projected cash balances.
No. They are illustrative projections based on estimated capacity, prices, salaries, expenses, and owner funding.
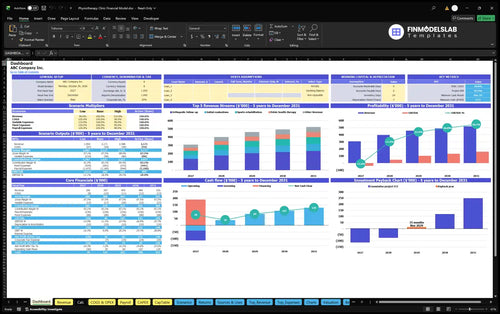
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
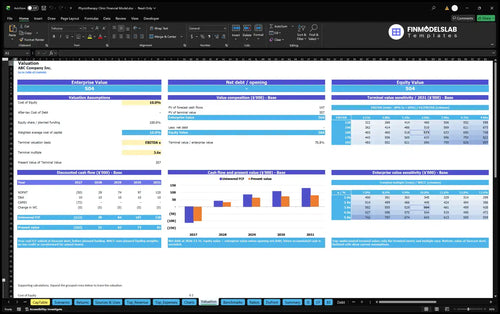
DCF valuation and sensitivity analysis.
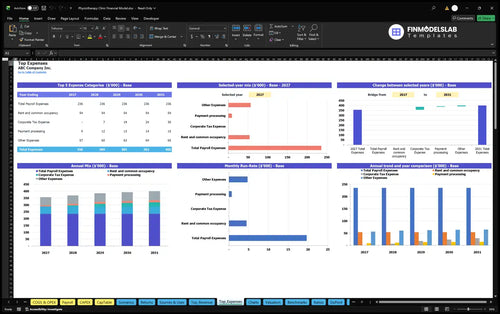
Largest costs and spending trends.
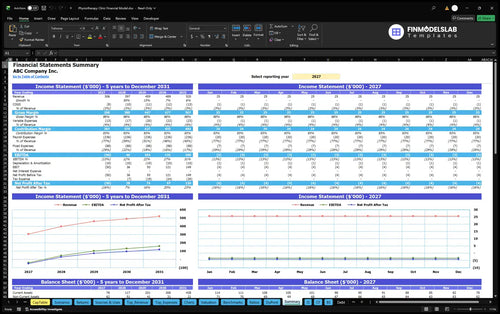
Annual and monthly financial performance.
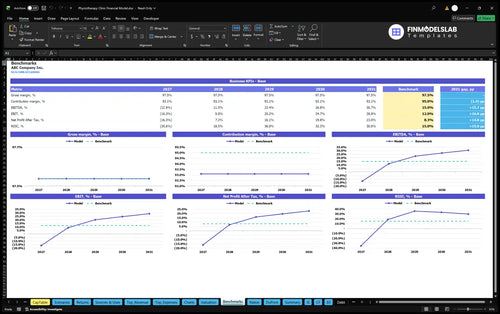
Compare margins and returns to benchmarks.

Building the clinic model from scratch would have eaten up days. This template cut that down fast, and I had a working forecast the same afternoon.

I could finally see where the cash dips were coming and how long our runway really was. That made planning our next hire and funding timing much easier.
I’m not an Excel power user, so this was a relief. The inputs were clear, and I got through the model without needing outside help.