

Revenue & Calc
Set qualified client leads, completed-side conversion, seasonal factors, service shares, and fees; monthly calculations allocate each completed side to one service.


This Real Estate Brokerage Financial Model projects qualified leads, completed transaction sides, negotiated fees, operating expenses, and EBITDA for an independent US brokerage over 2026–2030.
The example covers a leased suburban office, commission-only affiliated agents, a managing broker, and transaction support. It includes residential and small commercial representation, but excludes property ownership, management, mortgage origination, and title services.
Editable operating schedules connect deal activity and personnel costs to financial statements, scenario comparisons, and investment analysis.
Set qualified client leads, completed-side conversion, seasonal factors, service shares, and fees; monthly calculations allocate each completed side to one service.
Plan affiliated agent commissions, listing production, transaction services, lead generation, fees, travel, credit losses, and recurring office costs.
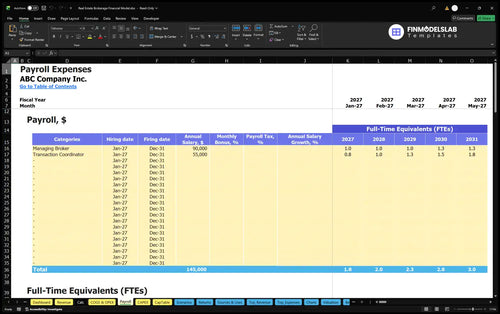
Schedule managing-broker and coordinator staffing, compensation, office equipment, improvements, and depreciation treatment without duplicating affiliated agent commissions.
Adjust Low, Base, and High operating multipliers and review resulting revenue, margins, and EBITDA alongside model settings and financing controls.
Review the Income Statement, Cash Flow Statement, Balance Sheet, Summary, and Checks for earnings, liquidity, financial position, and reconciliations.
Monthly qualified leads, completed-side conversion, and a repeating seasonal multiplier determine total sides before a one-time allocation across five services.
Residential seller and buyer representation each receive 35% of completed sides; residential lease placements receive 15%, commercial sales 5%, and commercial leases 10%. Those shares total 100%, so the model does not count the same completed side twice.
In 2026, 80 monthly leads, 10% completed-side conversion, and seasonal multipliers totaling 12 produce a blended $10,000 per side. These are negotiated-fee planning estimates, not prescribed rates.
The Revenue Forecast organizes lead volume, completed-side conversion, seasonal demand, service shares, and individual fees. The linked monthly calculations turn those inputs into completed sides and sales for each of the five representation services.
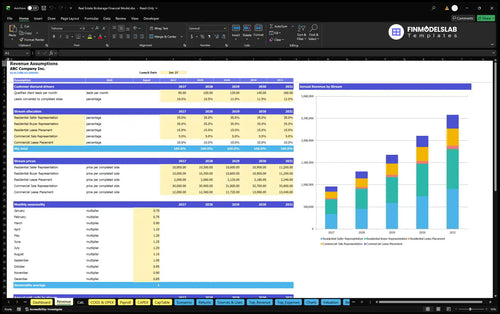
80 leads/month × 10% conversion × 12 combined seasonal months = 96 completed sides; 96 sides × $10,000 blended fee = $960,000 revenue.
In later years, monthly leads increase to 160 and conversion reaches 12% by 2030, while the fee assumptions increase by service. The sales engine remains demand-based; agent headcount is not programmed as a transaction-capacity ceiling.
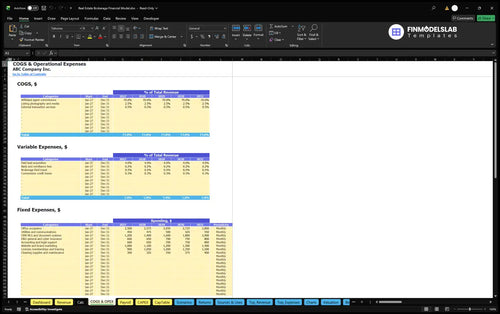
The operating forecast separates percentage-based direct costs, variable selling expenses, monthly fixed expenses, and salaried personnel.
Direct costs equal 73% of brokerage revenue: 70% affiliated agent commissions, 2.5% photography and listing media, and 0.5% external transaction services. Variable operating expenses add 5% for paid leads, banking, field travel, and commission credit losses.
Fixed inputs include office occupancy, CRM/MLS systems, insurance, utilities, licenses, and support; modeled occupancy rises from $2,500 per month in 2026 to $2,800 in 2030.
The COGS and Operating Expenses forecast separates agent splits and transaction delivery costs from variable sales spending and fixed overhead. Changing these rates or monthly expenses changes gross, contribution, and operating margins.
| Expense category | 2026 | 2030 |
|---|---|---|
| Direct costs | $700,800 | $1,883,750 |
| Variable expenses | $48,000 | $129,024 |
| Fixed expenses | $90,600 | $123,000 |
| Salaried payroll | $131,250 | $208,750 |
Amounts are rounded to whole dollars; commission-only agents are included in direct costs, not salaried payroll.
The Payroll Forecast calculates salaried staffing by role and annual-average FTE. The example starts with one managing broker and 0.75 transaction coordinator FTE, increasing to 1.25 and 1.75 FTE respectively by 2030.
Opening owner funding pays for qualifying office assets, distinct prelaunch cash uses, earned-fee receivables, and a working cash reserve.
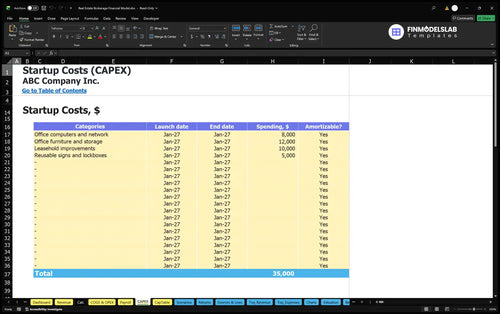
The illustrated capital asset budget totals $35,000: computers and networking, furniture and storage, leasehold improvements, and reusable signs and lockboxes. Separate preopening cash covers formation and licensing, website launch, initial marketing, a refundable deposit, and setup payroll.
The Capital Expenditure Plan records asset purchases, expenditure dates, and whether each item is depreciable. It separates startup investment from the annual operating expenses used to calculate EBITDA.
The example provides $315,093 of initial owner funding, including $25,000 of distinct prelaunch cash, approximately $13,151 in opening earned-fee receivables, and a $241,943 recurring-cash reserve alongside the assets. Rounded components may differ slightly from the funding total.
Working-capital controls specify five receivable days and zero payable or inventory days. The three-month cash reserve is a planning policy, not proof that cash never becomes negative.
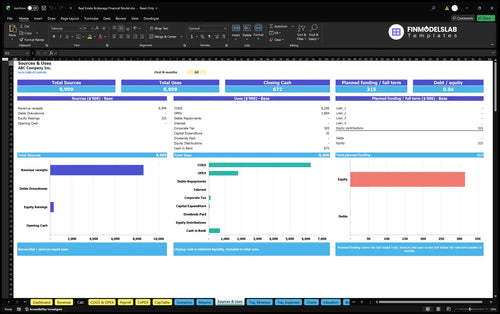
Sources and Uses of Funds shows how planned equity or entered borrowing is allocated among operating payments, investment spending, financing payments, and cash retained. The example confirms owner funding only; it does not establish an external loan commitment.
The Base-case illustration moves from a first-year EBITDA loss to positive projected EBITDA as completed sides and planned fees increase.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $960,000 | $970,650 | -$10,650 |
| 2027 | $1,297,800 | $1,255,984 | $41,816 |
| 2028 | $1,679,040 | $1,575,201 | $103,839 |
| 2029 | $2,105,880 | $1,952,486 | $153,394 |
| 2030 | $2,580,480 | $2,344,524 | $235,956 |
Illustrative projections, not historical brokerage results; values are rounded to whole dollars.
In 2026, $960,000 revenue less $970,650 operating expenses produces negative $10,650 EBITDA. The 2030 example reaches $2,580,480 revenue and $235,956 EBITDA as leads, fees, commissions, and staffing increase.
EBITDA measures operating earnings before interest, taxes, depreciation, and amortization; it does not establish net profit or available cash. The workbook also provides a projected Income Statement, Balance Sheet, and combined financial Summary for further analysis.
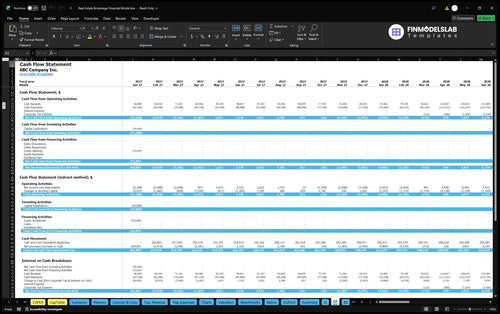
The Cash Flow Forecast separately tracks operating, investing, and financing cash movements, including the timing of brokerage receipts and setup purchases. Use it with the Balance Sheet to assess funding needs rather than treating EBITDA as cash on hand.
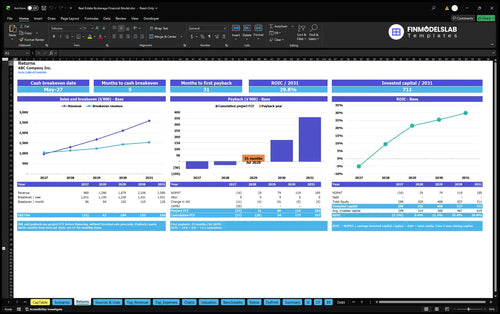
Break-even, payback, and ROIC answer different questions about revenue coverage, cash recovery, and the efficiency of invested capital.
Sales break-even compares projected brokerage revenue with the level needed to cover operating costs. Cash break-even examines when cumulative cash generation turns positive, while investment payback tracks recovery of the project investment through cash flows.
Annual ROIC relates returns to invested capital; it is neither an internal rate of return nor investment payback. None can be reliably inferred from EBITDA alone.
The Returns report compares sales with break-even requirements and tracks project cash flow, cumulative cash flow, payback, and annual ROIC. These measures help evaluate whether revised lead-conversion and expense assumptions support the planned investment.
Dashboard controls compare Low, Base, and High operating multipliers. Debt Controls schedule entered facilities; Valuation offers discounted cash flow and sensitivity analysis without implying verified borrowing or valuation results.
Use the model to evaluate a planned brokerage, revise an operating budget, or present internally consistent assumptions to financial stakeholders.
Founders can test leads, service mix, office costs, and agent splits; existing operators can replace estimates with their own pipeline, negotiated fees, staffing, and local costs.
The example represents a generic suburban market, not a signed lease or verified industry benchmark. Verify local licensing, fees, cash timing, and recruiting capacity.
Key answers about the model’s transaction assumptions, editable schedules, and scope.
Yes. Adjust the affiliated agent commission rate in direct costs; the illustrated selection is 70% of brokerage revenue.
Completed sides are divided among seller, buyer, residential lease, commercial sale, and commercial lease representation using editable service shares and fees.
No. Service fees are editable planning assumptions representing negotiated amounts, not mandated rates or promises of realized commissions.
The example describes 8–16 affiliated commission-only agents, but revenue is based on demand inputs rather than an enforced agent-capacity constraint.
Yes. The declared workbook includes projected Income Statement, Cash Flow Statement, and Balance Sheet reports; the example figures supplied here cover operating results through EBITDA.
No. Cash timing, opening investment, working capital, and financing payments require separate Cash Flow and Balance Sheet review.
No. All displayed revenue, cost, and EBITDA figures are illustrative estimates for the specified brokerage case, not observed industry performance.
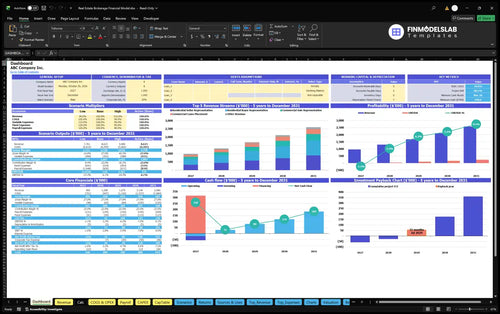
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
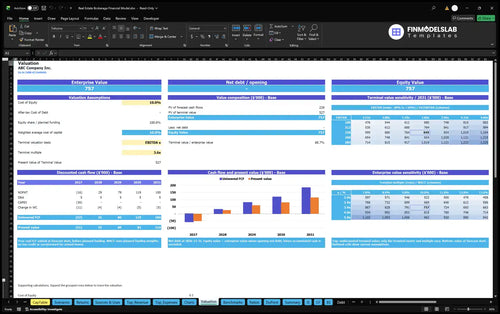
DCF valuation and sensitivity analysis.
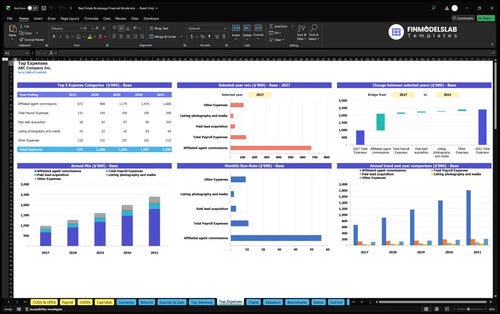
Largest costs and spending trends.
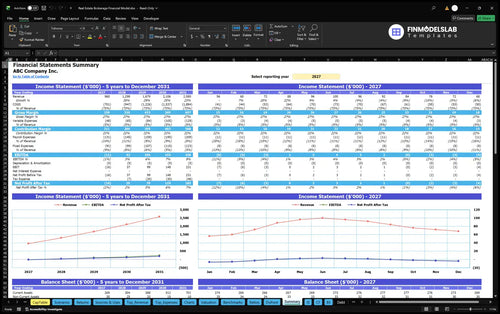
Annual and monthly financial performance.
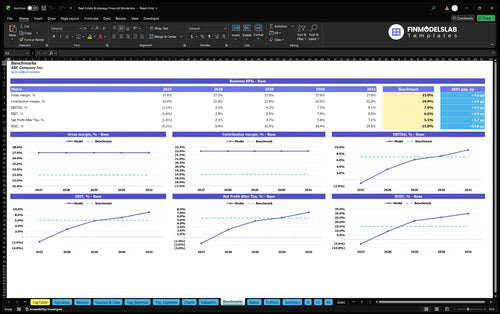
Compare margins and returns to benchmarks.

This template made low, base, and high cases easy to compare, and I saved a full afternoon I would have spent rebuilding tabs by hand. It gave me a clean way to test assumptions before sharing numbers.

I finally had a model with the right sections and outputs, so I wasn’t guessing what investors wanted to see. That clarity helped me prep my deck faster and book a meeting with our lender.
The cash flow tab made runway and shortfalls much easier to see, and I caught a funding gap weeks earlier than I would have otherwise. One clean view of the month-to-month numbers saved me a lot of stress.