

Revenue and Calc
Forecast monthly project completions from qualified opportunities, conversions, seasonality, package mix and prices.


The Solar Panel Financial Model is an Excel template for a regional U.S. turnkey rooftop solar sales and installation contractor. It forecasts project revenue, subcontracted costs, staffing, startup assets and EBITDA for 2026–2030.
The illustrative business uses one office and warehouse with outsourced licensed installation crews. It sells completed turnkey projects, not electricity or solar leases; all estimated inputs are editable.
Connected schedules turn lead generation, project delivery and startup assumptions into financial forecasts and management reports.
Forecast monthly project completions from qualified opportunities, conversions, seasonality, package mix and prices.
Plan subcontracted installation, equipment, permits, freight, selling expenses and overhead.
Model internal staffing, salaries, startup equipment and depreciation separately from outsourced crews.
View Income Statement, Cash Flow, Balance Sheet, Dashboard, Summary and Charts reporting.
Review equity contributions, optional debt schedules, cash allocations and model checks.
Compare scenarios, break-even, returns, valuation and user-selected benchmarks.
Qualified opportunities become expected completed projects, which are split across five residential and small-commercial turnkey packages.
Qualified sales opportunities start at 50 per month in 2026 and reach 110 per month in 2030, while completed-project conversion increases from 10% to 12%. Calendar-month factors adjust demand; fractional completions are planning volumes.
The five offerings are residential 6 kW, residential 10 kW, residential PV with battery, commercial 30 kW and commercial 50 kW. Four entered shares and one residual share split a single pool; there is no crew-capacity ceiling.
The Revenue Forecast connects qualified leads, completed-project conversion, seasonal multipliers, package shares and individual turnkey prices. Its monthly calculations allocate one completion pool across the five packages.
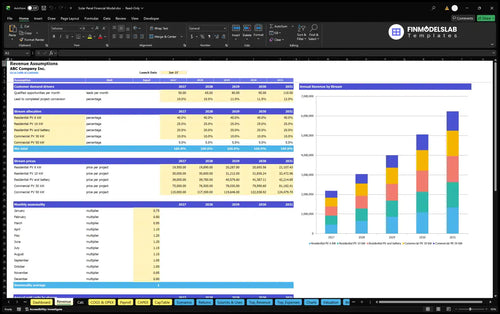
50 qualified opportunities/month × 10% conversion × 12 annual seasonality factors = 60 expected projects; 60 × $36,350 weighted project price = $2,181,000 revenue.
The 2026 package mix is 40% residential 6 kW at $19,500, 25% residential 10 kW at $30,000, and 20% residential PV with battery at $39,000. Commercial 30 kW receives 10% at $75,000 and commercial 50 kW receives 5% at $115,000.
Conversion, opportunities, annual price changes and package mix each influence revenue. These drivers can be adjusted independently.
Direct project expenses, revenue-linked selling expenses, monthly overhead and internal salaries form four distinct cost groups.
COGS totals 65% of projected revenue: panels, inverters, racking and batteries (44%); licensed installation subcontractors (16%); engineering and permits (3%); and freight and lifting (2%). Installation crews are excluded from internal Payroll.
The COGS and Operating Expense Forecast records direct delivery expenses, variable sales-related charges and fixed office overhead. These drivers affect projected gross margin and contribution margin.
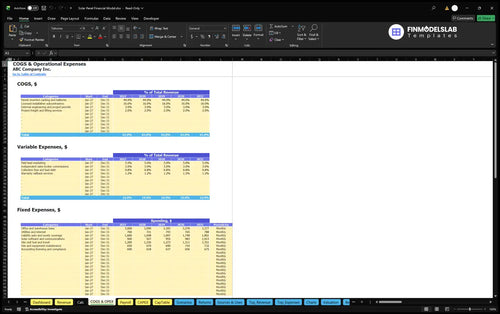
Variable operating costs equal 10% of revenue: paid leads (5%), independent broker commissions (3%), collection fees and bad debt (0.8%), and warranty callbacks (1.2%). Fixed items cover rent, utilities, insurance, software, travel, maintenance and compliance.
The office and warehouse lease begins at $3,000 per month in 2026, reaching approximately $3,377 monthly by 2030. These are monthly amounts, unlike percentage-based project costs.
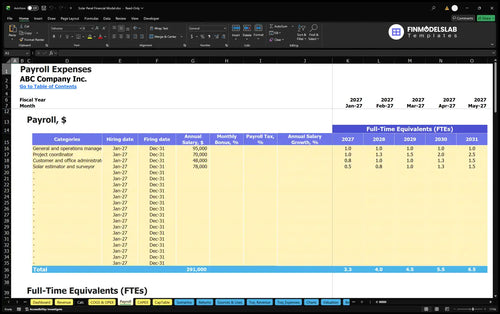
The Payroll Forecast plans annual-average FTE and base salaries for the operations manager, project coordinator, office administrator and solar estimator or surveyor. Coordinator FTE grows from 1 to 2.5 and estimator FTE from 0.5 to 1.5.
| Cost group | 2026 | 2030 |
|---|---|---|
| COGS | $1,417,650 | $4,051,106 |
| Variable OPEX | $218,100 | $623,247 |
| Fixed OPEX | $103,800 | $116,828 |
| Payroll | $240,000 | $459,000 |
| Total expenses | $1,979,550 | $5,250,181 |
Illustrative assumptions. The figures exclude employer taxes and benefits under the documented model scope.
The initial funding calculation groups startup assets, preopening cash costs, working capital and an operating reserve separately from EBITDA.
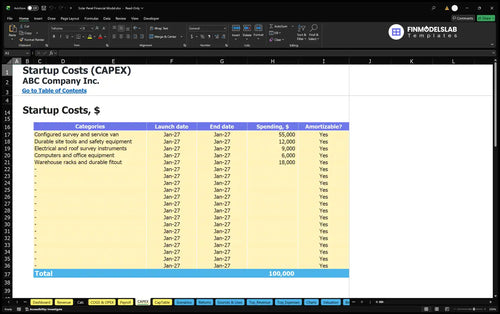
Startup assets total $100,000: a $55,000 van, $12,000 in tools, $9,000 in instruments, $6,000 in computers, and other warehouse fitout. Separate preopening cash expenses total $40,000 for licensing, deposits, training, marketing and wages.
The Capital Expenditure Plan schedules purchased vehicles, roof survey instruments, tools and other durable assets, including their depreciation assumptions. Purchase timing feeds asset and investing cash-flow schedules rather than project COGS.
Working-capital assumptions use 15 receivable days, 12 payable days and 14 inventory days. The example adds $99,811 of estimated net working capital and a $492,161 three-month operating reserve.
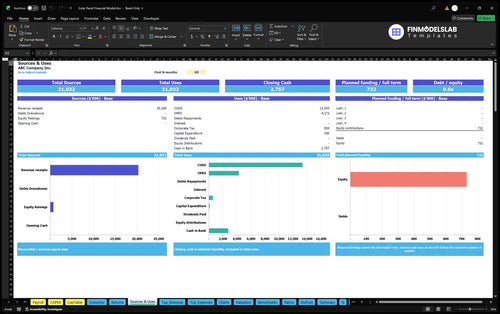
The Sources and Uses of Funds report reconciles cash coming into the company with operating, investment and financing uses. The $731,972 owner-funding assumption combines these startup items; it is not a peak-cash test.
The documented solar installation scenario produces rising annual project revenue, operating expenses and EBITDA across 2026–2030.
| Year | Revenue | Operating expenses | EBITDA |
|---|---|---|---|
| 2026 | $2,181,000 | $1,979,550 | $201,450 |
| 2027 | $3,036,606 | $2,673,369 | $363,238 |
| 2028 | $3,993,638 | $3,431,350 | $562,288 |
| 2029 | $5,057,171 | $4,298,803 | $758,368 |
| 2030 | $6,232,471 | $5,250,181 | $982,290 |
Forecasts, not observed results; displayed amounts are rounded to whole dollars, so some rows may differ by $1 after rounding.
The illustrative 2026 demand assumptions yield 60 completed projects. In 2030, 110 monthly opportunities, 12% conversion and higher prices produce $6,232,471 of projected sales.
Projected EBITDA increases from $201,450 in 2026 (9.2% of revenue) to $982,290 in 2030 (15.8%). EBITDA is not net profit or available cash.
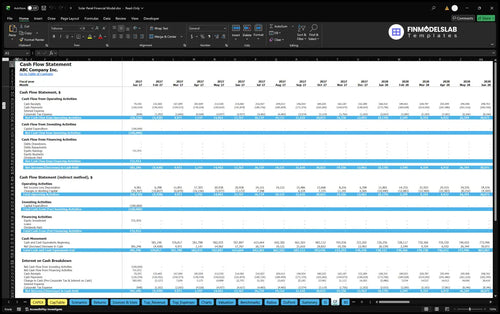
The Cash Flow Forecast separates operating cash receipts and payments from asset investment and financing movements, with monthly opening and closing cash balances. Working-capital timing can cause liquidity needs despite positive EBITDA.
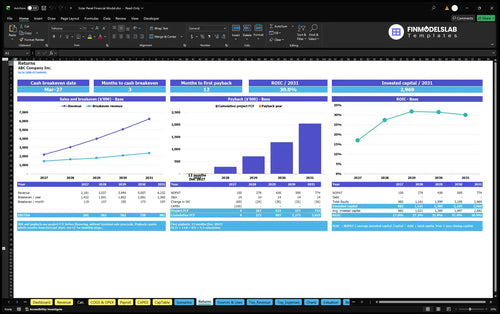
Sales break-even, cash break-even, investment payback, annual ROIC and discounted valuation measure different questions.
The Returns report distinguishes operating sales break-even, cash break-even, cumulative investment payback and annual ROIC. No payback date or ROIC value can be inferred from the supplied EBITDA series.
The Returns report supports break-even, investment payback and annual ROIC analysis using the workbook’s connected operating and financial schedules. These calculations separate operating coverage from cash recovery and invested-capital returns.
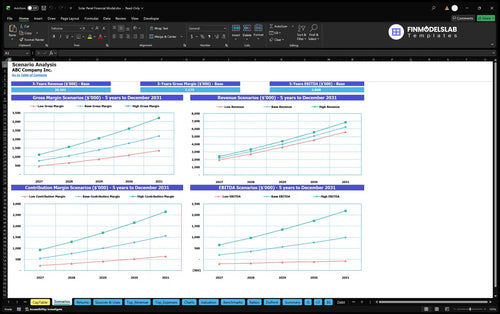
Dashboard Scenario Controls apply Low, Base and High multipliers to revenue, direct costs, variable expenses, fixed overhead and payroll. The Scenarios report compares their effects on margins and EBITDA.
The Financial Scenario Analysis compares Low, Base and High profitability through revenue, gross margin, contribution margin and EBITDA. Lead volume, conversion, prices and mix remain separately editable on Revenue.
Valuation estimates enterprise and equity value through discounted unlevered cash flow and terminal assumptions; Benchmarks compares ratios against user-entered reference values. These reports do not verify an external valuation or industry benchmark.
The workbook fits regional installers that sell completed rooftop PV systems rather than generating electricity for their own account.
Use it to evaluate solar contractor sales funnel requirements, compare residential and commercial packages, plan internal coordination staff, or prepare financial projections for a rooftop solar installation business plan. The case uses one regional office and outsourced crews.
In-house installers, solar leases and asset-owning generators need different assumptions. All figures are illustrative, not local quotes or observed industry averages.
These answers clarify the project-based revenue setup, assumptions and financial reports.
No. It forecasts turnkey installations, not electricity generation, leases or power purchase agreements.
Qualified monthly opportunities are multiplied by completed-project conversion and seasonal factors. One resulting pool is allocated across five packages.
Yes. Four entered shares plus one residual share distribute projects among five packages.
No. Licensed installation subcontractors are included in direct COGS; Payroll covers four in-house management, coordination, administration and estimating roles.
It combines $100,000 in assets, $40,000 of prelaunch costs, $99,811 of working capital and a $492,161 reserve.
No. EBITDA excludes financing, investing and working-capital cash movements. Review Cash Flow and Sources & Uses to evaluate liquidity separately.
No payback month or annual ROIC value is provided. The Returns report contains the supporting calculations for those measures.
Yes. Dashboard multipliers adjust revenue and costs; Scenarios compares margins and EBITDA. Package drivers remain editable in Revenue.
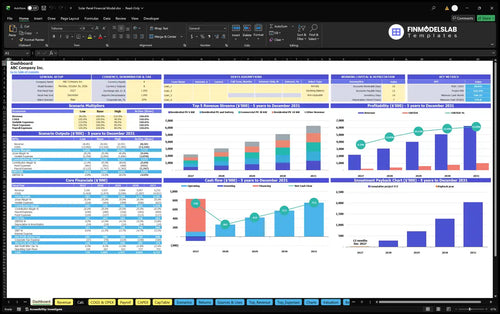
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
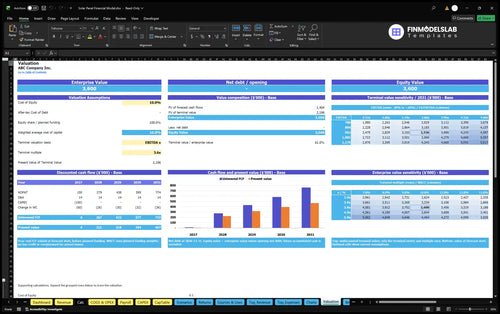
DCF valuation and sensitivity analysis.
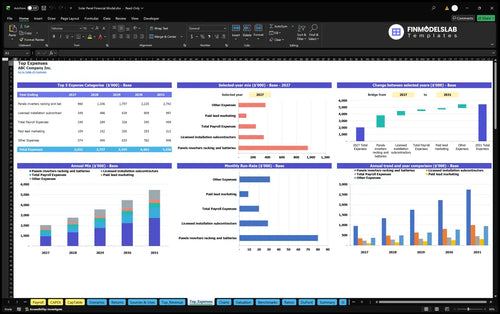
Largest costs and spending trends.
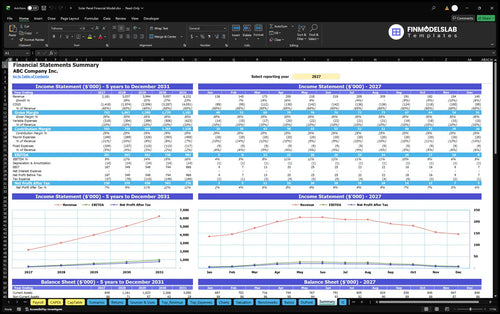
Annual and monthly financial performance.
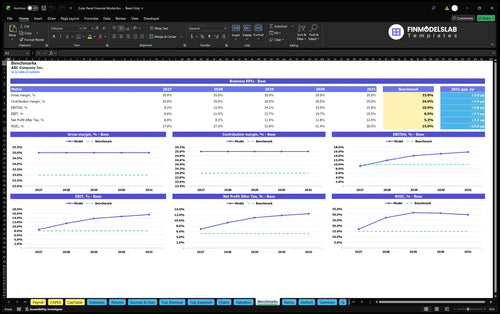
Compare margins and returns to benchmarks.

I stopped worrying that one bad formula would throw off the whole model. The built-in structure saved me about 6 hours of rechecking and made the spreadsheet easier to trust.

I was stuck before I even opened Excel, and this gave me a clean place to begin. I had a working draft in under an hour instead of losing a full day to setup.
I finally knew which outputs mattered and how to present them. The format made my first investor call easier to prepare for, and I booked the meeting with a much cleaner story.