

Revenue and Calc
Set craft-hour capacity, utilization, five service shares, rates, and launch timing. Calc converts these inputs into monthly revenue without using the same hour twice.


The Woodworking Financial Model is an Excel financial planning template for a custom furniture and woodworking shop. It turns available craft hours, workshop utilization, service mix, customer rates, material costs, staffing, and overhead into a monthly operating forecast and connected financial reports.
The illustrative case is a leased 2,500-square-foot workshop in Wichita, Kansas, serving household and small commercial customers. It covers 2026 through 2030, starts with three production FTE, and models a pass-through LLC; its assumptions are editable planning estimates, not established industry averages.
The workbook links shop-specific operating inputs to financial statements, management analysis, and funding schedules.
Set craft-hour capacity, utilization, five service shares, rates, and launch timing. Calc converts these inputs into monthly revenue without using the same hour twice.
Plan materials, selling expenses, shop overhead, and staff salaries separately. Payroll schedules FTE, pay, hiring dates, and monthly personnel costs.
Enter equipment, capital spending dates, owner contributions, and optional borrowing. Debt schedules calculate interest and principal payments from selected terms.
Income Statement, Cash Flow, and Balance Sheet provide monthly reporting; Summary combines annual and selected monthly views. Documented sample results stop at EBITDA.
Sales come from one workforce-matched craft-hour capacity pool, its sold utilization, and materials-inclusive service rates.
Monthly craft capacity is 480 hours in 2026–2027, 560 in 2028, and 640 in 2029–2030. Sold utilization increases from 55% to 76%, without seasonal adjustments.
Allocate sold hours once: 35% tables and desks, 30% cabinets and shelving, 10% decor, 15% furniture repair, and 10% refinishing. The last share is residual, keeping one 100% pool rather than separate demand forecasts.
The Revenue Forecast shows craft-hour capacity, sold utilization, five service shares, and materials-inclusive hourly rates. Calc translates these into monthly sales by woodworking service.
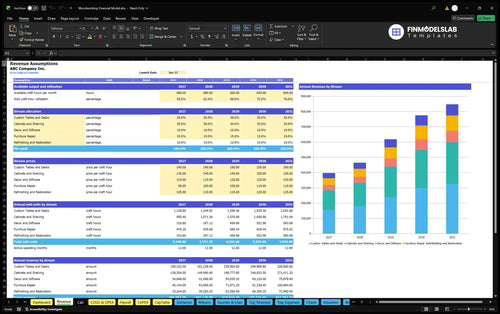
480 available hours/month × 55% sold utilization × 12 months = 3,168 sold hours; 3,168 × $125.25 weighted customer rate/hour = $396,792 revenue.
Tables and desks rise from $140 to $160 per sold hour between 2026 and 2030; cabinets and shelving rise from $135 to $155. These materials-inclusive customer rates are not worker wages.
January 31, 2026 activates a full January of sales. A later launch leaves earlier revenue at zero while retained salaries and shop overhead continue.
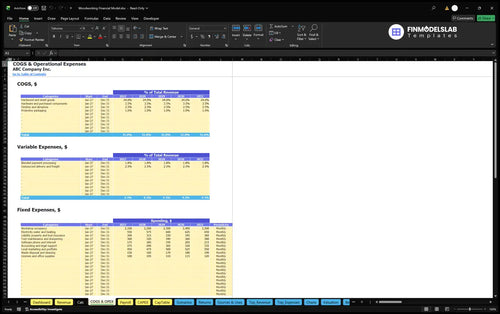
The model separates revenue-linked direct costs, variable selling expenses, fixed workshop spending, and salaried payroll.
Estimated COGS equals 31% of sales: wood 24%, hardware 3.5%, finishes 2.5%, and packaging 1%. Separate variable expenses are payment processing at 1.8% and outsourced delivery at 2.5% of revenue.
Fixed expenses cover rent, utilities, insurance, maintenance, professional support, marketing, and supplies. Monthly workshop occupancy rises from $2,100 to $2,500 between 2026 and 2030, payable for twelve months annually.
The COGS and Operating Expenses forecast separates material inputs, processing fees, delivery, and fixed workshop charges. Revise percentages and monthly budgets to test operating margins.
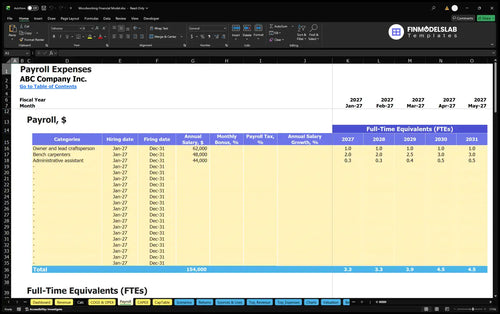
Payroll is not counted again in materials or overhead. The owner’s annual base is $62,000; bench carpenters increase from two to three FTE, while admin support rises from 0.25 to 0.5 FTE. Employer taxes and benefits are excluded.
The Payroll Forecast tracks staff roles, annual-average FTE, salary assumptions, and monthly personnel costs. Illustrated payroll grows from $169,000 in 2026 to $228,000 in 2030.
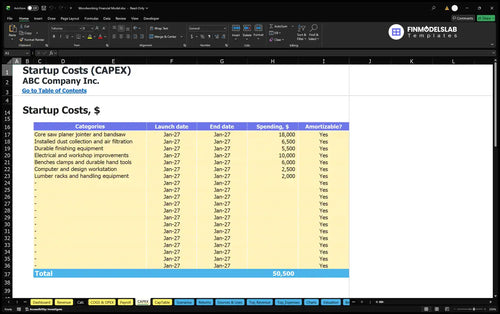
Startup assets, preopening payments, working capital, and funding are planned separately from recurring operating expenses.
The $50,500 startup asset budget includes core machines ($18,000), dust collection ($6,500), finishing equipment ($5,500), and improvements ($10,000). Benches, tools, a design workstation, and lumber racks account for other planned assets.
The Capital Expenditure Plan schedules machinery, equipment, and workshop improvements by acquisition date and depreciable status. Investment spending and depreciation are tracked separately from EBITDA.
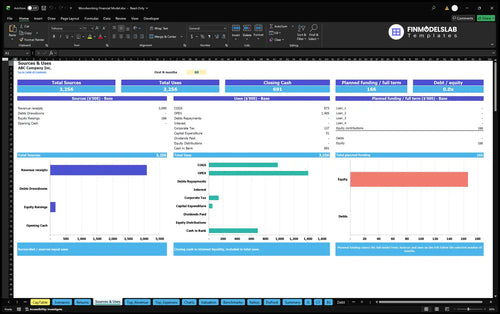
Preopening uses also include $13,700 in cash items, $11,738 of working capital, and a $90,467 three-month reserve. Together with assets, these total $166,405 of estimated owner funding, not a tested peak cash requirement.
Receivables, payables, and inventory are set at 6, 15, and 30 days. These timing assumptions affect cash and balance-sheet calculations, not sales or EBITDA directly.
The Sources and Uses of Funds report links equity, potential debt, and business receipts with operating, investing, and financing cash uses. No outside borrowing is confirmed in this case.
The documented Wichita workshop example increases sold hours and customer rates while carrying higher material and staffing costs.
| Year | Revenue | Operating Expenses | EBITDA |
|---|---|---|---|
| 2026 | $396,792 | $361,868 | $34,924 |
| 2027 | $465,149 | $388,698 | $76,451 |
| 2028 | $618,038 | $475,968 | $142,071 |
| 2029 | $775,526 | $562,661 | $212,866 |
| 2030 | $847,795 | $590,872 | $256,923 |
Illustrative scenario projections, not observed results. Displayed totals are rounded to whole dollars, so subtotals may differ slightly.
Illustrative annual sales increase from $396,792 to $847,795 between 2026 and 2030. Total operating expenses count COGS, variable costs, fixed costs, and Payroll once; EBITDA grows from $34,924 to $256,923.
The Income Statement also models depreciation, interest, taxes, and net profit, but only EBITDA figures are supplied for this case. The table does not establish net income or distributable cash.
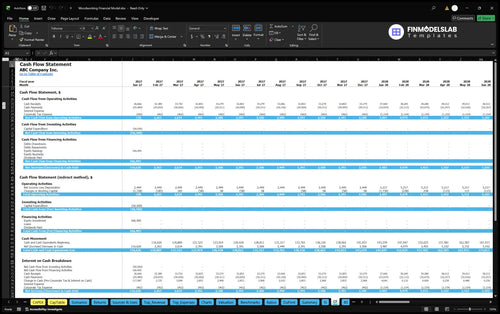
The Cash Flow Forecast shows operating, investing, and financing receipts and payments with a cash reconciliation. Read it with the Balance Sheet to evaluate collections, inventory, purchases, funding, and potential liquidity gaps.
Use the workbook reports to test whether the workshop covers operating costs and can support its startup investment.
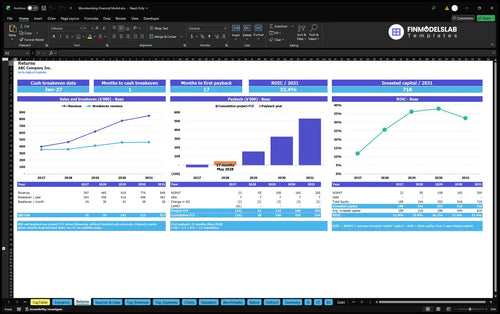
Returns distinguishes sales break-even, cash break-even, investment payback, and annual ROIC. These measure operating cost coverage, cash sufficiency, investment recovery, and capital efficiency respectively.
The supplied case establishes no payback date, ROIC percentage, or IRR. Evaluate returns using your own cash flow and funding assumptions, not EBITDA alone.
The Returns analysis compares sales with break-even requirements and tracks cumulative free cash flow, investment payback, and annual ROIC. Accounting earnings are not the same as recovered cash.
Dashboard Low, Base, and High multipliers adjust sales and expenses to compare EBITDA. Valuation sensitivities, KPI benchmarks, and checks are available, but no numerical valuation result is documented.
Answers to the most important questions about inputs, forecasts, costs, and reporting.
One shared pool of available craft hours is multiplied by sold utilization, allocated across five services, and priced at each service’s customer rate per sold craft hour.
Yes. Edit monthly craft-hour availability, utilization, five service allocations, and annual hourly selling rates on the revenue planning inputs.
Yes. Customer revenue rates include materials; wood, hardware, finishing supplies, and packaging are separately recognized as direct operating costs.
The model leaves sales before the revised launch month at zero while retained payroll and paid fixed workshop expenses continue according to their schedules.
No. The illustrated owner, bench carpenter, and administrative salaries are accounted for in Payroll and excluded from the listed COGS and fixed expense categories.
No. It combines estimated startup assets, prelaunch cash, working capital, and a three-month reserve; it is not tested proof of peak funding coverage.
Yes. Dashboard debt controls, financing schedules, Returns, Scenarios, and Valuation support analysis; specific loan approval, ROIC, payback, and valuation outcomes are not supplied.
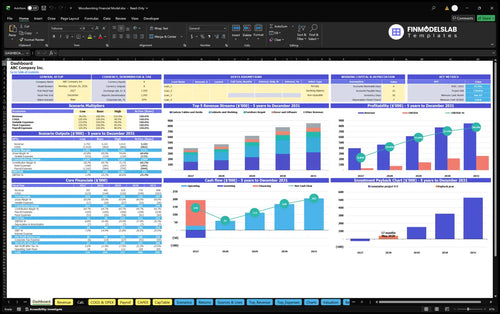
KPIs, forecasts, and cash flow at a glance.
Key assumptions and calculations driving revenue forecasts.
Funding sources, spending, and closing cash.
Cash break-even, payback, and ROIC.
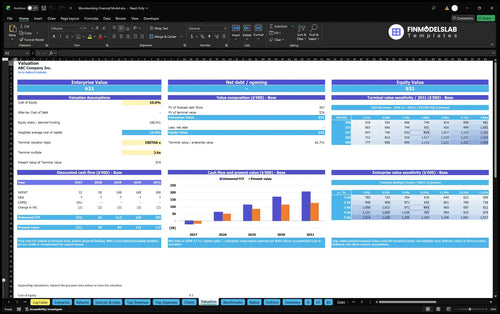
DCF valuation and sensitivity analysis.
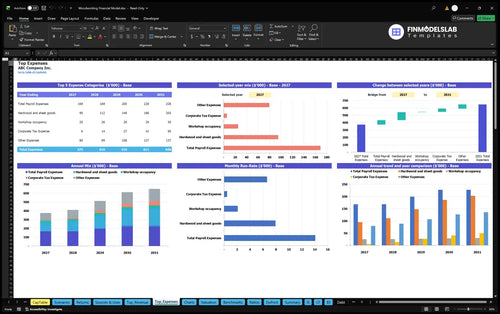
Largest costs and spending trends.
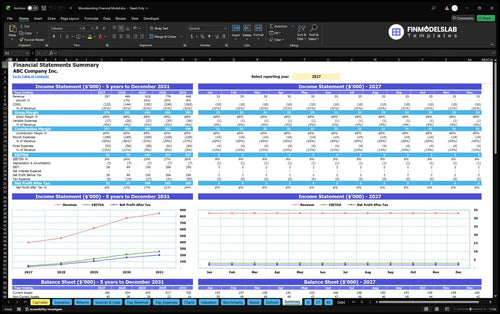
Annual and monthly financial performance.
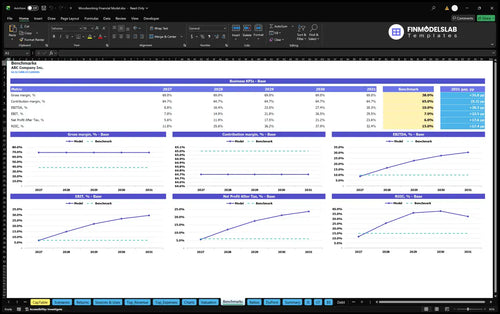
Compare margins and returns to benchmarks.

I used to waste time juggling low, base, and high cases, but this template kept them organized in one place. It saved me a few hours and made my assumptions easy to compare.

I’m not deep into Excel, so the guided layout and clean inputs made the model much less technical. I got through the workbook without outside help and had a clear forecast ready the same day.
The model made it easy to see margins and break-even instead of guessing from a messy sheet. I booked a lender meeting with the numbers already laid out in a way I could explain.