Does Owner Income in a Car Wash Depend More on Volume or Margin?
For a U.S. single-site, owner-operated express exterior car wash with free vacuums, a realistic planning range is roughly $32,000 to $513,000 a year in owner income after modeled tax and reinvestment reserves, with a base case of $241,560 on $1.86 million of annual revenue. The base case assumes about $40,000 a month of non-owner payroll, $42,000 of fixed and semi-fixed overhead, $5,000 of marketing, and $22,000 of debt service. It excludes a separate hired general manager, personal spending, and any tax outcome beyond the model's 22% tax reserve. This scope is an express tunnel, not a hand-wash, detailing shop, self-serve bay, or full-service interior operation; that distinction matters because labor, throughput, pricing, and capital intensity differ materially.
Owner income$242KNet margin13%Revenue for target pay$1.76MBusiness difficultyHard
What does a realistic car wash owner-income model assume?
The base case is deliberately below the economics of the largest national chains but high enough to represent a mature single express tunnel. Mister Car Wash reported a 32.8% adjusted EBITDA margin in 2025 and said subscription sales represented 76% of total wash sales; its filing also warns that EBITDA excludes debt service, replacement capital, working-capital needs, and other cash uses. Those exclusions are exactly why this article does not treat EBITDA as owner take-home. See the company's 2025 SEC filing.
For this model, monthly revenue is $155,000, gross margin is 90% after chemicals, wash materials, payment fees, and variable water or sewer costs, while all payroll is shown separately. The 90% gross margin is a planning assumption reconstructed to avoid double-counting labor; it is not copied from a P&L that embeds wash labor in cost of sales. Base operating costs are $109,000 a month including debt. Break-even before owner reserves and owner pay is therefore about $121,111 a month: $109,000 divided by 90%. To fund a $15,000 monthly owner target after a 22% tax reserve and 12% reinvestment reserve, the fixed calculator formula raises the requirement to $146,364 a month, or about $1.76 million annualized.
Owner income calculator
Test how car-wash revenue, margin, staffing, debt, and reserves translate into owner cash.
i
Planning note: Research-based planning estimate only. It is not guaranteed salary, tax advice, or owner distribution advice.
Which six levers move car wash owner income the most?
Express-wash economics are unusually sensitive to recurring membership revenue and fixed-site utilization. Industry data reported by the International Carwash Association shows average monthly member revenue of about $30, with a reported $26 to $35 distribution, which makes member count a cleaner revenue bridge than guessing one blended ticket. See the Q4 2024 industry report. The six ranked levers below are the same six expanded later in the article.
1
Membership count and retention
$30/member/mo
At the industry-reported average, 100 net active members add roughly $3,000 of recurring monthly revenue before usage-driven cost.
2
Cars per day and throughput
346/day base
The base planning case needs about 10,400 monthly visits, so traffic capture, queue speed, and uptime determine whether the site can absorb demand.
3
Retail price and package mix
3.1% price lift
Recent industry data found a 3.1% median increase in retail price per visit, showing that mix and price can lift sales without adding equal traffic.
4
Labor productivity
$40K/mo payroll
The base model keeps owner labor out of payroll and requires schedule discipline so added volume does not automatically require proportional staffing.
5
Equipment uptime and overhead
$42K/mo overhead
Rent, utilities, repairs, reclaim systems, vacuums, insurance, software, and property costs keep running even when weather or downtime cuts wash volume.
6
Debt and reserve discipline
34% base reserves
Debt is paid before owner cash, then the base case holds 22% for taxes and 12% for reinvestment before treating the remainder as owner income.
Want to test the assumptions in a full car wash forecast?
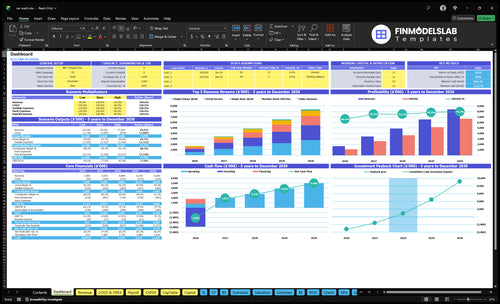
The Car Wash Excel Financial Model for Startups includes a business-specific dashboard and forecast structure for testing revenue, margins, staffing, cash flow, and scenarios. The dashboard preview is most useful for checking whether member growth, retail traffic, operating costs, financing, and cash reserves tell one consistent story rather than treating owner pay as a percentage of sales.
What revenue and wash volume support a $180,000 owner target?
Under the base cost structure, about $146,364 of monthly revenue, or $1.76 million annualized, supports a $15,000 monthly owner target after the model's 22% tax reserve and 12% reinvestment reserve. The base operating month at $155,000 therefore has roughly $8,600 of revenue cushion above that target-revenue threshold, but only $5,130 of after-reserve owner cash above the target. Current subscription pricing varies by market; one Colorado express-wash location lists unlimited plans from $24.99 to $39.99 per month, while industry data has reported about $30 average monthly revenue per member. See the current location pricing.
A useful revenue bridge is 2,800 active members at $30 per month, producing $84,000, plus about $71,000 of retail wash revenue. If the average retail transaction is modeled at $18, that is about 3,944 retail transactions a month. Assuming members use the wash 2.3 times per month, a planning assumption for capacity testing rather than a sourced benchmark, total site volume is roughly 10,400 cars a month or 346 per day. The wash does not need to hit that exact mix, but member count, retail traffic, and tunnel capacity must reconcile to the $155,000 top line.
Base revenue build
2,800 members × $30 = $84,000 monthly member revenue.
$71,000 retail revenue ÷ $18 = about 3,944 retail transactions.
Base annual revenue = $155,000 × 12 = $1.86 million.
Pre-reserve operating break-even is about $121,111 per month.
What can break the math
Member usage rises faster than member revenue.
Retail discounts lower the effective transaction value.
Queueing or equipment downtime caps cars per hour.
Weather shifts retail demand even when debt and rent stay fixed.
Can a car wash run without the owner working as manager?
Yes, but the same site will usually distribute less cash unless revenue rises enough to cover hired management. The base calculator assumes the owner covers the general-manager function, so owner compensation is the residual output, not an additional salary buried in labor. In the broad BLS category that contains much car-wash employment, 2023 data showed a median wage of $14.25 per hour for cleaners of vehicles and equipment and a median of $29.55 per hour across management occupations; those are national category proxies, not car-wash-specific pay quotes. See the BLS industry wage table.
If you replace the owner's daily management with roughly $6,000 to $7,000 of added monthly loaded payroll, the base model's after-reserve owner income falls by about $47,500 to $55,400 a year if revenue does not change. That is because every extra $1 of payroll reduces profit before reserves by $1, then only 66 cents of the former profit would have reached the owner after the 34% combined reserve. A fully staffed franchise format can be larger still: Tommy's Express says its full-size low-labor model is built to run with 12 full-time team members, while its franchise requirements show the substantial liquidity and net-worth hurdle for full-size ownership.
Owner-operated economics
Owner performs the general-manager role.
Labor line covers non-owner employees only.
$241,560 base output is total residual owner cash after modeled reserves.
If the entity pays owner wages, reclassify part of that residual rather than adding a second cost.
Manager-run economics
Add manager wages and payroll burden to labor cost.
Do not also call the replaced owner labor a distribution.
Require higher revenue before labeling ownership passive.
Track manager payroll against member retention, uptime, and labor hours per 100 cars.
How do memberships and seasonality change cash flow?
Memberships stabilize revenue, but they do not eliminate churn, weather, or usage risk. A February 2025 industry report put median member lifetime at 14.5 months and overall average monthly churn at 7.2%; it also reported seasonal differences by region. That means a wash with 2,800 members may need about 200 replacement members in a typical month just to offset 7.2% churn before growing the book. See the membership and seasonality findings.
Marketing therefore has two jobs: acquire new members and keep existing ones active and paying. In the model, $5,000 monthly marketing is separate from card fees and other direct costs. If 200 replacement memberships were required and every replacement came from paid acquisition, $5,000 would imply only $25 per replacement member before any growth spend; the practical mix will include driveway conversion, referrals, reactivation, local search, and organic repeat customers. A later 2025 industry release reported members' first-36-month lifetime value at $440 versus $106 for repeat retail customers, making retention a cash-flow lever rather than a vanity metric. See the Q1 2025 retention data.
Member growth can raise sales without matching retail traffic growth.
Family and multi-car plans can lengthen retention.
Prepaid recurring revenue helps cover fixed debt and occupancy.
Cash-flow pressures
Churn forces continuous replacement acquisition.
Rain, snow, road salt, and regional patterns move retail traffic.
Heavy member usage consumes chemicals, water, and equipment life.
Debt, base labor, rent, and maintenance continue through slow weeks.
Key Takeaways
The base owner-operated express wash produces $241,560 of annual owner income after modeled reserves on $1.86 million of sales.
Operating break-even is about $121,111 monthly revenue, while supporting $180,000 annual target owner pay requires about $146,364 monthly revenue.
Membership count, retention, cars per day, pricing, payroll productivity, uptime, and debt service decide whether revenue becomes distributable cash.
Owner salary and distributions are different labels for compensation and residual cash; do not count the owner's work twice or distribute money needed for taxes, repairs, debt, and working capital.
What must be paid before car wash cash is safe to distribute?
Revenue is not profit, and accounting profit is not automatically distributable cash. Start with revenue, subtract non-labor direct wash costs to get gross profit, then subtract payroll, occupancy, repairs, insurance, software, utilities, marketing, and other operating overhead. EBITDA or operating profit can still overstate what an owner can safely take because debt principal and interest, tax payments, replacement equipment, and working capital come later. The SBA notes that its 7(a) program can finance real estate, buildings, machinery, equipment, working capital, and business acquisitions, with most 7(a) loans capped at $5 million; actual lender terms and payments vary. See the SBA 7(a) guidance.
For this model, debt service is $22,000 monthly and comes before reserves. Then 22% of positive profit is reserved for taxes and 12% for reinvestment. The tax percentage is not a forecast of the owner's final tax bill. The IRS explains that people in business for themselves generally may need estimated tax payments when tax is not fully covered by withholding, which is why an owner should treat a tax reserve as restricted cash until the real obligation is known. See IRS Publication 505 for 2026.
Reinvestment is equally real. Tunnel brushes, pumps, blowers, pay stations, reclaim systems, vacuum motors, pavement, drainage, and signage age whether or not the income statement shows an immediate expense. EPA guidance notes that commercial car washes often recycle water or treat wash water before sanitary-sewer release, and local discharge requirements can add equipment, inspection, and maintenance obligations. See the EPA vehicle-washing guidance. A profitable wash that empties its bank account into owner draws can therefore become cash-poor after one equipment failure, tax deadline, or slow-weather month.
Keep the definitions separate
Revenue: customer and membership sales before expenses.
Gross profit: revenue after direct non-labor wash costs in this model.
Operating or EBITDA-like profit: profit before financing, taxes, and capital replacement, depending on definition.
Owner income: residual cash after modeled debt service and reserves.
Distribution gate
Payroll and payroll taxes are funded.
Debt service and vendors are current.
Tax reserve is untouched until liability is known.
Repair, replacement, and working-capital reserves remain adequate after the draw.
What do low, base, and high owner-income cases look like?
The modeled range is intentionally wide because fixed debt and overhead make the downside asymmetric. At $110,000 monthly revenue, the low case still pays $93,000 of operating costs after gross margin and leaves only $2,660 monthly owner income after reserves. The high case increases revenue to $220,000 but also raises payroll, overhead, marketing, tax reserve, and reinvestment rather than pretending extra sales are free. These are planning cases, not earnings promises.
Owner income scenarios
One owner-operated express tunnel, with costs scaled to each revenue case and owner income shown after modeled tax and reinvestment reserves.
Low, base, and high planning cases for a single-site U.S. express exterior car wash.
Low CaseConservative
Base CasePlanning
High CaseStrong site
Launch modelTraffic and revenue build
$110K monthly revenue
About 1,600 members
About 250 cars/day
$155K monthly revenue
About 2,800 members
About 346 cars/day
$220K monthly revenue
About 4,000 members
About 480 cars/day
Typical setupOwner role and margin
Owner-operated
88% gross margin
Lean shift coverage
Owner-operated
90% gross margin
Normal maintenance plan
Owner-operated
91% gross margin
More peak coverage
Cost driversMonthly cash load
$31K labor
$36K overhead
$4K marketing
$22K debt
$40K labor
$42K overhead
$5K marketing
$22K debt
$50K labor
$50K overhead
$7K marketing
$22K debt
Owner income rangeAfter modeled reserves
$31,920
$241,560
$512,640
Best fitHow to interpret it
Slow ramp, weaker member base, or weather-sensitive site where debt absorbs most profit.
Mature single-site operator with recurring members and disciplined labor, pricing, maintenance, and reserves.
High-traffic site with strong retention and throughput, supported by more staffing and maintenance.
i
Planning note: Scenario figures are researched planning assumptions, not guaranteed earnings, salary promises, tax advice, or distribution forecasts.
Six detailed income drivers for a Car Wash
These six levers show where a single express tunnel gains or loses distributable owner cash: recurring revenue, throughput, realized price, labor, uptime, and financing discipline.
1. Membership count and retention
Turn recurring members into a revenue floor
The Q4 2024 industry report put average monthly member revenue near $30. At that level, 2,800 members create about $84,000 a month. Add 100 net members and recurring revenue rises about $3,000 monthly; lose 100 and it falls by the same amount. At 7.2% monthly churn, 2,800 members also imply roughly 202 replacements before growth, so retention directly protects cash against fixed rent and debt.
Track member economics weekly
Measure whether new joins outrun cancellations without expensive discounting.
Active members and net adds
Monthly churn percentage
Average member revenue
Acquisition cost per net member
More retained recurring revenue raises the amount available for reserves and owner distributions.
2. Cars per day and tunnel throughput
Make capacity math agree with the sales forecast
The base case implies about 346 cars a day: roughly 6,440 member visits if 2,800 members average 2.3 visits monthly, plus about 3,944 retail transactions. The 2.3 figure is a capacity assumption, not a benchmark. Another 30 retail cars per day at an $18 transaction adds about $16,200 monthly revenue and $14,580 of gross profit at a 90% margin before added staffing or overhead.
Watch throughput, not just traffic
Separate weak demand from a physical bottleneck.
Cars per hour by daypart
Queue abandonments
Member versus retail visits
Downtime during open hours
Demand only improves owner income when the site can process it reliably.
3. Retail price and package mix
Raise realized revenue per visit without losing demand
The Q1 2025 industry report found median retail visits up 3.9% and median price per visit up 3.1%. With about $71,000 of modeled monthly retail revenue, a 3% realized-price lift adds roughly $2,130 of sales and $1,917 of gross profit at a 90% margin. Track collected revenue after coupons and comps, not the menu-board price.
Track realized price by channel
Watch mix and discounts beside traffic.
Retail revenue per paid visit
Package mix by tier
Discount and comp rate
Retail-to-member conversion
Price helps owner cash only when contribution gains exceed lost volume or churn.
4. Labor productivity and owner role
Schedule labor against cars, not habit
The base plan uses $40,000 of monthly non-owner payroll, 25.8% of revenue. The 2023 BLS industry table shows vehicle-cleaner wages vary by role and market, so local hiring rates should replace this planning cost. A five-point labor overrun equals $7,750 a month. If the owner steps away and adds $7,000 of monthly management payroll, modeled annual owner income falls about $55,440 after reserves.
Measure labor per unit of demand
Do not cut staffing until service, safety, and uptime fail.
Labor dollars per 100 cars
Cars per paid labor hour
Overtime and call-off coverage
Owner versus manager hours
Owner labor must be classified consistently before calling the residual passive income.
5. Equipment uptime and fixed overhead
Treat maintenance as revenue protection
The model carries $42,000 a month of fixed and semi-fixed overhead, a planning assumption covering occupancy, base utilities, insurance, repairs, software, and administration. A three-hour outage in a 12-hour selling day removes 25% of that window while most fixed costs continue; against roughly $5,167 of base daily revenue, about $1,292 of sales is at risk. EPA guidance also highlights wash-water treatment and recycling considerations that can affect equipment and maintenance needs.
Track the cost of downtime
Connect stoppages to lost cars and repair spending.
Uptime during selling hours
Unplanned downtime minutes
Repair spend per 1,000 cars
Utility and reclaim cost per car
Reserve cash before distributions so deferred maintenance does not become an emergency draw.
6. Debt service, taxes, and reinvestment reserves
Do not confuse operating profit with spendable owner cash
The base wash produces $30,500 of monthly profit before reserves after $22,000 of modeled debt service. It then sets aside $6,710 for taxes and $3,660 for reinvestment, leaving $20,130 for the owner. The debt payment is an assumption, not a lender quote; replace it with the actual amortization schedule and adjust the replacement reserve for equipment age and warranty coverage.
Set a distribution policy before taking draws
Owner pay should follow a cash policy, not the checking-account balance.
Debt-service coverage
Tax reserve versus liability
Repair and replacement reserve
Minimum operating cash
The base $5,130 monthly cushion above target pay is not guaranteed recurring distribution capacity.
Disclaimer
Financial Models Lab provides this article and its calculators for educational and business-planning purposes only. They are not personalized financial, accounting, tax, legal, investment, or lending advice. Figures shown are illustrative planning estimates based on publicly available sources, observed market information, and stated assumptions; they are not guaranteed benchmarks, forecasts, quotes, or expected results. Actual startup costs, revenue, expenses, margins, funding needs, and break-even timing vary by location, date, business size, operating model, financing, and execution. Review the cited sources and replace sample assumptions with current local data, supplier quotes, and your own operating inputs. Calculator and financial-model outputs change when assumptions change. Consult qualified professional advisers before making material commitments. Financial Models Lab sells related templates and may link to its own products. Please report suspected errors through our contact page.
Car Wash Bundle
Choosing a selection results in a full page refresh.